Firefly Aerospace Today
FLY
Firefly Aerospace
$25.21 -0.10 (-0.41%) As of 02:52 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $14.44
▼
$62.17 - Price Target
- $35.33
Firefly Aerospace NASDAQ: FLY is still a small company, but it represents an aggressive opportunity in space development. While Q3 revenue came in at less than half of what Rocket Lab NASDAQ: RKLB reported for the same period, its backlog, contract wins, and expansion plans set it up to catch up quickly. The opportunity for investors is getting into this market while shares remain well below earlier highs. Firefly grows at a hyperpace, although the timeline for profitability remains uncertain.
Q3 results reflect a company executing its strategy and in demand. Highlights include a landmark deal with AST SpaceMobile NASDAQ: ASTS to provide hardware, intellectual property (IP), and support services. Valued at about $1.3 billion, the deal includes about $800 million in consideration for a license to manufacture Miranda and Vira engines, with the remainder covering engine deliveries and engineering services. The deal validates the technology and adds to Firefly's growth prospects. Its existing backlog represents nearly four years of activity at the Q3 pace, even before accounting for the AST agreement. The deal could also reduce launch risks for AST SpaceMobile.
Firefly Aerospace Triggers Momentum Boost With Q3 Results
Firefly Aerospace’s Q3 results showed accelerating momentum, with revenue up about 260% year over year, 7.3% above expectations, and improved guidance. Revenue was driven by numerous projects, while work on five lunar missions also improved visibility. Contract wins include an extension of a multiyear launch agreement with Lockheed Martin NYSE: LMT, providing clarity into the early next decade.
Margin news is mixed, with adjusted losses swelling but tied to strategic execution. Work included expanding a cleanroom facility that now enables the simultaneous manufacture of up to 12 lunar landers and orbital vehicles. Key details also include the adjusted losses, which came in a nickel below consensus despite the heavy spending.
Guidance is a catalyst. Guidance improvement compounded the quarterly strength and backlog growth, coming in ahead of consensus and forecasting approximately 24% sequential growth, though it remains cautious. While launch delays are impacting the outlook, strength in other segments, including defense software, offsets it, and the five parallel lunar missions provide a solid baseline, laying the groundwork for upside surprises.
Analysts Lift Targets: Reinforce Upside Potential for Firefly Investors
Firefly Aerospace Stock Forecast Today
12-Month Stock Price Forecast:$35.7550.70% UpsideModerate BuyBased on 12 Analyst Ratings | Current Price | $23.72 |
|---|
| High Forecast | $54.00 |
|---|
| Average Forecast | $35.75 |
|---|
| Low Forecast | $25.00 |
|---|
Firefly Aerospace Stock Forecast DetailsAnalysts' responses highlight the strength of Firefly’s quarter, with several firms raising price targets after the report. Commentary focused on the earnings beat, backlog, and guidance, alongside the validating AST SpaceMobile deal. The target range is wide, but Firefly has a Moderate Buy consensus rating and an average price target of $35.75, suggesting about 50% upside from recent trading levels. The expectation now is for Firefly to continue executing its strategy and sustain its bullish revision cycle.
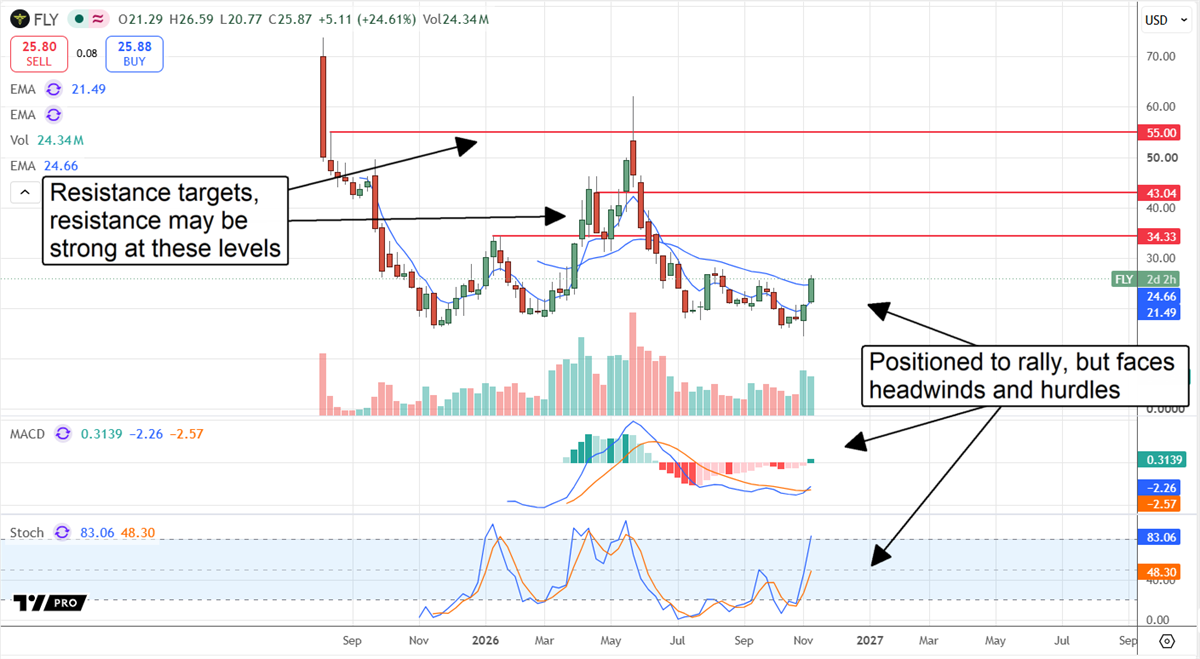
Price action was bullish following the release, rising by more than 10% and suggesting a potential bottom in the market. Whether it is the absolute bottom remains to be seen. Near-term signals suggest upside potential, but technical hurdles remain. Prior highs near $35, coincident with a congestion band in the $35 to $45 region, may provide sufficient resistance to cap gains.
There Are Plenty of Risks and Headwinds for Firefly Shareholders
Risks include, but are not limited to, shareholder dilution. Q3 highlights reveal a well-capitalized company with limited debt and steady equity, but cash is down year-to-date despite a dilutive capital raise, and the cash bonfire is still burning. Cash could continue to dwindle, increasing dilution risk until the company reaches profitability. Based on Q3 figures, additional financing remains a risk before that transition. News of capital-raising activity could create selling pressure.
Other risks center on concentration and execution. Firefly Aerospace’s outlook is rapidly improving, but its existing revenue and backlog are tied to a few government entities, while the new AST SpaceMobile agreement introduces additional execution risks. Government contracts are exposed to budget shifts and administration changes, while ASTS is an equally speculative play on space-based 5G services with no guarantee of success. As it stands, the Alpha launch system has experienced several setbacks and delays, with the next launch not slated until early 2027. Governance is also a risk, with a large shareholder retaining significant influence over the company.
Boiled down, bulls may be getting the timeline to scale wrong. Project delays, costs, and widening adjusted losses plague the outlook and make the existing timeline uncertain at best. Bears may be wrong to treat Firefly like a pure launch company, because its primary revenue source and growth drivers are spacecraft solutions, including vehicles and defense software. While launch matters, the five concurrent lunar missions and the vehicle requirements they bring are the bigger story. In addition, acquiring SciTec embeds Firefly in the defense software industry.
Before you consider Firefly Aerospace, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Firefly Aerospace wasn't on the list.
While Firefly Aerospace currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
MarketBeat just released its list of the 7 hottest IPOs expected to hit Wall Street in 2026. See which companies are preparing to go public and why investors are watching closely.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
