SoundHound AI Today
$4.11 -0.15 (-3.52%) As of 11/6/2026 04:00 PM Eastern
- 52-Week Range
- $3.88
▼
$14.98 - Price Target
- $9.50
The ugly truth behind SoundHound’s NASDAQ: SOUN Q3 results is that costs are rising, compressing gross margins and widening adjusted losses. However, it's wrong to view these statistics as signs of impending doom, because the pain is self-inflicted, part of the company’s strategy, and has it at an important inflection point. That is, from cash burn to positive adjusted EBITDA, which management forecasts for the back half of next year, only three to four quarters away. This transition could provide a powerful catalyst for a market long plagued by doubts.
SoundHound’s strategy is to build an AI-powered voice platform for enterprise automation. It includes numerous acquisitions, such as LivePerson, which expanded the addressable market, product portfolio, cost savings, and cross-selling opportunities. Within this, the company is shedding excess baggage, including lower-margin, dilutive legacy contracts, which execs are allowing to lapse. Today, the impact is weaker growth and wider losses than would otherwise be reported, alongside a rapidly shifting operational environment supporting the long-anticipated profit transition.
SoundHound Guides for Strength in Q4 and 2027
SoundHound posted a solid quarter despite wider losses. The company brought in $62.4 million, up more than 48% and outpacing MarketBeat’s consensus. Growth came from strength across verticals, including new enterprise wins, upsells, and renewals. More importantly, the company received positive feedback from LivePerson’s largest clients, representing approximately $100 million in annual recurring revenue. Execs reported encouraging feedback about continued business and interest in enterprise-level agentic voice services.
Margin is the sore spot, with non-GAAP gross margin falling nine percentage points year over year to 50.3%, while adjusted losses widened. Despite the top-line strength and an earnings-per-share beat, widening adjusted losses and margin pressure remain concerns. Guidance is the offset: management forecasts $255 million in 2026 revenue at the midpoint, better than expected, and sustained, nearly 50% growth in 2027, with the longer-term forecast likely to be cautious.
Factors that could support growth in Q4 and 2027 include cross-selling to LivePerson’s clients, new enterprise wins, the transition to a software-as-a-service (SaaS) model, and scaling operations. LivePerson is an opportunity not to be underestimated, as its clients include 25 of the Fortune 100, a high double-digit number of Fortune 500 companies, and 35% of Forbes’ Most Valuable Brands.
The operational shift includes shedding legacy business in favor of new, hosted services built on the OASYS platform, effectively transitioning SoundHound to a higher-margin SaaS business. Scale is seen in recent deals such as the one to bring SoundHound-powered commerce to LG Smart TVs, potentially opening a new revenue stream.
Analysts' Mixed Responses Highlight SoundHound’s Long-Term Opportunity
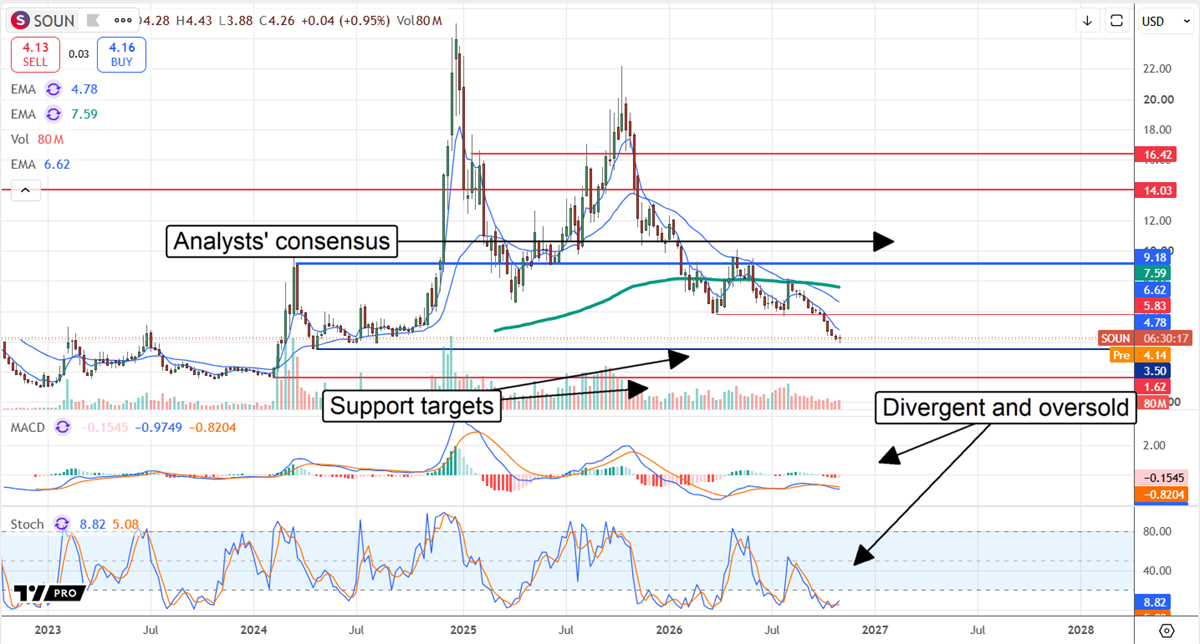
The few analysts’ responses emerging immediately after SoundHound's report are mixed. Analysts are highlighting both the near-term margin headwinds and the long-term opportunity, cutting price targets but reaffirming their ratings. The consensus rating in early November is Hold, although analyst sentiment leans positive. Institutional activity has been modest, with slightly more buying than selling. Price targets are favorable, suggesting a market disconnect, with SOUN stock trading well below the consensus target and analysts forecasting more than 100% upside.
Short selling is among the biggest risks for investors. SoundHound’s cash-burning status and uncertainty attracted flocks of short-sellers, driving short interest to over 40%, where it has hovered for months. With this in play, SOUN shares could struggle to advance without a strong catalyst and may face hurdles even if one emerges. Short-covering triggers center on the LivePerson acquisition, enterprise wins, and the transition to profitability, which are unlikely to emerge before the Q4 earnings report. The silver lining is that, with days-to-cover above 10 and short interest so high, the upside potential for a short squeeze is massive.
There’s no way to know for sure where SoundHound’s stock price bottom is, when it will be set, or how high it will get on the rebound, but investors can watch signals to help gauge direction and timing. Among them are the stochastic and MACD oscillators, which help measure momentum, market strength, and direction.
Price action is trending lower in Q4, with stochastic and MACD reflecting divergence and an increasingly weak bearish force. The setup suggests an imminent rebound, needing only a catalyst to trigger it, potentially delivered in early 2027 with the Q4 release and 2027 guidance update. Until then, support is possible but not guaranteed near the April 2024 lows and the February 2024 lows if the first target is broken. SoundHound's risks include competition, but it has a moat with its differentiated approach to voice, which enables higher-quality responses and interactions.
Before you consider SoundHound AI, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and SoundHound AI wasn't on the list.
While SoundHound AI currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Robotics and automation are rapidly becoming essential infrastructure across healthcare, manufacturing, logistics, and many other industries. "Physical AI" is coming. Learn which seven companies are most positioned to benefit as intelligent robots enter the workforce.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
