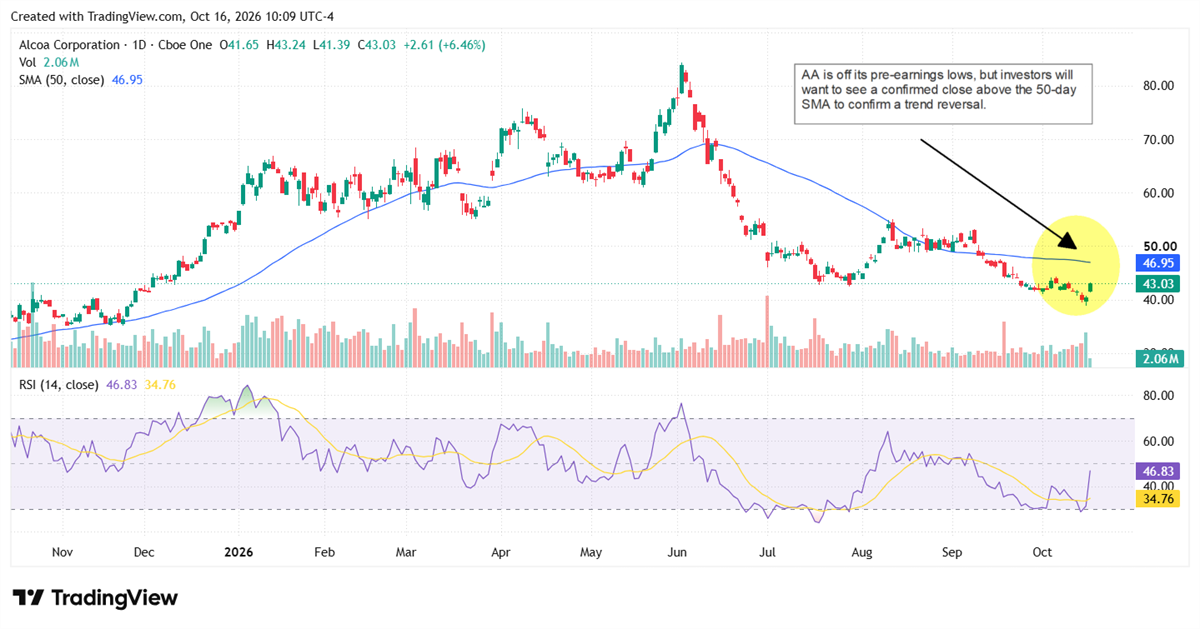
Alcoa Corp. NYSE: AA stock has been cut nearly in half since its spring peak. Shares traded near $77 in May and were trading near $40 prior to the company's Q3 2026 earnings report, which the company delivered after the market closed on Oct. 15.
Alcoa Today
$41.63 +0.18 (+0.44%) As of 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $35.12
▼
$84.38 - Dividend Yield
- 0.96%
- P/E Ratio
- 7.19
- Price Target
- $62.17
That kind of drawdown usually signals a broken business or a collapsing commodity. Alcoa has neither. Aluminum prices have cooled from their spring highs, but they have not followed the stock down. Alcoa’s average realized aluminum price fell about 5% from the second quarter to the third. AA shares fell roughly ten times that.
That gap set up the real question that Alcoa needed to answer with its report. Had the market confused a temporary operational problem with a peak in the aluminum cycle?
The operational problem is real. Instability at the Pinjarra refinery in Australia pushed the Alumina segment to a $96 million EBITDA loss in Q2. Add July’s earnings miss, and the “peak earnings” story writes itself.
The Q3 report provided a bullish rebuttal. Pinjarra is stable again. Aluminum margins remain near record levels. And Alcoa beat earnings expectations while producing its strongest free cash flow of the year.
Pinjarra Refinery Recovery Drives an Alumina Rebound
Alumina production jumped 11% sequentially to 2.5 million metric tons. Management credited improved stability at Pinjarra. Segment EBITDA improved to a loss of just $1 million. That's a $95 million swing in one quarter.
Costs fell. Adjusted operating cost per ton of alumina dropped to $354 from $368. This came while realized alumina prices rose to $353 per ton from $334.
This is evidence of a temporary problem that is in the process of resolving itself. Management expects Alumina performance to hold steady in Q4 rather than slip back.
Aluminum Margins Remain Strong Despite Lower Prices
Aluminum segment EBITDA fell to $862 million from Q2’s record $1.07 billion. Bears will point to that decline. But context matters.
Two factors drove most of the drop. Realized aluminum prices slipped to $4,527 per ton from $4,752. Shipments fell 5% after Q2 volumes were inflated by inventory moves from Q1. Additionally, higher carbon costs added pressure.
Viewed from that lens, this doesn't look like a cycle rolling over. Q3 aluminum EBITDA was still nearly triple the $307 million from a year ago. The segment kept a margin above 28% of third-party sales.
Production kept climbing, too. Aluminum output rose for the sixth straight quarter to 649,000 metric tons. The Alumar smelter restart in Brazil is complete. Five smelters and one refinery set year-to-date production records.
Alcoa Q3 2026 Earnings Beat Estimates
Adjusted earnings per share (EPS) came in at $1.82, ahead of the $1.51 consensus. GAAP EPS rose to $1.81 from $1.53 in Q2. A year ago, adjusted EPS was a 2-cent loss.
Cash flow tells the same story. Operating cash flow was $643 million. Free cash flow reached $472 million, up from $422 million in Q2. A year ago, free cash flow was negative.
The balance sheet is ready for the AliGroup acquisition. Alcoa holds $4.4 billion in cash after a $2.6 billion bond sale. Net debt is just $414 million. South32 shareholders approved the deal on report day. Closing is expected in the first half of 2027.
Why Alcoa Stock Remains Near Its Lows Despite Strong Results
So why is the stock still near its lows? Partly because the market prices aluminum stocks on the next move in metal, not the last quarter.
Q4 guidance does carry modest headwinds. Management sees about $30 million in higher raw material and maintenance costs in Aluminum. Higher alumina input costs should add another $30 million. Interest expense is also rising after the bond deal.
Those are real, but small against an $862 million quarterly segment result. Management also expects higher production and shipments in both segments in Q4.
The chart reflects exhausted selling more than new information. Shares sit below a declining 50-day moving average near $47. AA bounced nearly 5% the morning after earnings. This pushed the 14-day RSI out of oversold territory, where it was before the report.
Key Risks and Catalysts for AA Shares
The bull case doesn’t require aluminum to rally. It requires aluminum to stay elevated while Alcoa’s operations keep improving. Q3 delivered both.
The risk is a further slide in metal prices. LME moves flow directly through the Aluminum segment. A sharp drop would validate the market’s peak-cycle read.
But this report points the other way. The operational issue behind the sell-off is resolved. Margins remain near historic highs. And the stock is priced as if neither were true.
That disconnect is the opportunity. The market sold Alcoa on a refinery problem and cycle fears. The quarter fixed the refinery. The cycle hasn’t turned.
Before you consider Alcoa, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Alcoa wasn't on the list.
While Alcoa currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
The AI wave will soon hit public markets with Anthropic and OpenAI set to go public later this year. However, you don't have to wait to invest. This report shows seven AI stocks that you can buy today while the big model providers get ready to go public.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.

