CoreWeave’s NASDAQ: CRWV Q3 results upended the AI narrative, showing compute demand outpaces supply in a supply-constrained environment. The results also challenged fears of an AI spending slowdown and set the stage for a prolonged AI infrastructure supercycle. Debt concerns also eased, with execs highlighting backlog growth, pricing power, and the same self-funded expansion signaled by other critical players.
CoreWeave Today
$57.93 -2.84 (-4.68%) As of 11:08 AM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $40.58
▼
$138.25 - Price Target
- $118.28
Committed customer contracts support CoreWeave's backlog, including upfront payments and hardware commitments that reduce CoreWeave’s capital requirements. Management confirmed it would not tap high-yield, unsecured credit markets at current rates, instead funding its buildout with asset-backed loans, operating cash flow, and approximately $9 billion in prepayments and deposits expected over the next three months. Looking ahead, execs expect to raise less than $5 billion in additional parent-level capital through 2027, while Oracle’s NYSE: ORCL management has indicated that AI-focused spending will soon peak.
And CoreWeave’s moat? That’s tied to first-mover advantage: the hyperscalers and neoclouds with projects in progress have advantages over those that don’t, and they could strengthen as regulations raise entry barriers. Regulation may make it harder for new businesses to enter the neocloud market, benefiting established companies like CRWV and its peers. In this scenario, capacity constraints could improve utilization and efficiency, factors that underpin revenue and margin strength for any business.
CoreWeave’s Beat-and-Raise Reignites AI Trade
CoreWeave’s Q3 results matter both company-specifically and sector-wide, validating signals in reports from Oracle to Oklo NYSE: OKLO pointing to acceleration over the next three to six quarters. Revenue grew by nearly 170%, to $3.66 billion, beating analysts' revenue estimates by more than 3%, with backlog growth, guidance, and capital expenditure (CapEx) plans pointing to continued growth in the coming quarters. Backlog grew to over $130 billion, sufficient for nine years’ revenue at the annualized Q3 pace, underpinning a guidance increase. Revenue guidance ranges from $13 billion to $13.3 billion for the full year versus the $12.88 billion consensus, and could prove conservative given the trends.
CapEx, a primary driver of market doubts, is accelerating and increasing, with management raising the low end of its full-year guidance from $35 billion to $37 billion while maintaining the upper end at $39 billion. Demand is driving the acceleration, with execs aiming to capture backlog faster than expected. As it is, execs expect to end the year with an approximate $20.5 billion exit run rate, a 3.25x year-over-year increase, implying more than $5 billion in quarterly revenue. Equally important, perhaps more so, execs target profitability by H1 2028, at least a full half sooner than analyst consensus forecasted.
Analysts Cheer CoreWeave Results: Lower Targets on Debt Risk
Analysts responded with an overwhelming vote of confidence in CoreWeave’s business traction but focused on debt and near-term risks rather than accelerating momentum. The net result was a flurry of reaffirmed ratings, reinforcing the bullish Moderate Buy consensus, and lower price targets. Price target reductions are a concern and a headwind for market action, but they don’t undermine the outlook. MarketBeat's consensus price target is approximately $119, well above CRWV's recent trading range.
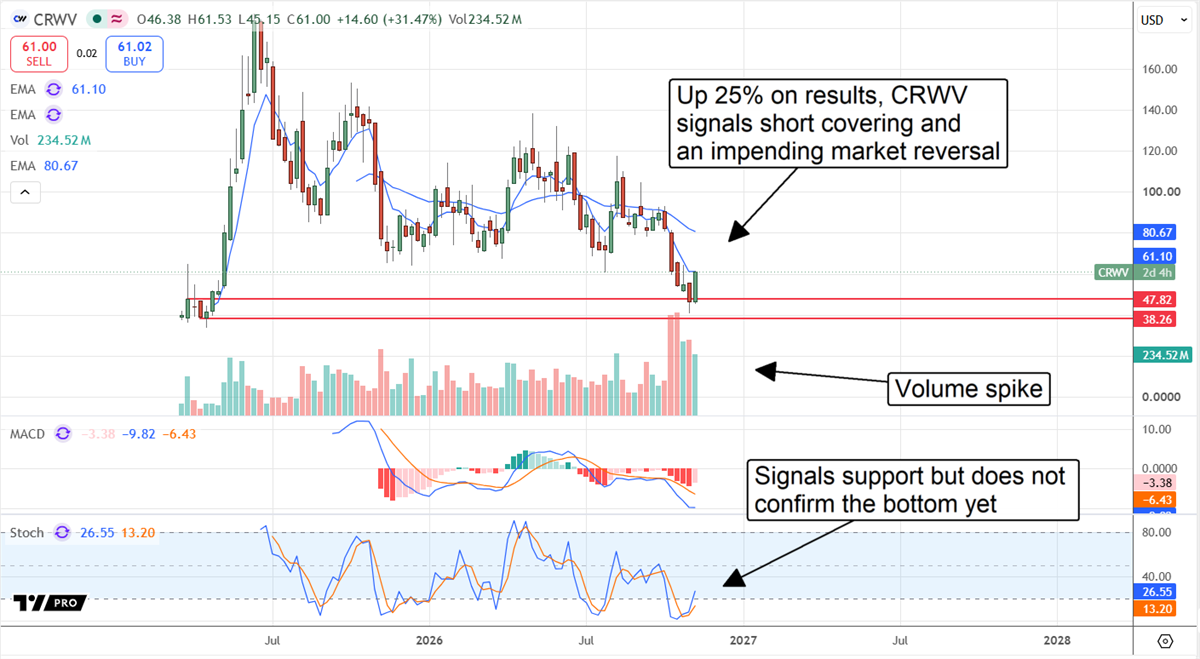
Short interest also warrants attention. Short interest topped 21% of the public float at the end of October, suggesting the post-release stock surge may be due at least in part to short covering. The signal is that CRWV’s market dynamics are changing enough for short sellers to potentially begin exiting, which may drive a more pronounced rebound and market reversal in the coming quarters.
Valuation and Technical Outlook Improves, But CRWV Still Has Hurdles
CoreWeave Stock Forecast Today
12-Month Stock Price Forecast:$118.14108.90% UpsideModerate BuyBased on 39 Analyst Ratings | Current Price | $56.55 |
|---|
| High Forecast | $200.00 |
|---|
| Average Forecast | $118.14 |
|---|
| Low Forecast | $39.00 |
|---|
CoreWeave Stock Forecast DetailsAssuming CRWV continues to execute its strategy, grow revenue, convert backlog, and improve profitability, the stock price rebound could easily last several quarters, potentially exceed the consensus price target, and even set a new high. Long-term forecasts place this stock at approximately 2x its 2036 earnings per share (EPS) as of early November, a valuation that prices in utter failure and suggests a massive market disconnect.
Price action suggests CRWV stock may have found a bottom, with a conspicuous volume spike accompanying the move. Other signs of rebound strength include the stochastic oscillator and moving average convergence divergence (MACD), which align with support at current levels but have not yet produced a Buy signal. A Buy signal could emerge when stochastic reconfirms with another bullish crossover and MACD shifts from bearish to bullish. The risk for traders is in volatility; short interest and analysts' revisions suggest CRWV is not out of the weeds, and whipsaw action remains possible over the next few weeks to months.
The bears may be wrong, however, to assume CoreWeave’s surging bond yields signal financial distress, as the Q3 results show. While yields have surged, this is secondary-market activity and does not directly affect CRWV’s operations. It still pays the original coupon, well below the reported mid-teens rate. In reality, CoreWeave’s cost of capital fell versus last year, coming in at a weighted average near 7.9%.
Before you consider CoreWeave, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and CoreWeave wasn't on the list.
While CoreWeave currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
AI spending is reshaping the market, and the opportunity extends far beyond the biggest chipmakers. Discover 10 stocks set to benefit from powerful trends in AI infrastructure, cloud computing, energy, capital returns, and consumer growth this fall.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
