J.B. Hunt NASDAQ: JBHT continues to face headwinds, but don’t get this turnaround story wrong. The company has not experienced a structural decline in its business, but rather a dynamic market shift from which it will not only recover but also benefit. The shift centers on regulatory oversight, enforcement, and the resulting driver shortage and capacity constraints that underpin the business today.
J.B. Hunt Transport Services Today
JBHT
J.B. Hunt Transport Services
$228.78 -6.53 (-2.78%) As of 10/16/2026 04:00 PM Eastern
- 52-Week Range
- $157.82
▼
$299.76 - Dividend Yield
- 0.79%
- P/E Ratio
- 32.13
- Price Target
- $274.12
While driver costs are rising, these costs can be recovered because they’re part of the operating environment. There’s no other choice; the entire industry faces the same headwinds.
And within the industry, J.B. Hunt is uniquely poised to benefit. It has the size, scale, and intermodal expertise to deliver quality services businesses and enterprises demand.
For J.B. Hunt today, this means higher volume, with pricing and industry undercapacity driving business. Next year, this means a dual lever for earnings growth, with top-line strength amplified by margin recovery.
Margin recovery will take time, but execs are actively working on it, planning a more aggressive repricing cadence in the coming year.
J.B. Hunt’s Strong Q3 Sets the Stage for Margin Recovery
J.B. Hunt posted a solid Q3, with revenue up 20% to $3.68 billion and outperforming MarketBeat’s consensus by 250 basis points. Volume and pricing drove strength, with most segments contributing. Intermodal grew by 20% on an 8% volume gain; Dedicated Contract Services grew by 11% on trucks and efficiency, led by Integrated Capacity Solutions (ICS). ICS grew by 57% on a 22% volume gain, amplified by a 29% improvement in revenue per load. Looking ahead, the volume and pricing metrics are expected to remain favorable, if not improve.
Margin is the sore spot, but it's no worse than the company forecast and the market priced in. Key details include a 2% increase in operating income, much slower than the 20% top-line gain, but still better than expected. Key details for investors include the massive increase in purchased capacity, a metric that can be controlled over time, and a nearly 30% increase in salaries, which points to a steadily improving driver base.
The company did not provide guidance but did offer an optimistic outlook for Q4 and 2027. While repricing has impacted only about 10% of contracts, another 30% is expected in each of the first three quarters of next year, setting the stage for accelerated revenue growth and margin recovery. Analysts' consensus forecasts a low-double-digit revenue compound quarterly growth rate over the next two years, with earnings growth accelerating to nearly 50% by Q3 2027 and then sustaining a high-double-digit pace for quarters afterward.
J.B. Hunt’s Dividends and Buybacks Support Long-Term Growth
J.B. Hunt’s appeal lies as much in its cash flow and capital-return capacity as in anything else, including dividends and share buybacks. The dividend is the lesser, yielding less than 0.8% annualized, as of mid-October, but it is a reliable payment with annual growth that helps keep buy-and-hold interest high. Buybacks are more substantial, reducing the count by more than 2.25% over the trailing 12 months. The likely outcome is that J.B. Hunt will continue to pay dividends and buy back shares, helping boost earnings-per-share growth over time.
Analysts See Upside as Institutional Buying Supports J.B. Hunt Stock
Analysts responded to the report with cautious optimism. While some lowered their price targets, others reaffirmed theirs, and the overall outlook remains bullish. MarketBeat tracks 26 analysts with current ratings; the stock is pegged at Moderate Buy, sentiment has been firm and steady, and the consensus price target trend is favorable. While recent price target reductions capped upside potential, consensus is up about 70% over the last year, forecasting more than 20% upside from early Q3 lows.
An immediate rebound is not guaranteed, but lower prices are unlikely. Institutions own about 75% of this stock, and buying spiked in late Q3 alongside the stock price implosion. The group's activity indicate a price floor which is also reflected in the technical action.
J.B. Hunt Stock Eyes New Highs, But Cost Risks Remain
Chart price action reveals a market trading above its critical support, in the midst of an inflection and poised for a bullish upswing. In this setup, the stock price can revert to its existing highs near $300; the question is whether it can move on to set new highs.
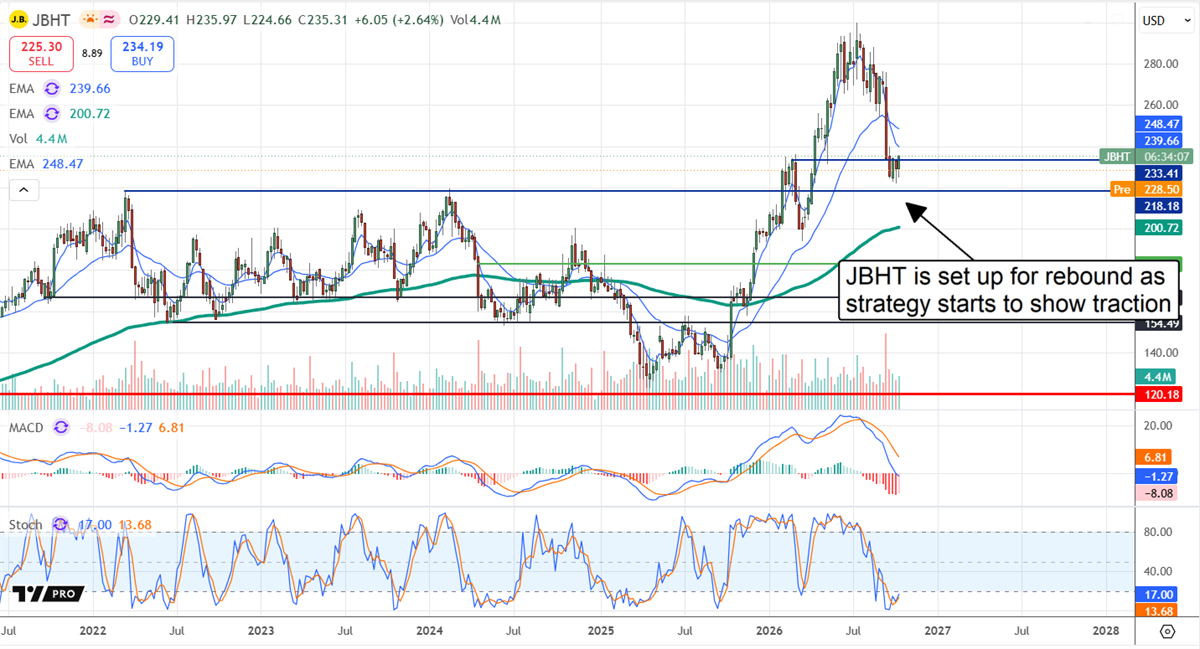
J.B. Hunt's biggest risk is persistently high costs and the impacts of price pass-throughs. On one hand, the company is on track to recoup margin, but on the other, higher costs for end users are inflationary and may lead to slower activity than expected.
Before you consider J.B. Hunt Transport Services, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and J.B. Hunt Transport Services wasn't on the list.
While J.B. Hunt Transport Services currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Robotics and automation are rapidly becoming essential infrastructure across healthcare, manufacturing, logistics, and many other industries. "Physical AI" is coming. Learn which seven companies are most positioned to benefit as intelligent robots enter the workforce.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
