Texas Instruments' NASDAQ: TXN Q3 results were hailed by analysts as a definitive beat, reinforced by increased guidance that strengthens the case for future stock price gains.
Texas Instruments Today
TXN
Texas Instruments
$280.72 -3.93 (-1.38%) As of 03:35 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $152.73
▼
$334.03 - Dividend Yield
- 2.02%
- P/E Ratio
- 43.02
- Price Target
- $310.74
The immediate analyst response has been a wave of reaffirmed and raised price targets, extending the trend and pointing to a $400 price handle at the high end. While the consensus price target remains tepid, forecasting only modest upside relative to pre-release price levels, analysts' trends are robust and suggest another 50% upside is coming.
Analysts' trends reflect strong conviction, with 30 covering the stock and 15 rating it a Buy. The Moderate Buy rating has been relatively stable over the past year, while the consensus price target has increased by 50%, underpinning stock price action. The caveat is that the 50% upside will take time to achieve; quick gains are likely over, and caution is strengthening. Analysts point to the premium valuation and wide guidance range as the main hurdles the stock faces.
Valuation is a concern, with TXN trading at about 30x current-year earnings, well above the S&P 500 average and industry peers. However, the valuation prices in a solid growth trajectory, which the Q3 results affirmed, and forward estimates see the price-to-earnings (P/E) multiple lowering significantly within only a few years. The 2030 forecasts put the stock's P/E in the mid-teens, are likely cautious, and suggest at least 25% upside to match the S&P 500 average. Assuming the stock retains its premium and grows into its forecast, it could rise by another 100% over the next few years.
Texas Instruments: The King of Nuts-and-Bolts Semiconductors Outperforms in Q3
Texas Instruments posted a robust quarter, with revenue up nearly 28% year over year and 11% sequentially to over $6 billion. Revenue beat MarketBeat’s consensus estimate by 220 basis points, and management highlighted strength across key end markets, including industrial, data center, and automotive. Segmentally, Analog led with a 32% increase, followed by a 21% increase in Embedded Processing, offset by a 6% decline in Other.
Margin news was impressive. The company widened gross margin and controlled SG&A, capital expenditure, and research & development, driving accelerated earnings growth across the stack. Gross profit rose 42.7%, operating profit 73%, net income 78%, trailing 12-month (TTM) cash flow 43%, and TTM free cash flow 249%. The key detail is GAAP earnings, which grew by 77% despite a slight increase in share count.
Guidance was both a catalyst and a headwind, oddly enough, as the company firmed up its Q4 outlook and posted a revenue guidance range well above consensus. The problem, albeit a small one, is that the wide ranges leave ample room for uncertainty. However, investors should not get this wrong. Uncertainty matters when the company faces the possibility of contraction and guidance is iffy. Here, even the low end of the range beats consensus, making the uncertainty less concerning.
Capital Return Strength Underpins TXN’s Price Outlook
Texas Instruments' cash flow supports a healthy capital return, which in turn supports the stock's price outlook. While buyback activity failed to reduce the share count in Q3, the company has a history of opportunistic repurchasing that has significantly reduced the count over time. Balance sheet details suggest further buybacks are possible, but likely to occur on pullbacks, given the elevated stock prices.
The dividend is reliable, yielding about 2.2% in late October and growing at a high-single-digit compound annual growth rate.
Balance sheet highlights reflect the strength of Texas Instruments’ position, with cash and assets rising, debt and liabilities falling, and equity improving. Equity grew 15% year over year, supported by cash, investments, receivables, and saleable materials, all of which exceeded total liabilities. Looking ahead, investors can expect TXN management to use its cash flow and balance sheet to fund growth opportunities, pay dividends, and buy back shares.
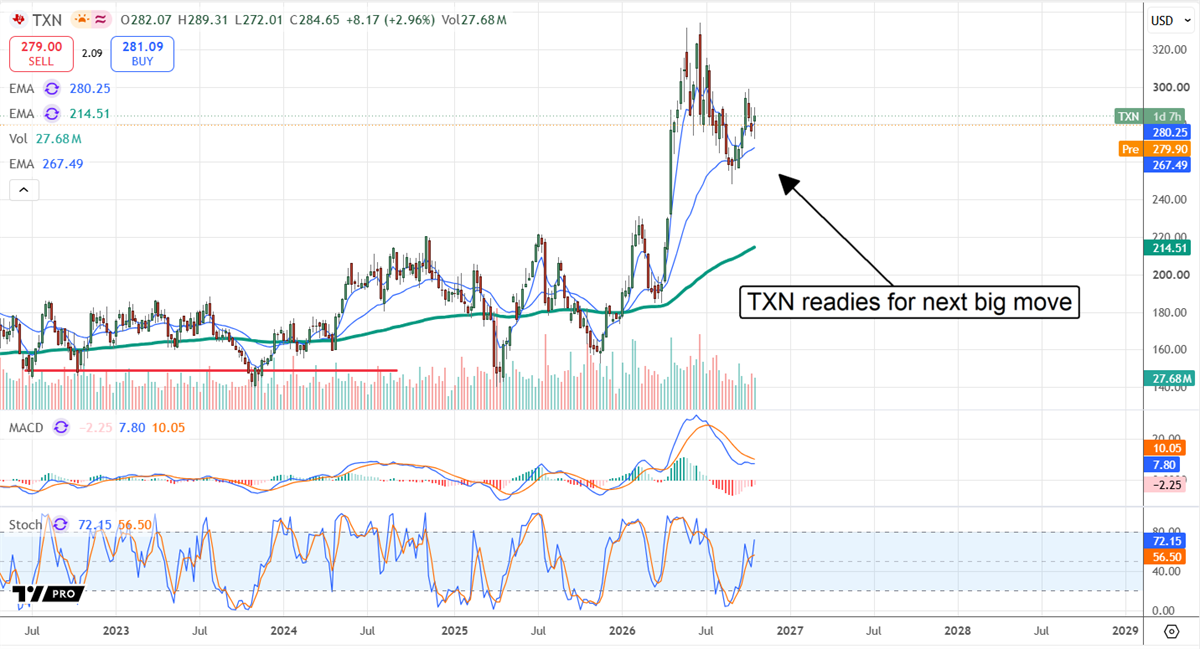
The post-release price action was mixed. Shares fell about 2% in after-hours trading, suggesting the market expected strength. That move, however, kept price action within an existing range where the stock has been winding up ahead of its next major move. The next move is likely to be upward, given the results and sentiment trends, but that may take some time to unfold. Critical support levels are near $270 and $260; critical resistance targets are near $300 and $320.
Institutions are a risk-reducing factor as of mid-Q4. The group owns about 85% of the shares and has been accumulating all year. They are also likely to buy on dips and may accelerate buying activity in the upcoming quarters.
Catalysts include expectations that business investment will slow, free cash flow will improve, and buybacks will resume at a more substantial pace. The company has about $18 billion left under its authorization, about 6.9% of its late-October market cap. Until then, investment is focused on 300-mm wafer capacity, which is central to the margin-quality outlook.
Before you consider Texas Instruments, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Texas Instruments wasn't on the list.
While Texas Instruments currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
MarketBeat just released its list of the 7 hottest IPOs expected to hit Wall Street in 2026. See which companies are preparing to go public and why investors are watching closely.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.

