With interest rates rising again, it's time to talk housing, which is once again showing that the K-shaped economy is alive and well. The Federal Reserve raised its benchmark rate by 25 basis points on Sept. 16, and a hot inflation report on Oct. 15 renewed concerns about additional hikes later this year.
That is another challenge for a housing market already struggling with affordability across much of the country. For investors, there are two approaches: a luxury homebuilder like Toll Bros. Inc. NYSE: TOL and an entry-level homebuilder like D.R. Horton Inc. NYSE: DHI. And as you might expect in a K-shaped economy, the luxury brand is outperforming its peers.
Toll Bros: Luxury Brand Shielded From High Mortgage Rates
Toll Brothers Today
TOL
Toll Brothers
$130.96 -2.74 (-2.05%) As of 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $123.14
▼
$168.36 - Dividend Yield
- 0.79%
- P/E Ratio
- 10.51
- Price Target
- $166.67
Toll Bros is the largest luxury homebuilder in the U.S., and its affluent buyers often have enough cash to make mortgages a non-issue. As of the most recent report, more than 60% of the company’s sales are luxury move-ups, and only 23% are first-time buyers. More importantly, 25% of sales were all-cash, and borrowers have a loan-to-value ratio of nearly 70%, giving the company a healthy buffer against skyrocketing mortgage rates.
The company reported its fiscal Q3 2026 numbers on Aug. 18 and beat projections for both earnings per share (EPS) and revenue. Luxury buyers again did most of the lifting, with net contracts up 5% year-over-year (YOY) and an average selling price of $996,400. Adjusted home sales gross margin also beat expectations at 25.6%, and only 5.4% of contracts were canceled in the period, down from 7.5% last year despite increasing mortgage rates. Management also reaffirmed full-year 2026 revenue guidance at $10.5 billion and raised average delivered price estimates to $1 million at the high end.
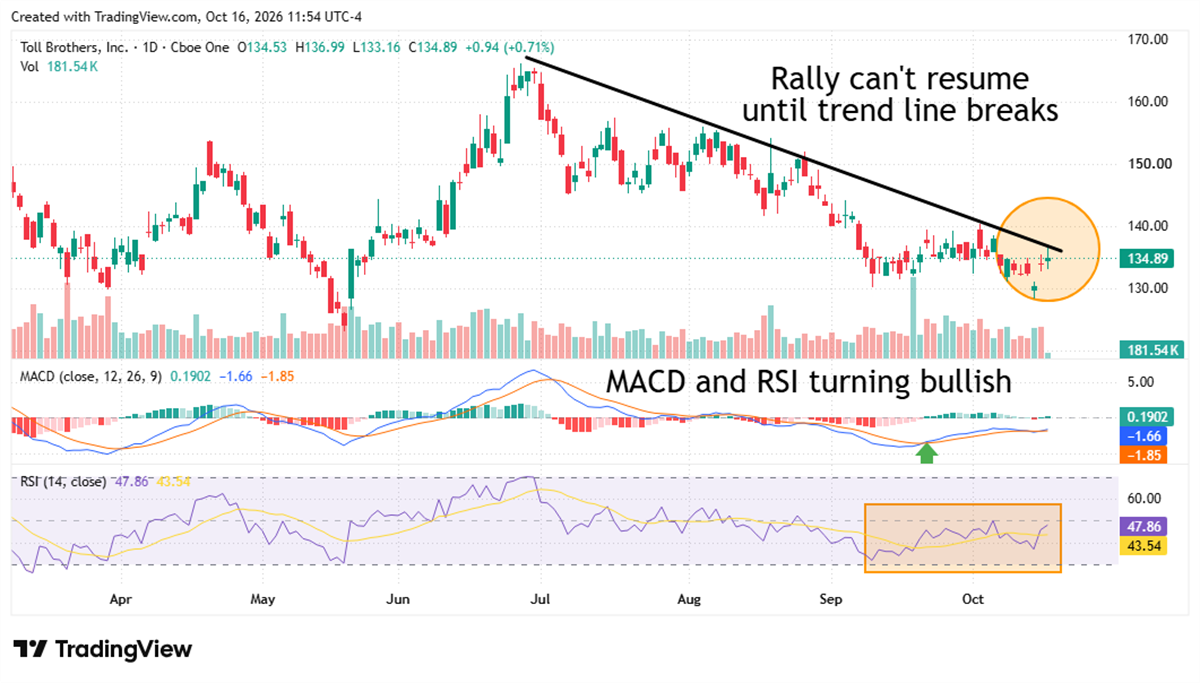
TOL shares received three price-target boosts from analysts shortly after the optimistic Q3 report, and 14 of the 19 firms covering the stock rate it a Buy. While the technical trend is still down, some evidence points to bullish activity. The Moving Average Convergence Divergence (MACD) indicator is bouncing off some extremely oversold levels, and the Relative Strength Index (RSI) is creeping toward 50 for the first time since August. The housing market is far from unlocked in the current macro environment, but Toll Bros is a safer place to hide than our next entry, which bears the full brunt of high mortgage rates.
D.R. Horton: Cancellations Build as First-Time Buyers Get Frozen Out
D.R. Horton Today
$135.31 -4.08 (-2.93%) As of 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $130.40
▼
$170.79 - Dividend Yield
- 1.33%
- P/E Ratio
- 12.87
- Price Target
- $156.36
D.R. Horton operates at the other end of the client spectrum. While it has its own luxury brand, Emerald Homes, its Express Homes offerings target entry-level buyers. In fiscal Q3, first-time buyers accounted for 65% of closings handled by the company's mortgage business. D.R. Horton is the largest U.S. homebuilder by volume, with an average net order price of approximately $365,000. This is also the most rate-sensitive cohort of homebuyers, who often struggle to afford a 20% down payment, let alone buy outright with cash. With 30-year fixed mortgage rates
once again over 7%, first-time buyers are getting frozen out, and D.R. Horton’s earnings data confirms this trend.
The company reported its fiscal Q3 2026 results back on July 21, and while the headline numbers beat expectations, the under-the-hood metrics and guidance left investors feeling queasy. EPS fell 5% YOY, and net home orders totaled 23,084, flat vs. the same period in 2025. Total number of homes closed grew only 4% YOY, and the gross margin on home sales was 23.3%, down from 24% in Q3 last year.
But the cancellation numbers stood out like a Cowboys fan in Philadelphia. Management reported a 20% cancellation rate in Q3, up from 17% in Q3 last year and 16% in Q2 2026. Chief Financial Officer (CFO) Bill Wheat said mortgage qualification is the primary reason for the cancellation buildup, and demand continued to soften as the quarter progressed. The company cut full-year 2026 revenue guidance to $32.5 billion to $33 billion and trimmed closings to 83,800 to 84,300. Guidance wasn’t the only thing getting trimmed; a wave of analyst price-target reductions followed the report, including a new Sell rating and a $128 target from Melius Research.
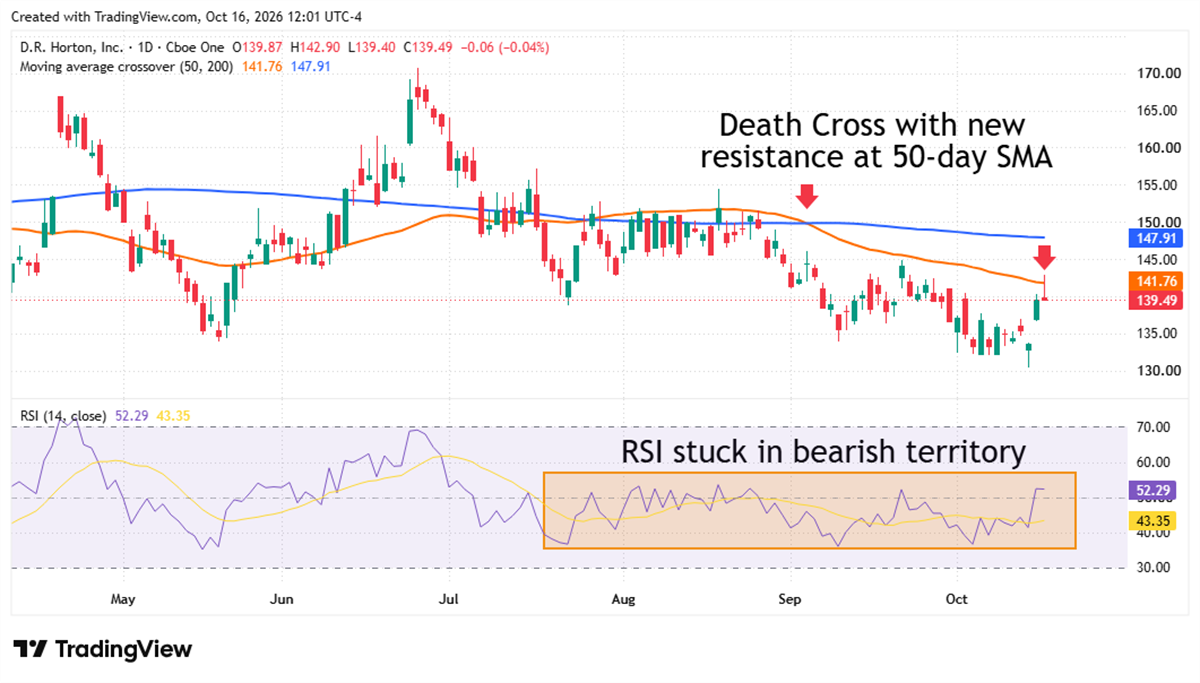
DHI shares are attempting to reclaim their 50-day moving average, a level that has acted as resistance since July. The 50-day average has now crossed below the 200-day average, forming a death cross that traders generally interpret as a bearish technical signal.
The RSI has recently moved just above 50, suggesting some improvement in near-term momentum. However, the stock remains below both major moving averages, leaving the broader technical picture weak. Until better fundamental data comes out of the company (or mortgage rates suddenly drop), this downtrend is likely to gain more steam as first-time homebuyers continue to struggle with affordability. The company reports its fiscal Q4 2026 results on Oct. 29, and the market will be watching closely for signs of further increases in cancellations or stabilization in buyer demand.
Before you consider Toll Brothers, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Toll Brothers wasn't on the list.
While Toll Brothers currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Discover the 10 Best High-Yield Dividend Stocks for 2026 and secure reliable income in uncertain markets. Download the report now to identify top dividend payers and avoid common yield traps.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.

