General Mills NYSE: GIS is working on a turnaround and nearing its inflection point. Its Q1 results for fiscal year 2027 (FY2027) were lackluster, but investors must remember this was against tough comp, with a significant divestiture in the numbers.
General Mills Today
GIS
General Mills
$34.85 -0.97 (-2.70%) As of 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $31.75
▼
$51.32 - Dividend Yield
- 7.00%
- Price Target
- $36.53
General Mills sold its yogurt business to focus on core growth opportunities and operational efficiency, positioning itself to sustain long-term growth. The key point is that the inflection point is here now and reflected in the stock’s price.
Internals reveal the impact of divestiture and turnaround efforts. While North America Retail contracted by 7% (400 basis points due to yogurt), it was the only segment to show weakness. North America Pet wasn't strong, but flat results are better than contraction and a more solid foundation to build upon.
More importantly, areas of strength, such as North America Foodservice, are expanding, and companywide organic sales were flat, with only the yogurt business needing to slip out of the math for growth to return. As it stands, the company is optimistic, forecasting potential for the inflection to positive organic growth by year’s end.
General Mills Dividend Safe in FY2027, Safer in FY2028
General Mills' dividend faces headwinds but appears reliable for FY2027. The payout ratio is getting high, but forecasted earnings cover it, as does the expected annual cash flow, which matters most. The biggest risk to the dividend is stalled growth, but it will likely return by the end of FY2028, mitigating the risk. In this scenario, the dividend growth outlook is more of a tailwind than not, providing a future catalyst to lift price action and accelerate price recovery. Until then, investors buying in late September can lock in an approximate 6.9% dividend yield at historically low prices, more than double the pace of core inflation.
Institutional holdings reflect confidence in General Mills' long-term value, and the group's activity aligns with a technical stock-price bottom. Institutions own more than 75% of the stock and have been accumulating in 2026, ramping activity into early Q3, as shown by MarketBeat data. Trading volume has steadily ramped up this year, reaching record levels as GIS shares hit historically low prices.
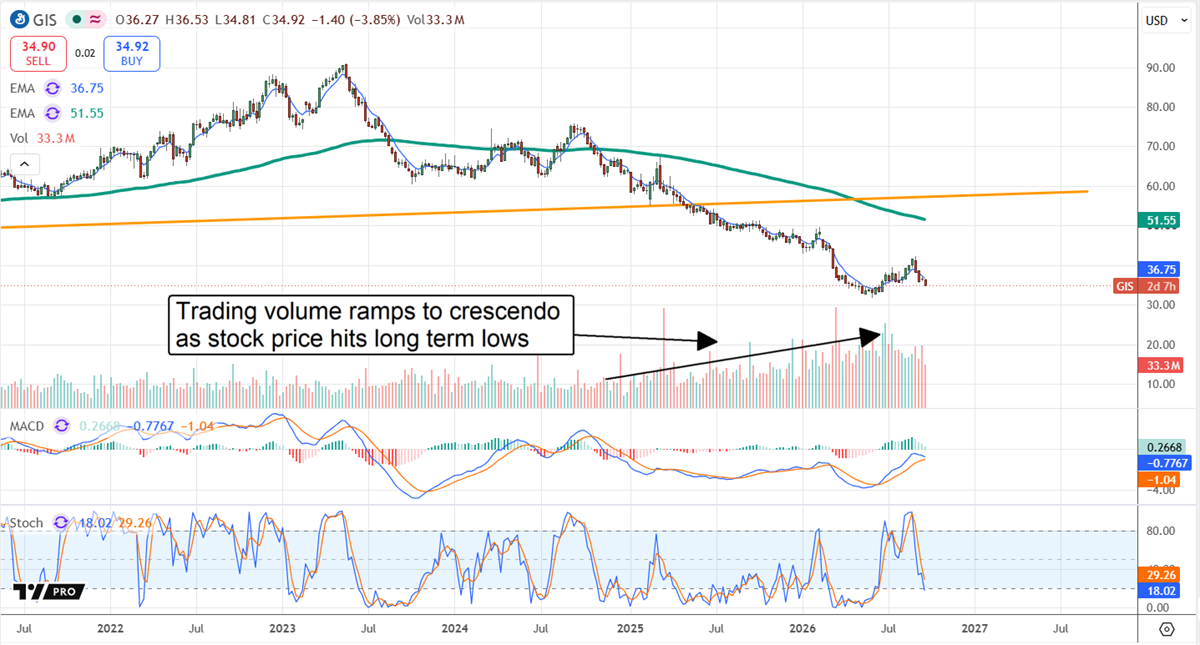
The Q3 institutional activity spike also suggests downside is limited in late Q3 and Q4. The likely outcome is that GIS shares trend sideways, if not higher, over the next two to three quarters while the market waits for systemwide growth to reenter the picture. Analysts are a more pressing concern, with consensus pegged at Reduce. The caveat is that bearish bias is minimal, only 30%, and the late-August/early-September aligns with a market bottom. It includes reaffirmed bullish ratings and higher price targets, confirming the low-$30s as a price floor.
General Mills Clears Hurdle, Reaffirms Guidance
General Mills had a tough quarter with sales in its core market contracting, even on an adjusted basis. However, net revenue of $4.4 billion beat consensus by a slim margin, as did margins. GAAP margins contracted by high double digits, but include the impact of yogurt; adjusted margins contracted by low single digits, leaving earnings down a low-teens amount versus last year.
Key details include $397 million in net income and the expectation that full-year results will outpace expectations. Guidance was reaffirmed, expecting flat to slightly negative organic sales and $3.10 in adjusted earnings per share, 3 cents more than analysts had hoped.
Balance sheet highlights raise some red flags, with cash, total assets, and equity down from last year, but the risks are minimal. The company is using its balance sheet to help sustain the dividend until the business turnaround gains visible traction, but it has the capacity to do so. Mitigating factors include reduced liabilities and flat debt, which leave the cash flow relatively unimpaired, though diminished.
And another catalyst is brewing: share buybacks. General Mills paused buybacks to conserve cash but will likely resume them as cash flow improves. No buybacks were made in Q1 FY2027, but the average count is down about 1%.
This year’s risks include the impact of GLP-1’s. GLP-1s are changing how Americans eat: they are snacking and eating less overall, and are more focused on protein. To respond, General Mills is shifting with the industry to offer more protein-rich, nutrient-dense options. The company is also leaning into technology to improve efficiencies, including return on invested dollars. Investors should watch dividend coverage and the risk of dividend cuts, which will increase as the year progresses; the key question is whether the company can make its expected pivot.
Before you consider General Mills, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and General Mills wasn't on the list.
While General Mills currently has a Reduce rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
MarketBeat just released its list of the 7 hottest IPOs expected to hit Wall Street in 2026. See which companies are preparing to go public and why investors are watching closely.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
