Biotech and specialty health care stocks can be attractive speculations because product innovation can drive explosive growth and attract intense takeover interest from large pharmaceutical companies. The challenge is determining which ones justify the risk, because early-stage drug developers are numerous, and many remain cash-burning for years.
Even the few winners still face challenges such as adoption, scaling, and disruption, alongside the dreaded patent cliff. For drug developers, patent cliffs effectively limit the period of market exclusivity, making investor timing an equally critical factor in the investment thesis.
Delcath Systems Disrupts Niche Market: Has the Cash Flow to Expand
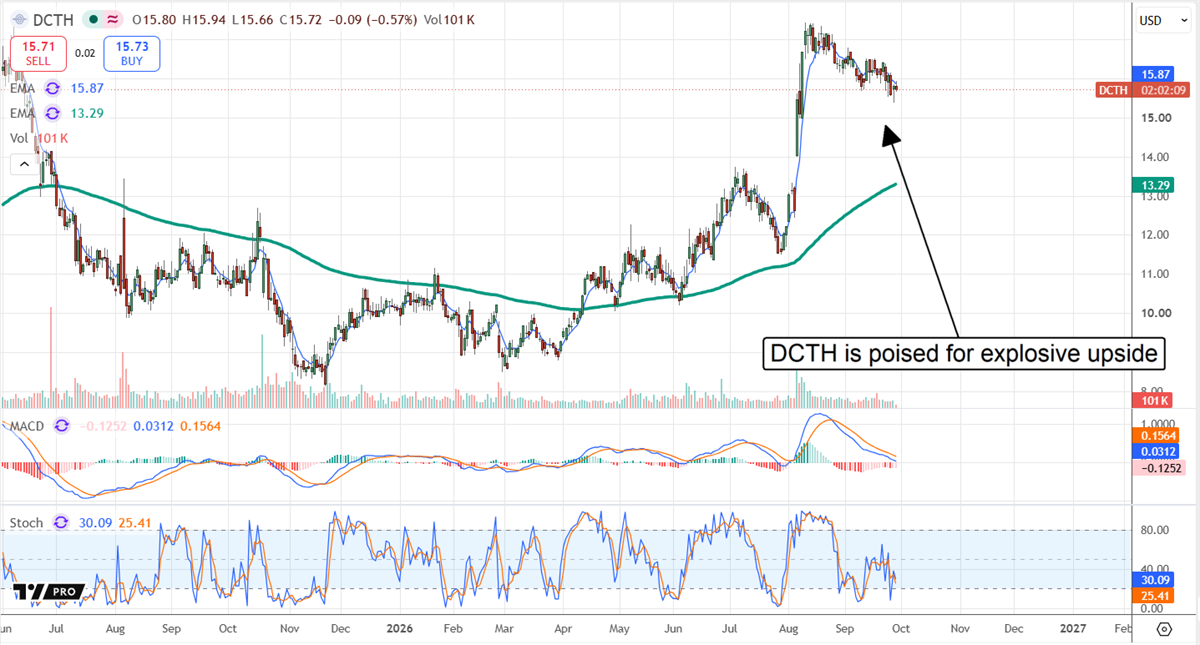
Delcath Systems NASDAQ: DCTH faces hurdles, including fewer initial certified centers than planned, but demand for its product offsets the difference. The product is the Hepzato Kit for targeted chemotherapy. It enables the isolation of liver systems and the direct administration of cancer-treating drugs. The benefits are obvious, providing targeted, high-dose treatment with fewer side effects, which is why it's in demand. The hurdle is the time it takes to onboard the system, which can run to over a year, but once certified, utilization drives revenue and profits.
Highlights in 2026 include moderating but sustainable, high-level growth in the 20% range and GAAP profitability. Profitability is crucial because it enables reinvestment and territory expansion alongside R&D for new indications. The company’s pipeline focuses on expanding the number of liver treatments it can administer, rather than adapting this liver-specific technology to other body systems. Looking ahead, analysts forecast a sustained high-teens to low-20% revenue growth rate over the next three to five years, with margins steadily improving as new centers are certified.
Analyst coverage is tepid, with only seven tracked, but they are bullish, rating the stock as a consensus Moderate Buy with approximately 46% upside as of late September. The latest updates came this summer, affirming the consensus, and institutions are actively buying, owning more than 60% of shares and underpinning Q3 price action.
Viking Therapeutics Could Topple the GLP-1 Duopoly
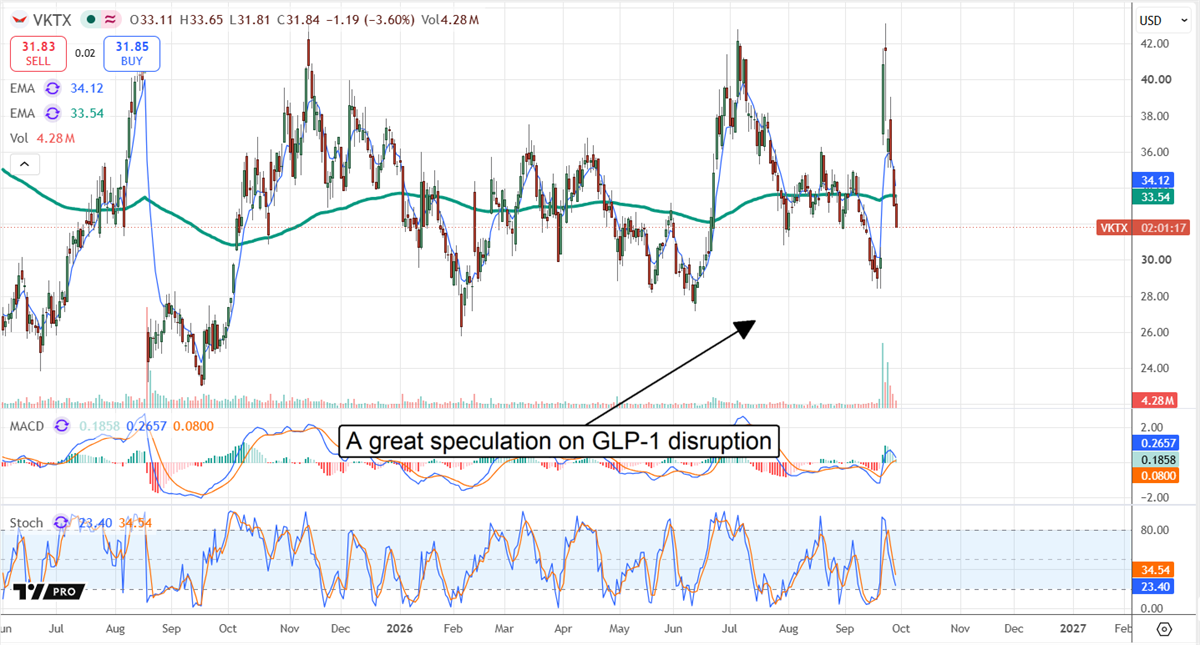
Viking Therapeutics NASDAQ: VKTX is a hot topic because its lead candidate is a dual GLP-1 receptor agonist, similar to Eli Lilly’s NYSE: LLY product. If approved, it could push Novo Nordisk NYSE: NVO out of second place, potentially knocking Eli Lilly into second if its oral treatment is also approved. The oral aspect is critical, allowing patients to move away from injections once the initial weight-loss period ends. Additionally, the company could present an attractive takeover target for larger pharmaceutical companies seeking exposure to the obesity market.
And the opportunity is real. The GLP-1 market is estimated to be worth at least $60 billion this year and is expected to triple in size over the next five to ten years. Disrupting even a small portion of this is a win, and the odds are high that Viking can steal a lion’s share of the market.
The risk for investors is that these treatments aren’t expected to receive approval for two to three more years, given the results of clinical trials. Between then and now, dilution is a factor, with the company using share count to sustain operations until it can commercialize its pipeline. Analysts, meanwhile, reflect modest conviction in the company’s potential, rating it as a Moderate Buy with more than 200% upside at the consensus price target. Institutions show greater confidence, owning about 76% of the share count.
AxoGen Transitions to Profits
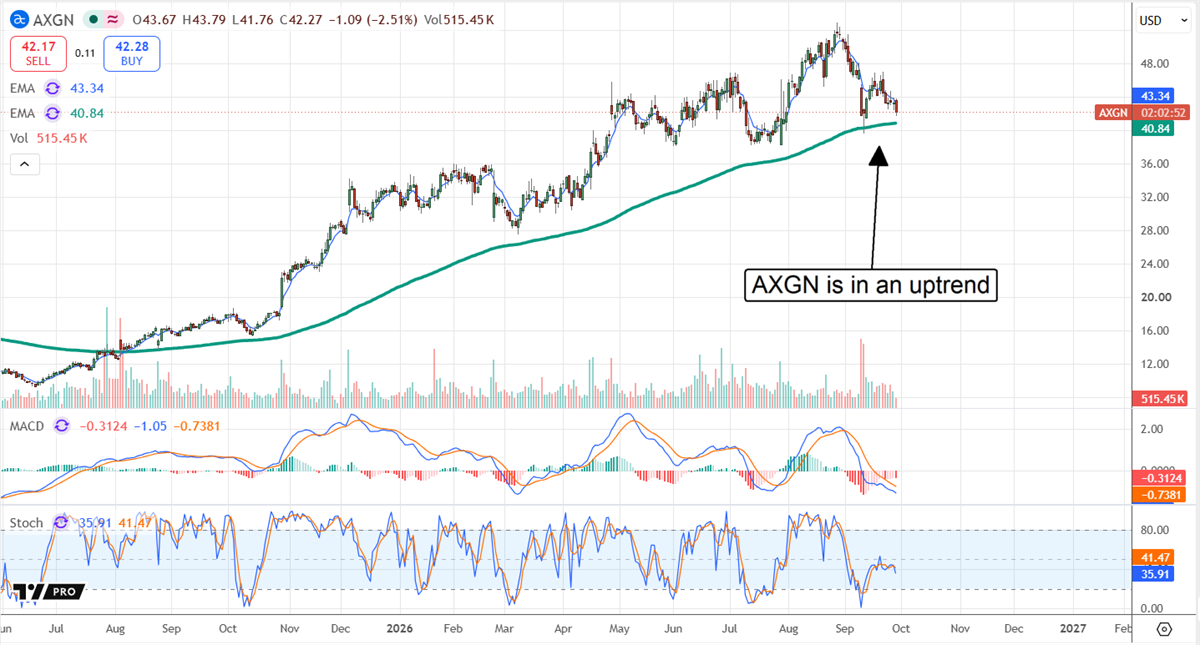
AxoGen, Inc. NASDAQ: AXGN stands out as a company with multiple revenue streams and is on the cusp of profitability. Leading therapies include Avance Graft, a processed human nerve graft that significantly reduces patient impact, and Axoguard Nerve Protector, which facilitates regeneration of protective tissues. Highlights from 2026 include accelerating growth and improving guidance, with a well-capitalized balance sheet and a company positioned to execute its strategy.
AxoGen’s opportunity is large. The company’s addressable market is about $5-$6 billion, roughly a quarter of the total, in a market growing at a low-double-digit CAGR. This sets the stage for sustainable, if not explosive, growth, with the estimated total revenue approximately 16x the 2027 consensus.
Analysts and institutional activity show strong, strengthening support, with rising coverage, a firm Moderate Buy rating, an uptrend in price targets, and aggressive accumulation. Institutions are the driving force, owning approximately 80% of the stock, buying at a $2-to-$1 pace over the trailing 12 months (TTM), and ramping activity into Q3.
Before you consider Delcath Systems, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Delcath Systems wasn't on the list.
While Delcath Systems currently has a Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Discover the 10 Best High-Yield Dividend Stocks for 2026 and secure reliable income in uncertain markets. Download the report now to identify top dividend payers and avoid common yield traps.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
