Six Flags Entertainment NYSE: FUN has launched Flex Pay by Upgrade. This is a buy-now-pay-later (BNPL) solution that offers consumers a pay-over-time option for eligible online purchases from $49, including season passes. Approved guests can activate their season pass right away and begin visiting parks while making fixed monthly payments.
Six Flags Entertainment Today
FUN
Six Flags Entertainment
$11.54 -0.78 (-6.29%) As of 03:10 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $11.61
▼
$27.37 - Price Target
- $21.50
The initiative comes after the company announced disappointing Q2 2026 earnings in August. Six Flags posted earnings per share (EPS) of 14 cents, while analysts had expected EPS of 29 cents. Revenue also came in light at $864.92 million versus the $929.31 million that was forecast.
In addition to coming in below expectations, both numbers were also lower year over year. Six Flags' net loss more than doubled to $202.6 million from $99.6 million a year earlier. That's troubling since the company's second and third quarters are typically its best based on seasonal factors. It also raises questions about what the health of the consumer could mean for its outlook.
FUN is down 45% in the past 12 months. Now an activist investor wants the board to consider selling the company. That leaves investors weighing a slow turnaround against a possible buyout premium.
Flex Pay Arrives at a Telling Time
The theme park operator is announcing Flex Pay during the company's softer time of year. Many of its theme parks are about to close until next spring. That means investors shouldn't read too much into the initial numbers for Flex Pay.
The timing stands out for another reason. Flex Pay went live on Sept. 7, the same day promotional pricing on 2027 season passes was set to expire. Six Flags appears to be using financing to keep pass sales moving after the discount window closed.
Investors should understand what Flex Pay is. It isn't an in-house payment plan. It's a loan from Upgrade's lending partners. Approval depends on a credit check, and the APR ranges from 0% to 36% based on the borrower.
That's a sharp contrast with the industry's biggest names. Universal and Disney NYSE: DIS both let annual passholders pay interest-free over time, though Disney restricts its plan to Florida residents. Six Flags is marketing Flex Pay as a value tool. But budget-conscious families may feel differently if they have to pay interest on their purchases.
Can Financing Fix a Demand Problem?
A larger concern is why the company is failing to attract consumers. Theme parks like Six Flags tend to be somewhat defensive. First, the theme parks are drivable for most of the guests. Second, they generally offer good value.
But higher gas prices are causing some consumers to put aside trips to theme parks, which come with their own on-site costs. That's where Flex Pay could make a difference. But is it too little too late for investors?
Six Flags May Go Private
JANA Partners is leading a group of activist investors that are pressing Six Flags to explore a sale, which could include a take-private deal. On Sept. 22, JANA pushed the board to hire an investment bank to run that process, citing frustration with second-quarter results.
JANA isn't new to this story. The fund built a roughly 9% stake alongside co-investors last fall, worth around $200 million at the time. That group included Kansas City Chiefs tight end Travis Kelce, who later signed on as a Six Flags brand ambassador. JANA's original demands covered marketing, park experience, technology, leadership changes, and a review of a possible sale.
The case for going private comes down to the balance sheet. Net debt stands at roughly $4.9 billion, while market capitalization is about $1.2 billion. With debt near four times equity value, a buyer's premium may look better than waiting on a multi-year turnaround.
There are reasons why investors may want to proceed with caution. The 2024 merger of Cedar Fair and Six Flags promised synergies that haven't materialized. History also offers a warning. Red Zone's 2005 takeover of Six Flags promised a brand revival and ended in bankruptcy in 2009.
Investors Aren't Thrilled
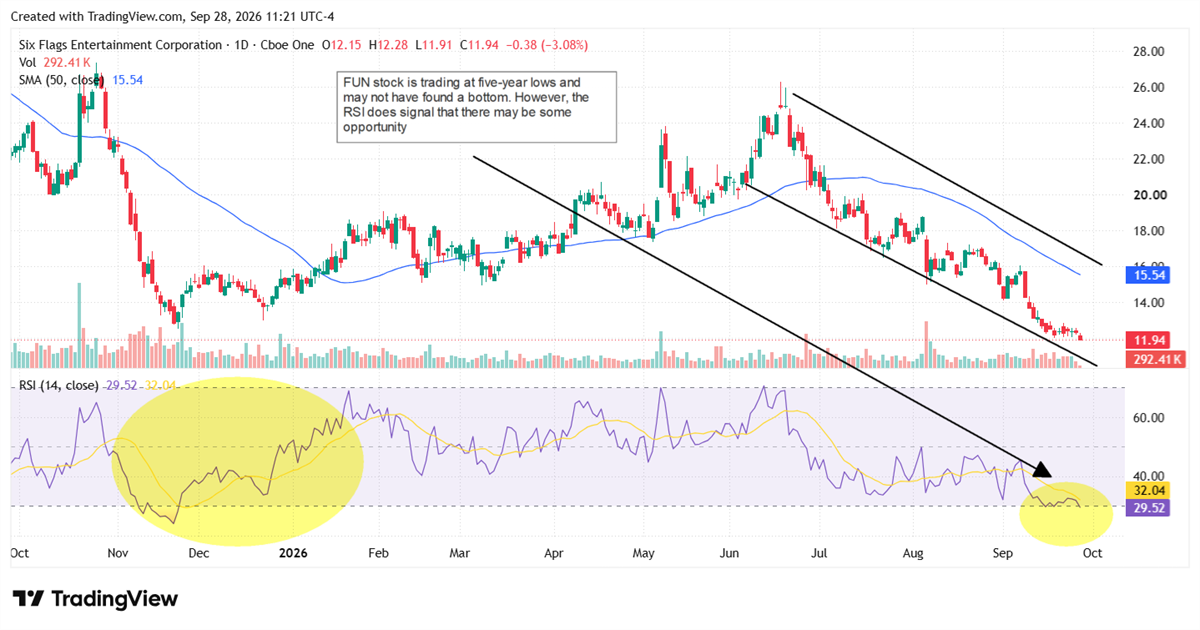
Flex Pay hasn't given Six Flags stock a lift. Shares fell about 26% in the month leading up to JANA's letter. The report then sparked a 5.4% after-hours pop. However, shares are still trading at five-year lows. A troubling sign for investors is that FUN keeps trending lower, even below a descending 50-day simple moving average (SMA).
Retail investors will have to overcome short interest that sits at around 21%. However, some factors are working in favor of buyers, such as the stock's relative strength index (RSI) tipping into oversold territory and a high percentage of institutional ownership.
Analyst price targets have been moving lower since the company's disappointing Q2 earnings report in August. However, the consensus price target for FUN is $21.50, which offers about 85% upside.
The fundamentals still point to a long, expensive turnaround. But the possibility of a sale gives FUN a potential floor it didn't have a month ago. If the board hires bankers, the debate shifts from attendance to takeover value.
Investors should watch two things. First, how FUN's board formally responds to JANA. Second, whether early season pass sales hold up in the next earnings report. Until the board acts, FUN remains a turnaround story with a takeover option attached, not a takeover story.
Before you consider Six Flags Entertainment, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Six Flags Entertainment wasn't on the list.
While Six Flags Entertainment currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
The AI boom extends far beyond the biggest tech names. Discover 10 companies supplying the memory, storage, networking, semiconductor manufacturing, and power infrastructure that make AI possible. Learn where the next wave of AI investment opportunities may emerge—and the key risks investors should watch as the global AI buildout accelerates.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
