Aeluma’s NASDAQ: ALMU stock price is under pressure in 2026 because the market has no appetite for risky, cash-burning startups without real revenue.
However, Aeluma is not a run-of-the-mill startup, and a catalyst is in play that investors can capitalize on. The company is in the midst of a major transition, from research, development, and niche production to scalable manufacturing of advanced photonic equipment.
Aeluma Today
$11.42 -2.01 (-15.00%) As of 03:13 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $10.24
▼
$31.79 - Price Target
- $25.00
Photonics is critical to many advancing technologies, not just AI.
It enables faster speeds, more bandwidth, and greater reliability than copper wiring, especially in rugged or high-power applications, including data centers, aerospace, space, industrial, robotics, and quantum computing.
Highlights from fiscal 2026 indicate that Aeluma's timeline to commercialization is accelerating.
These highlights include intent to claim $30 million in CHIPS funding, $5.3 million in recently awarded government development contracts, an expanded leadership team, and advancing discussions for non-recurring engineering agreements.
Non-recurring engineering agreements don’t sound all that interesting, but they can be worth millions in revenue, validate the technology, lead to follow-on orders, and broaden demand. Follow-on orders matter most because they come from engineering design wins, locking this company’s photonic devices into a long-term product cycle.
Aeluma Reduces Costs and Improves Performance for Clients
Aeluma’s technology is one to watch as it could significantly disrupt the photonic industry. Current standards include “gluing” photonic components onto the silicon wafer substrate. It gets the job done but creates hurdles, including misalignments and signal degradation across the interface. Aeluma’s patented technology “grows” photonic materials directly onto the substrate, creating a two-sided wafer.
Aeluma’s process enables larger manufacturing volumes, reduces manufacturing steps, and produces a wafer that can pass through traditional foundry equipment without requiring specialized equipment. This means greater efficiency from the get-go: more wafers at lower cost, with less waste, fewer errors, and greater capacity to transfer optical input to the silicon circuits. Aeluma has what the semiconductor industry needs; what remains is product validation and the capacity to scale.
Aeluma Plunges After Earnings Are Released
Aeluma did not provide a bullish catalyst in its Q4 fiscal 2026 (FY2026) earnings report, and it was unlikely to. The market wants a contract win and real revenue, which is more likely in Q1 or Q2 of FY2027. Instead, Aeluma announced accelerated spending and wider losses, unpopular in today’s market. Even so, the spend is focused on team expansion, go-to-market efforts, and capacity, which align with the accelerating commercialization timeline.
Looking ahead, spending is expected to continue accelerating. The forecast is for approximately $11 million in capital expenditure on top of operating costs, compared to last year’s $9.1 million net loss. The key takeaway is that the balance sheet appears well capitalized, with more than $56 million on the books. This should be sufficient for the foreseeable future, potentially taking the company across the line to commercialization. As it stands, analysts expect revenue to ramp slowly over the next four quarters and then accelerate to a hyper, triple-digit pace in fiscal 2028.
Analysts and Institutions Signal Confidence in Aeluma
Aeluma MarketRank™ Stock Analysis
- Overall MarketRank™
- 42nd Percentile
- Analyst Rating
- Moderate Buy
- Upside/Downside
- 120.1% Upside
- Short Interest Level
- Bearish
- Dividend Strength
- N/A
- News Sentiment
- 0.65

- Insider Trading
- Selling Shares
- Proj. Earnings Growth
- N/A
See Full AnalysisAnalysts and institutions reflect optimism in Aeluma’s opportunity, if not an outright bullish stance. MarketBeat tracks only four with current coverage, but rates it a Moderate Buy with 75% Buy-side bias. Coverage and price targets have been fairly steady over the past year, including some summer activity.
The critical takeaway is the triple-digit upside forecast and improving institutional holdings. Institutional-quality investors, including insiders, corporations, funds, and private capital, own approximately half of the floating shares and ramped up their buying in early Q3. The likely outcome is that the group will provide a price floor near $11, as it has in the past.
The Risks Are Real, But the Selloff Looks Like a Bottom
Risks include short interest and dilution. The company’s non-revenue status, cash burn, and dilutive actions triggered short selling, lifting short interest to the 20% range in early September. The offset is that dilution is a diminishing risk and unlikely in the near term, given the balance sheet condition, and a contract win could trigger short covering.
In this scenario, institutions may also aggressively buy, leading to a short squeeze and a rocketing share price. A move to the consensus $25 will be a stepping stone toward even higher prices and new all-time highs.
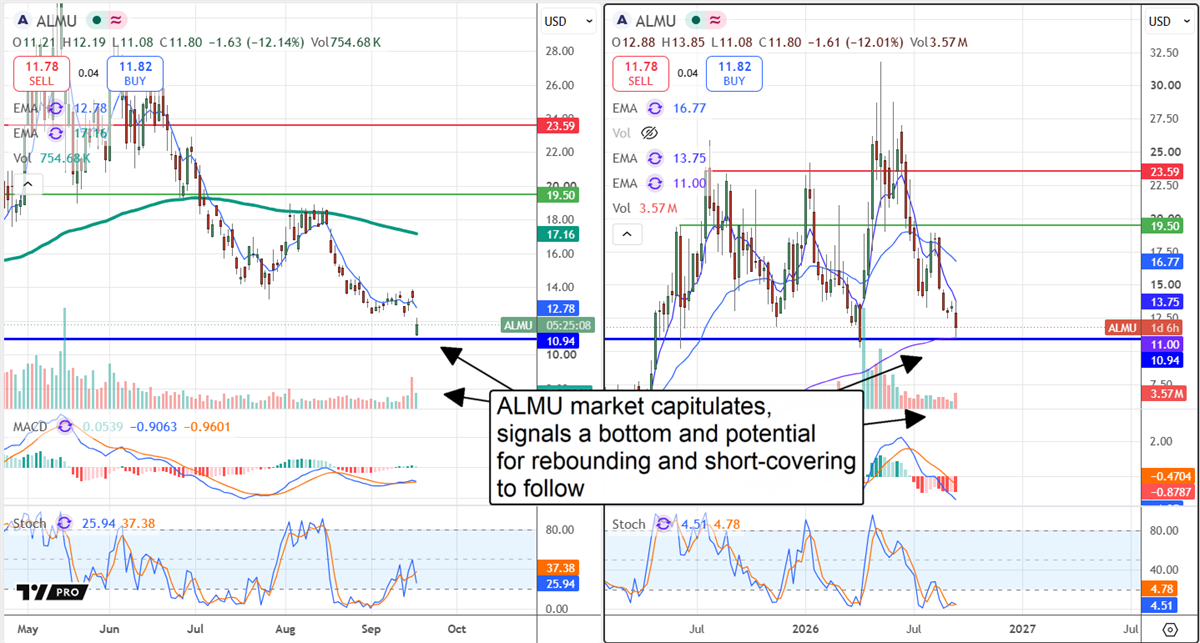
As bad as ALMU's post-release plunge seems, the move isn't entirely bearish, reflecting market capitulation and the potential for a bottom. Price action gapped lower at the open, set a new low, then moved higher from those lows, revealing support at a critical level. The likely outcome is that ALMU establishes a support base and rebounds, potentially very quickly, as it has done in the past.
Before you consider Aeluma, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Aeluma wasn't on the list.
While Aeluma currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
With the proliferation of data centers and electric vehicles, the electric grid will only get more strained. Download this report to learn how energy stocks can play a role in your portfolio as the global demand for energy continues to grow.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
