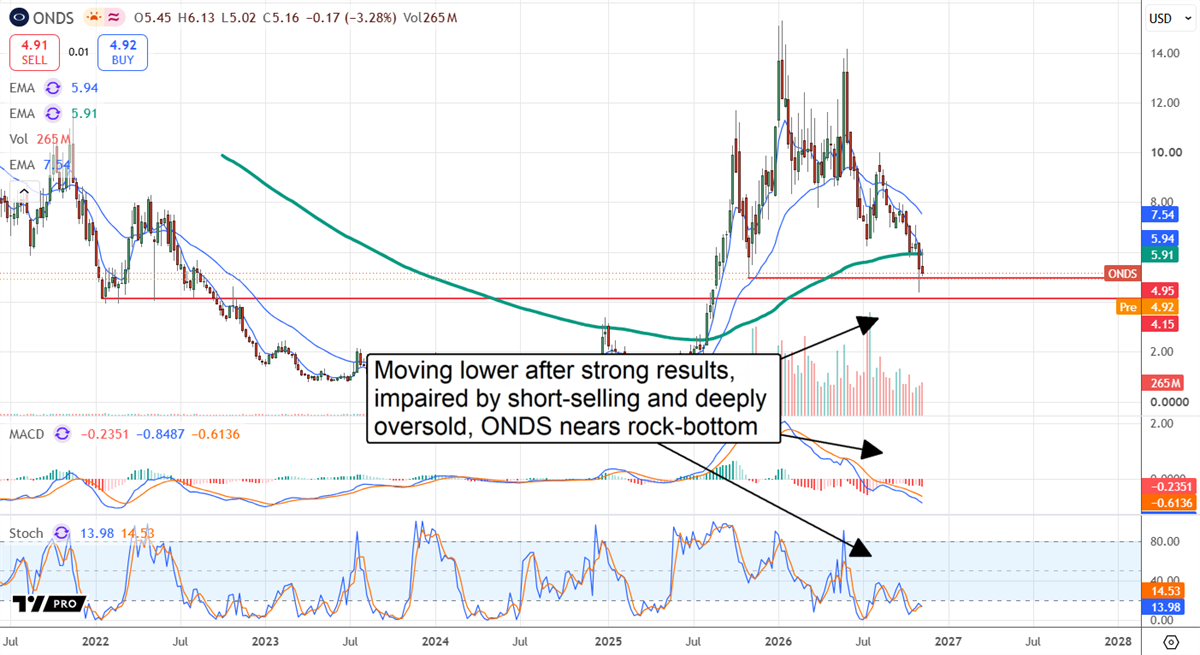
Ondas Inc. NASDAQ: ONDS is among a small but privileged set of small-cap defense companies poised for a growth wave that could take its stock price to new all-time highs. Struggling with execution risk in 2026, the stock price is down from its highs but could be setting up for a rebound if execution improves in the coming year.
The trigger is execution as the company builds on its earlier surge in orders and backlog and expands its NDAA-compliant defense capabilities and unmanned and autonomous systems business. That includes developing compliant products and reducing reliance on restricted Chinese-sourced components. Execution means ramping domestic manufacturing capacity, securing supply chains, and converting the rapidly swelling backlog into revenue, cash flow, and earnings.
Ondas’ business is unmanned and autonomous vehicles, drones, and defense AI applications. Operations span the defense and commercial sectors, both of which contributed to record third-quarter revenue of $167.5 million. Backlog is a potential catalyst in late 2026. Quarterly results are outperforming expectations, supported by a large, growing backlog worth more than a year’s business at the Q3 pace. Backlog growth supports the transition, rising about 35% in the quarter on $214 million in new bookings, as the business moves from early product qualifications to larger-scale orders.
Ondas Builds Momentum: Accelerates Profit Timeline
Ondas’ third-quarter revenue exceeded consensus estimates by more than 10%, topping $167 million, up 100% sequentially and more than 1,500% year over year (YOY), driven by broad-based business strength and acquisitions. Acquisitions helped drive scale, collaborative gains, and cross-selling opportunities, but did not overshadow organic growth. Pro forma organic revenue grew 64%, assuming all business lines were owned in the comparable quarter last year, and is expected to continue driving strength.
Margins remain a challenge despite the strong revenue growth. Acquisitions, related accounting adjustments, and production inefficiencies affected profitability, and financial results show that GAAP gross margin fell to 21.8% from 43.1% sequentially, while the adjusted EBITDA loss widened to $59.7 million. The GAAP loss was 10 cents per share, and adjusted profitability remains a forward-looking target. Guidance forecasts operating-platform adjusted EBITDA profitability in Q4 2026, and company-wide adjusted EBITDA profitability by Q3 2027, a full quarter sooner than anticipated.
Guidance provides more than one catalyst. Execs lifted targets for Q4 2026 and 2027 revenue, expecting quadruple-digit growth to persist another quarter and the business to double next year. Assuming no major hurdles arise, the forecast is likely cautious, given the bullish book-to-bill ratio of about 1.28:1 and industry trends, including a shift to unmanned and next-gen technologies that is accelerated by the NDAA deadlines.
Ondas’ catalysts include a strategic partnership with LightPath Technologies NASDAQ: LPTH. Ondas and Unusual Machines NYSEAMERICAN: UMAC each committed $4 million in 2025 to support LightPath's technology development and expansion. LightPath's defense technology strategy includes its BlackDiamond chalcogenide glass, which reduces reliance on Chinese-sourced germanium and supports the development of defense-compliant systems. The partnership should not be overlooked because BlackDiamond provides other benefits and strategic advantages, including performance, size, and weight; size and weight are critical for unmanned operations, enabling more payload and longer ranges.
Optimistic Analysts Highlight Near-Term Risks: Stock Price Remains Disconnected
Analysts have maintained a generally bullish outlook on Ondas, but their responses to the third-quarter report have been more cautious than the ratings alone suggest. Several firms lowered price targets following the release. Lake Street Capital and Needham each cut their targets from $19 to $14, while Stifel reduced its target from $18 to $15 on Nov. 16. All three retained Buy ratings, reflecting continued interest in the company's longer-term prospects despite concerns about margins and execution.
MarketBeat continues to show a Moderate Buy consensus rating, with 11 Buy ratings among the 13 analysts it tracks. The average price target remains well above recent trading levels, suggesting substantial potential upside. However, the downward revisions indicate that analysts have become more cautious about how quickly Ondas can turn its growing backlog into sustainable profitability.
Market positioning presents a more mixed picture. Institutional investors own approximately 38% of Ondas shares, while short interest remains elevated. As of Oct. 30, nearly 43% of Ondas' public float was sold short, with a short-interest ratio of 6.2 days based on average trading volume. However, shares sold short declined by approximately 3% from the previous reporting period. Elevated short interest could amplify a rally if positive developments trigger short covering, but it does not establish that short-sellers caused the stock's decline or guarantee a short squeeze.
Dilution is a risk. Capital-raising and acquisition activity drive the risk, lifting shares by more than 100% YOY for Q3, and may not be over. Acquisitions are likely to continue; the question is whether the company needs more cash. Balance sheet highlights suggest sufficient cash to cross the line into adjusted profits and positive cash flow, but don't guarantee that another capital raise isn't in Ondas' future.
Before you consider Ondas, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Ondas wasn't on the list.
While Ondas currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Oil still powers the global economy, but AI is reshaping the energy opportunity. Discover seven stocks spanning traditional energy, infrastructure, and next-generation power.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
