LightPath Technologies Today
LPTH
LightPath Technologies
$6.82 -0.39 (-5.41%) As of 12:33 PM Eastern
- 52-Week Range
- $5.83
▼
$18.94 - Price Target
- $14.38
LightPath Technologies NASDAQ: LPTH is at an inflection point seen across the defense technology landscape. The push to onshore production, meet defense sourcing requirements, and advance next-gen technologies (including drones and unmanned applications) catalyzed a massive business surge, pointing to acceleration, sustainability, and profits.
LightPath's catalyst centers on its optical and glass technology; BlackDiamond chalcogenide products offer major advantages, including lower weight, better performance, and reduced dependence on China. LightPath's BlackDiamond glass provides an alternative to germanium, a component China effectively controls and that is essential to many legacy infrared optical and imaging systems. Government funding, such as the Department of Defense’s Critical Low-Risk Electro-Optical Alternatives for Resilience (CLEAR) award, shows the utility and underlying demand.
LightPath Technologies Has an Active Catalyst in Play
The active catalyst, however, is plans to ramp capacity and swelling backlog. Following its exit from Chinese operations, management is ramping capacity, targeting tens of thousands of optical assemblies monthly and the potential to reach 100,000 monthly over time. Investors wondering whether hundreds of thousands of optical assemblies are needed will find evidence in the backlog data.
The company's Q1 fiscal year 2027 (FY2027) backlog surged 20% sequentially and 54% year over year, hitting a record near $133 million. The company also reported more than $30 million in follow-on orders through October, a new order for 50,000 assemblies, and a high percentage of orders requested for delivery within the next 12 months. The forward revenue outlook is bullish, with customers requesting delivery of about $110.8 million in existing backlog over the next 12 months. New business, awards, and follow-on orders could add to that pipeline.
Profitability is part and parcel of this catalyst. While the Q1 FY2027 release was mixed versus consensus, with revenue short of expectations, timing and the China exit are in play. More pertinent details include the 37.9% year-over-year (YOY) growth, led by the 76% increase in assemblies and modules revenue. Optical assemblies are the growth driver, critical to the outlook, and the higher-margin business; assemblies and modules now account for more than 50% of revenue, and the margin impact is clear.
LightPath’s GAAP losses narrowed in the quarter, while costs continued to reflect timing, repositioning, the China exit, and capacity ramps. Focus on gross profit, which surged 91.9% and grew more than twice as fast as revenue, and adjusted EBITDA, which grew 252.1%. The likely outcome is that the company could continue to strengthen margins over time as it ramps production capacity, shifts into higher-margin product lines, and leverages scale.
Analysts Reaffirm Ratings and Price Targets for LightPath
Initial analyst responses to LPTH’s results are generally positive. While at least one firm lowered its price target following the release, analysts continued to express confidence in the company, with commentaries focused on the backlog and production ramp rather than the Q1 weakness. LightPath has a Moderate Buy consensus rating and an average price target of $14.38, suggesting about 112% upside from recent trading levels, although price targets do not eliminate investment risks.
LightPath Technologies Stock Forecast Today
12-Month Stock Price Forecast:$14.38112.96% UpsideModerate BuyBased on 6 Analyst Ratings | Current Price | $6.75 |
|---|
| High Forecast | $15.50 |
|---|
| Average Forecast | $14.38 |
|---|
| Low Forecast | $13.00 |
|---|
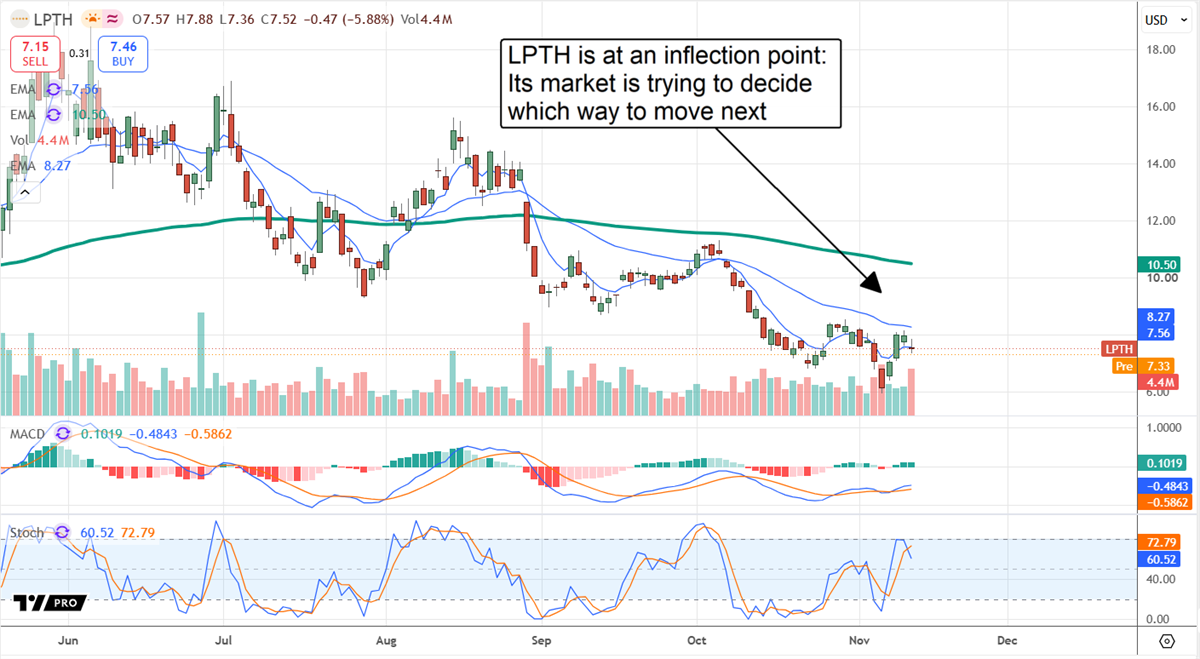
LightPath Technologies Stock Forecast DetailsStock price action is mixed since the release. While not bearish, it isn’t actively bullish, suggesting market indecision. Market indecision is also seen in the small candles formed in recent sessions, amounting to Spinning Tops, a well-recognized indication of uncertainty. However, uncertainty reflects a balance of risks versus rewards, and risks may be declining as potential rewards grow, suggesting a market reversal is possible and needs only time and company execution to complete.
What the market may be getting wrong is focusing on legacy business, spotty revenue, and execution risks instead of the end game. The end game is positioning itself as a potential beneficiary of changing optical sourcing requirements under the National Defense Authorization Act (NDAA). The law calls for a strategy to eliminate the Defense Department's reliance on covered nations, including China, for optical glass and systems by 2030, and defense contractors are locking in product now.
Defense contractors are locking in product now because the defense industry runs on a multiyear qualification and procurement pipeline. The takeaway is that LightPath is already well-positioned; it just doesn’t show up fully in the reported results yet, but could as production scales. In this scenario, today’s backlog surge is a drop in the bucket compared to what could come once qualifications are made, and the deadline draws closer. The market gets it right that execution risk will cause hiccups and delays, likely driving stock price volatility as the opportunity develops.
Dilution is another risk, as the company’s 2026 share sales substantially increased the share count, but the risk of further dilution remains. Balance sheet highlights include ample capitalization, a net-cash position, and a cash runway supported by the current balance sheet, although future spending could shorten it. Despite improving margins and positive adjusted EBITDA, another dilutive raise remains possible before LightPath achieves sustained profitability.
Before you consider LightPath Technologies, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and LightPath Technologies wasn't on the list.
While LightPath Technologies currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
The space race is growing fast, and you don’t have to have gotten in early on SpaceX to profit. This report shows seven space stocks you can buy today that may grow as rockets, satellites, defense, space internet, and new space technology become more important.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
