LightPath Technologies NASDAQ: LPTH is turning a corner, and investors should take note. The once globally focused business is taking a more domestic approach, divesting its China-based assets to comply with the National Defense Authorization Act.
LightPath Technologies Today
LPTH
LightPath Technologies
$9.01 -0.10 (-1.10%) As of 09:45 AM Eastern
- 52-Week Range
- $5.75
▼
$18.94 - Price Target
- $14.10
That alone is a trigger for business, but even more so given its shift toward defense and counter-drone technologies. The company’s infrared and germanium-free optics are critical to high-performance thermal imaging, including ruggedized defense and aerospace applications, and are in increasingly high demand.
Business is underpinned by clients such as Anduril and Lockheed Martin NYSE: LMT, which use the technology in their most advanced systems. Anduril, specifically, uses the tech in its AI-powered command and control platform, while Lockheed Martin is working to integrate it into numerous applications. LightPath's backlog is swelling, up nearly 200% in its fiscal Q4, and the likelihood is that business will continue to accelerate.
LightPath is emerging as a critical cog in the defense supply chain, not only for its capability, which provides strategic advantages, but also because of critical minerals. Germanium is a critical mineral controlled by China, and LightPath provides an alternative. It uses proprietary chalcogenide glass, marketed as BlackDiamond, which not only performs well but also enables size, weight, and power (SWaP) optimization, which is important for range and payloads. Autonomous vehicles using BlackDiamond are lighter, enabling longer range and larger payloads.
LightPath Has Illuminating Quarter, Revealing a Robust Growth Trajectory
LightPath posted a solid quarter, with fiscal Q4 revenue up 73% year-over-year (YOY) to just over $21 million, beating analyst expectations. This is the fourth quarter of year-over-year acceleration, with strong results expected in the subsequent year. The backlog, worth nearly $111 million at quarter’s end, is mostly current, with $85.6 million deliverable within the next 12 months. That alone is worth 20% growth and will be compounded by new orders.
Margin is another bright spot, with operating metrics improving, but net losses are still the story. Highlights include gross margin up 900 basis points and $4.2 million in adjusted EBITDA. Looking ahead, losses are expected to continue, as the company plans to ramp capital expenditure (CapEx) as it increases investment in capacity expansion. The good news is that margin expansion came from product mix and throughput, not price increases, revealing improving profitability with scale.
The biggest risk now lies in execution and cost, as the company is leaning hard into expansion and recently diluted shares. The offset is that the dilution injected enough capital to extend the runway, giving the company better visibility. As it stands, it is fully funded through next year and may not require additional capital. The balance sheet reflects the share sales, with cash up by nearly $90 million YOY, and virtually no debt.
Analysts Respond With Cautious Optimism
Analysts responded to the release with optimism, citing the backlog and expansion plans, but also caution, with wider-than-expected net losses and increased CapEx leading to some earnings forecast reductions. The group expects profits in fiscal 2028, so an inflection is ahead.
Until then, the consensus of the six analysts MarketBeat tracks is a Moderate Buy with an 83% buy-side bias. They see the stock advancing 55% to the consensus midpoint and as much as $15.50 at the high end. The likely outcome is that they remain cautious in the near term, potentially warming to the stock over the coming quarters as it executes on capacity and backlog.
Institutional activity is telling. The group owns more than 55% of the stock, a significant stake for such a small market cap, and is aggressively accumulating. While activity has been bullish for several consecutive quarters, Q3 activity is noteworthy, spiking to record levels alongside the stock price correction. The takeaway is that institutional traders recognized the opportunity and are capitalizing on it.
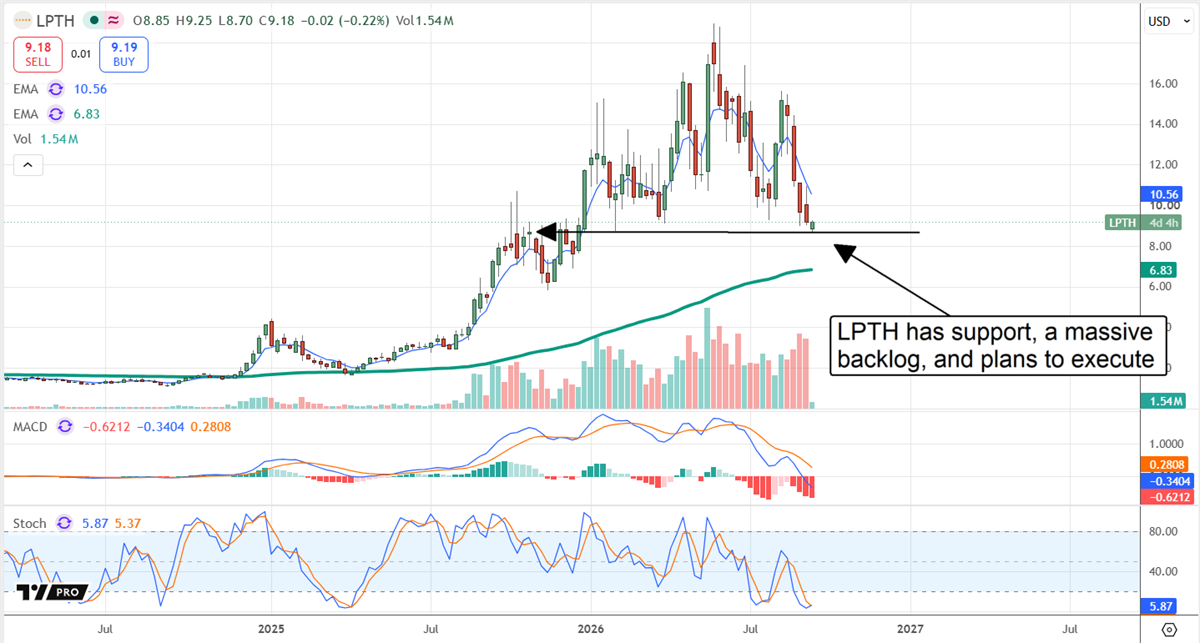
Chart price action is oversold and ready to rebound, potentially very strongly. Not only does the stochastic show a bullish crossover low in its signal range, but MACD divergence suggests the bottom is in. In this scenario, LPTH is on track to begin rebounding soon, but may not experience a robust recovery until later in the year or early in 2027. Short sellers remain in the market, creating a headwind to price action that may not ease without a strongly bullish catalyst.
Customer concentration and contract delays are among the risks. Its role in the defense supply chain opens the door to program and supply chain delays beyond its control. Recent delays include the Army’s Next Generation Short Range Interceptor schedule and redesigns on other projects.
Before you consider LightPath Technologies, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and LightPath Technologies wasn't on the list.
While LightPath Technologies currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Tesla, Nvidia, and Google helped shape the last era of market growth, but the next wave could come from a new group of companies. Inside this report, you’ll find 7 stocks that could play a major role in the next tech-driven market boom.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
