The AI trade is still alive and well, only shifting from speculation to execution, which is where investors stand to make the biggest gains. This portfolio aims to capture those gains, focusing on the names critical to AI’s success while balancing them against a trio of powerhouse cash-flow machines. The goal is a high double-digit compound annual growth rate, underpinned by capital gains, cash flow, and the power of compounding.
AI speculation drove sharp price increases as the market shoved money at any stock with AI in the name or business plan. The execution phase is marked by a focus shift from speculative what-ifs to the companies producing results: it may not produce the same sharp increases, but could generate larger gains over time, driven by growth and valuation. Some of these stocks may offer substantial upside based on long-term earnings forecasts, although those projections remain uncertain.
Results, signs of AI success stories, include demand for product, ramping capacity, swelling backlogs, and cash flow, the critical factor. While many AI stocks were punished in Q3 and early Q4, the ones producing cash flow may be better positioned to recover and sustain upward momentum. When the next major market peak arrives is anybody’s guess, as the AI build-out could continue for years.
NVIDIA: The Source of AI as We Know It
NVIDIA Today
$160.62 -5.57 (-3.35%) As of 12:22 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $148.80
▼
$243.37 - Dividend Yield
- 0.62%
- P/E Ratio
- 20.31
- Price Target
- $278.54
Jensen Huang’s indiscretion and potential spy hang-up isn’t good news for NVIDIA NASDAQ: NVDA shareholders, but it doesn't change the company's leading position in AI or Huang's role in shaping it. He is the architect of the critical hardware and software, including the CUDA developer platform for parallel computing. CUDA helps GPUs perform complex computing tasks beyond graphics, including the workloads that power modern AI. NVIDIA will go on without him, with its established GPU roadmap providing continuity as the company searches for a permanent CEO.
NVIDIA is central to the portfolio today for GPUs and the adjacent technologies that harness their power; it is central long-term because of the circular investment cycle Mr. Huang developed. GPU demand drives NVIDIA cash flow; NVIDIA cash flow invests in advancing AI technology; advancing AI technology drives demand for NVDA GPUs. Long-term earnings growth could support further gains, although forecasts that far into the future carry substantial uncertainty.
Advanced Micro Devices: Inference and the Edge
Advanced Micro Devices Today
AMD
Advanced Micro Devices
$522.71 -62.59 (-10.69%) As of 12:22 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $188.22
▼
$658.52 - P/E Ratio
- 113.81
- Price Target
- $640.11
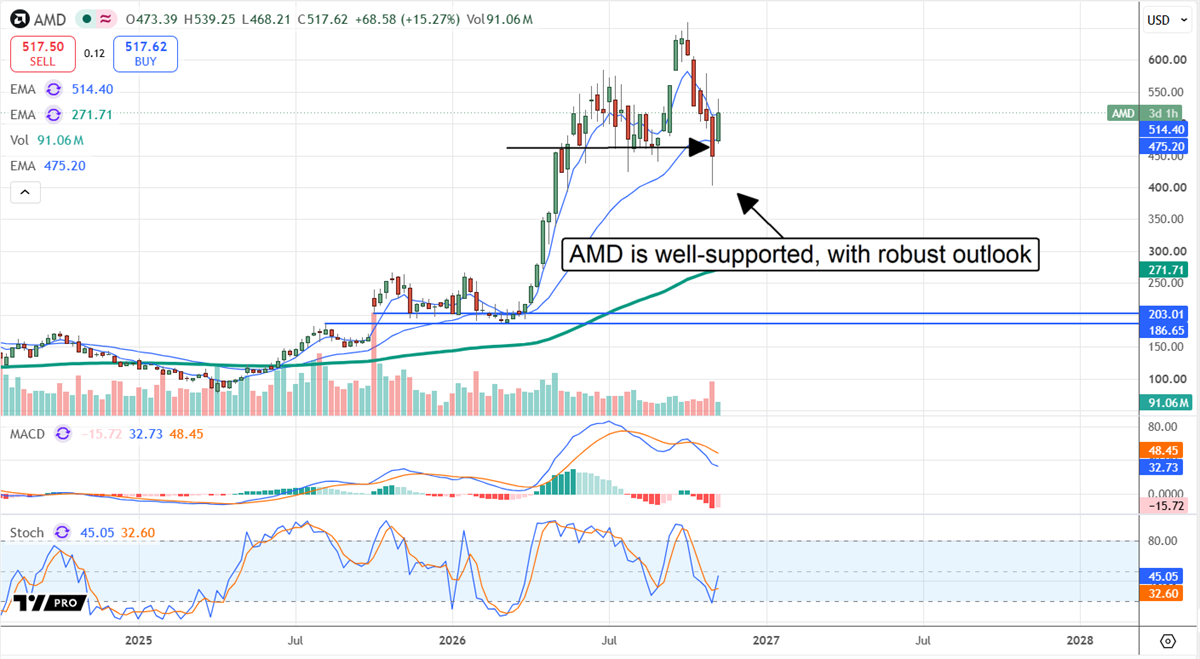
Advanced Micro Devices NASDAQ: AMD is central to the portfolio for its MI450 line and Helios rack architecture. They place AMD alongside NVIDIA as a major competitor in AI GPU clusters at scale.
More importantly, its clusters could compete on efficiency and cost in inference, which are key to hyperscale success. Additionally, AMD is a key player in the CPU market, also important to inference. Demand for CPUs alongside GPUs could grow as inference gains traction. Inference could become a much larger market than model training.
AMD’s long-term growth outlook depends heavily on Helios adoption, and analysts' earnings estimates could continue to change as deployments scale.
Micron Technology: AI and Inference Is All About Memory
Micron Technology Today
MU
Micron Technology
$758.36 -40.08 (-5.02%) As of 12:22 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $192.59
▼
$1,255.00 - Dividend Yield
- 0.08%
- P/E Ratio
- 10.23
- Price Target
- $1,407.88
Micron NASDAQ: MU is central to the portfolio because of high-bandwidth memory (HBM). Strong demand and constrained supply have supported elevated HBM prices, and those conditions are not expected to ease soon. Supply constraints could persist through 2028 or beyond.
Recent reports suggest demand will remain visible through 2030, setting the stage for the memory upcycle to linger for many years. Even when prices fall, demand could remain high, enabling MU to reap ample cash flow and fuel capital returns.
Dividends are a token amount; buybacks are a catalyst, accelerating in 2026 and potentially over time. MU’s forward earnings estimates may understate the duration of the memory upcycle, setting it up for a persistently bullish analysts' revision cycle.
Oracle: AI Infrastructure Player, Not Just a Database Company
Oracle Today
$123.64 -3.47 (-2.73%) As of 12:22 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $109.21
▼
$250.25 - Dividend Yield
- 1.62%
- P/E Ratio
- 19.43
- Price Target
- $249.27
Oracle NYSE: ORCL is among the biggest AI winners, effecting a systemic change from a simple software service to a hyperscale AI enabler. Leading AI labs and hyperscale enterprises book Oracle's cloud instances for advanced computing workloads and embed its legacy products into theirs.
It competes with megatech companies while selling them services and capacity, creating a symbiotic relationship that drives revenue for both. The opportunity today is the low, low price: the market punished Oracle’s shares for its debt and heavy AI infrastructure spending, even as its earnings outlook anticipates a return to positive free cash flow later in the investment cycle.
Credo Technologies and Astera Labs: 2 Sides of the Connectivity Coin
Credo Technology Group Today
CRDO
Credo Technology Group
$130.23 -9.58 (-6.85%) As of 12:22 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $86.49
▼
$308.67 - P/E Ratio
- 46.36
- Price Target
- $262.67
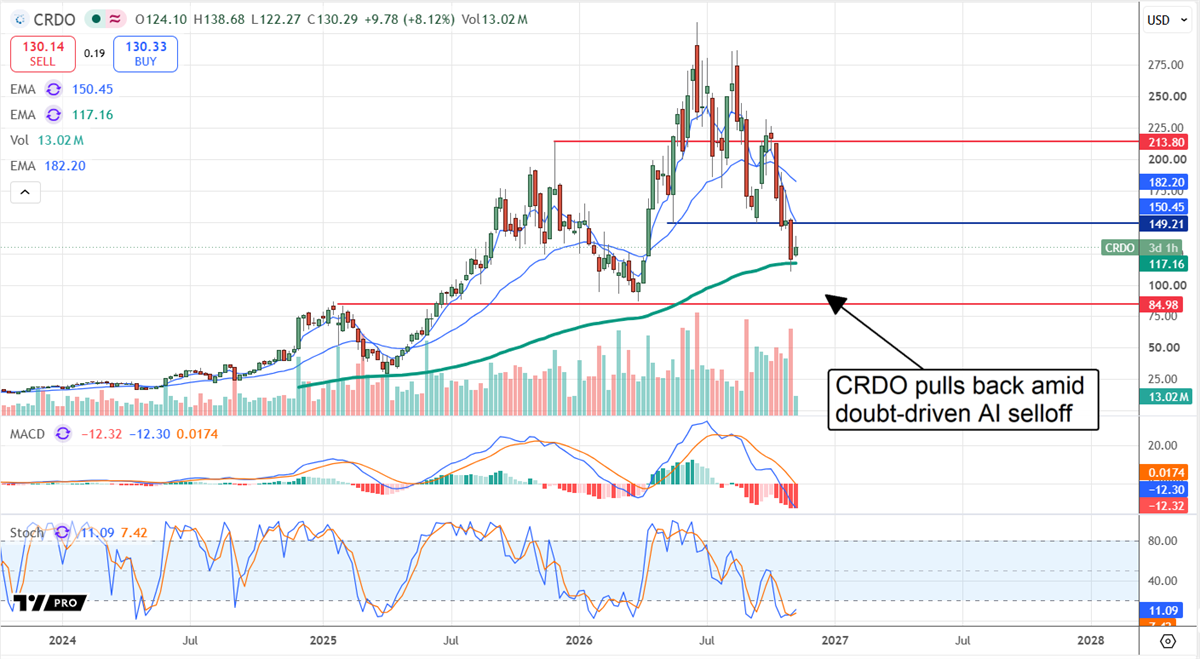
Credo Technologies NASDAQ: CRDO and Astera Labs NASDAQ: ALAB operate in the connectivity layer, providing services at different points in the AI chain. The key for investors is that their next-gen technologies are gaining adoption and could benefit from multiyear, potentially multigenerational product cycles.
This doesn’t mean a single win, but the potential for repeat business as new systems are deployed. In this scenario, they are in place to serve the AI industry at large and sustain high-level business, if not growth, for years to come.
Long-term earnings forecasts suggest substantial upside potential, although those gains depend on continued growth and execution.
Cerebras: Inference Engine Pureplay
Cerebras Systems Today
CBRS
Cerebras Systems
$105.73 +7.98 (+8.16%) As of 12:22 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $77.84
▼
$386.34 - Price Target
- $237.80
Cerebras NASDAQ: CBRS is critical to AI and this portfolio because of its inference technology. The large, dinner-plate-sized semiconductors reduce dependence on HBM by using substantial on-chip memory.
They work because their size lets them keep more model data on-chip; they add utility by reducing connectivity bottlenecks, speeding time to token and reducing overall costs.
Cerebras is approaching breakeven on a core operating basis, although the longer-term transition to sustained profitability remains uncertain, with future earnings growth offering potential upside over time.
Kroger: Dividends and Buybacks, Aisle 9!
Kroger Today
$71.07 +1.26 (+1.81%) As of 12:22 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $54.15
▼
$76.58 - Dividend Yield
- 2.19%
- P/E Ratio
- 38.64
- Price Target
- $70.35
Kroger NYSE: KR is central to this portfolio for its blue-chip position in consumer staples.
As the leading independent grocery chain, the business is supported by daily essentials that drive consistent cash flow.
Growth isn’t substantial but is present, underpinning a dividend distribution increase cycle that drives shareholder value.
Kroger has increased its payout for 20 consecutive years and continues to move closer to Dividend Champion status.
PepsiCo: Cyclical Recovery Drives Value
PepsiCo Today
$144.22 +1.96 (+1.37%) As of 12:22 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $123.47
▼
$171.48 - Dividend Yield
- 4.10%
- P/E Ratio
- 18.12
- Price Target
- $143.28
PepsiCo NASDAQ: PEP is key to this portfolio for its balance sheet health, cash flow consistency, and capital return.
It's also well positioned amid a cyclical recovery as it recovers from company-specific issues and shifts to meet consumer demands, including higher-protein snacks.
Valuation is also a factor; PepsiCo trades at a relatively low valuation compared with recent years, offering a value opportunity relative to peers like The Coca-Cola Company NYSE: KO and a higher-than-average yield of about 4.1% as of mid-Q4.
Casey’s General Stores: Self-Funding the Future
Casey's General Stores Today
CASY
Casey's General Stores
$709.42 +2.79 (+0.39%) As of 12:22 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $529.84
▼
$927.85 - Dividend Yield
- 0.37%
- P/E Ratio
- 34.24
- Price Target
- $835.38
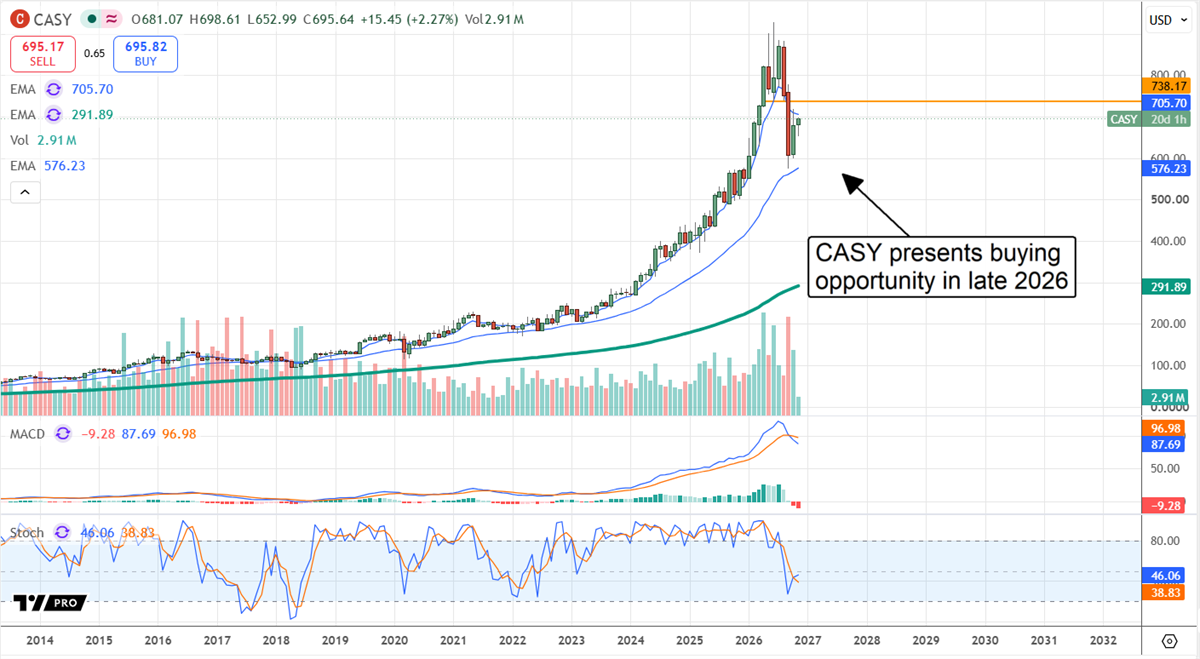
Casey’s General Stores NASDAQ: CASY merits a spot in this portfolio because of its healthy balance sheet, capacity to self-fund growth, cash flow, and capital returns.
Capital returns include dividends and share buybacks, with buybacks helping reduce the share count when cash flow isn’t focused on acquisitions.
Acquisitions such as Fikes in 2024 expand the company’s footprint while providing cost-saving opportunities and a platform for expansion.
Looking ahead, continued consolidation in the convenience store/gas station industry could create additional opportunities for acquisitions and capital returns.
Before you consider NVIDIA, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and NVIDIA wasn't on the list.
While NVIDIA currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Discover the next wave of investment opportunities with our report, 7 Stocks That Will Be Magnificent in 2026. Explore companies poised to replicate the growth, innovation, and value creation of the tech giants dominating today's markets.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
