NVIDIA NASDAQ: NVDA strengthened the case for massive share price upside by announcing a record-breaking $150 billion share buyback authorization. Backed by its cash flow and balance sheet, the buyback sends several bullish signals.
At face value, the authorization affirms NVIDIA’s confidence in future cash flow, which, in turn, validates the AI buildout. In addition, investors can assume downside is limited on price pullbacks, as NVIDIA is likely to keep buying back shares when prices dip.
NVIDIA Today
$166.19 -7.54 (-4.34%) As of 04:00 PM Eastern
- 52-Week Range
- $148.80
▼
$243.37 - Dividend Yield
- 0.60%
- P/E Ratio
- 21.01
- Price Target
- $283.63
The question is, how much strength does the authorization give? Record or not, $150 billion is a drop in the bucket against NVIDIA’s $5.4 trillion valuation, about 2.7% of the market cap, to be exact.
However, the signal is that buybacks can be expected to continue at their current pace indefinitely, as the total remaining authorization is valued at roughly 4% of the market, with further authorization increases likely.
NVIDIA’s share buybacks are significant, giving investors increasing quarterly leverage. Highlights from Q2 show share count reduction accelerating to about 1% on average over the trailing 12 months, a pace likely to continue in the coming quarters unless it accelerates further. Either way, the company can sustain the $19.7 billion Q2 pace for the foreseeable future, setting the stage for sustained and substantial share count reduction over time.
NVIDIA's Explosive Gains Are Over, Steady Compounding Ahead
Investors and traders looking for big, triple-digit gains in under 12 months might want to look elsewhere, as NVIDIA’s days of producing those types of returns are likely over. However, investors looking for sustainable, incremental annual returns, compounded by share-count leverage and dividends, have a robust runway ahead.
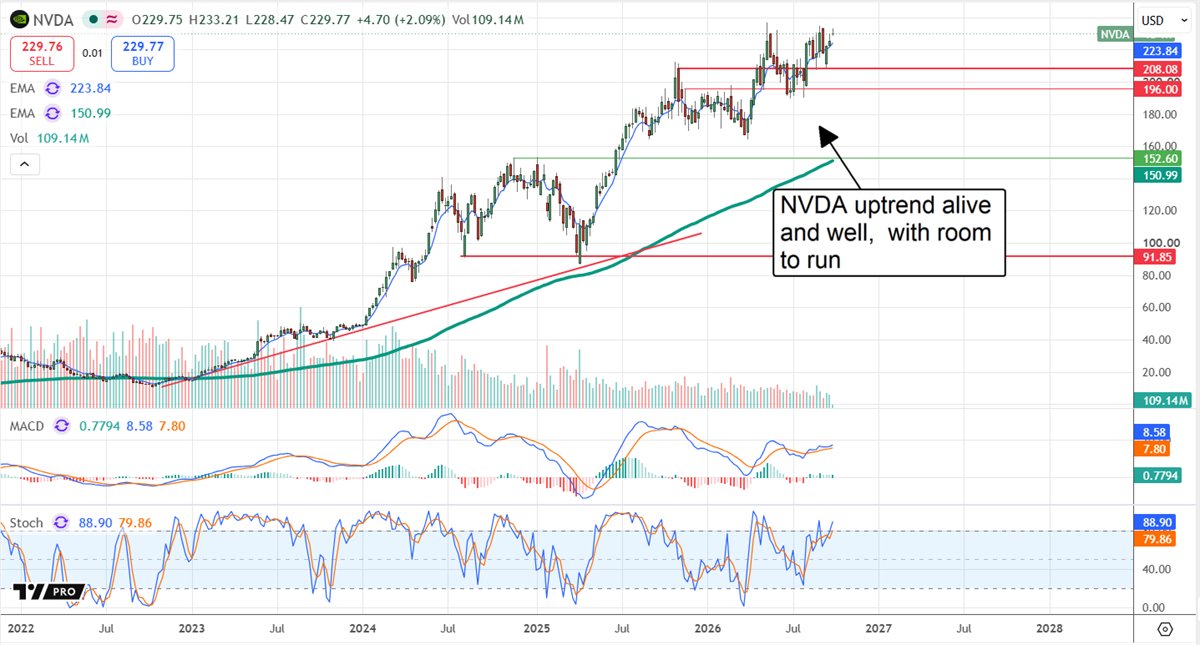
While technical price action suggests upcoming moves will be short, potentially jerky, and likely followed by longer consolidations, the growth and valuation metrics suggest many short-term stock price spurts for investors to capitalize on. Long-term earnings forecasts suggest NVIDIA trades at pennies on the dollar; the stock is set up to advance by 400% over the next 10 years as it executes its strategy.
Is NVIDIA wasting money on share buybacks? No. NVIDIA’s AI dominance, built on GPUs but driven by CUDA, connectivity, and software services, provides robust cash flow. Q2 adjusted net income approached $54 billion, more than double the capital return, which includes both buybacks and dividends. This profitability, along with trailing-12-month free cash flow, has enabled both aggressive acquisitions and responsible balance sheet maintenance.
Balance sheet highlights help put any misgivings to rest, including more than $160 billion in cash, securities, and receivables. Liabilities and debt are also rising, but marginally and in response to increased operational load, with total liabilities well below the company’s liquidity position.
Analysts Cheer as NVIDIA’s Buyback Drives Confidence
Analysts liked NVIDIA’s buyback announcement, highlighting it as a sign of financial strength, a mechanism to soothe AI spending fears, and a signal that management thinks the stock is still cheap. While no analysts revised their price targets immediately after the announcement, the chatter reaffirmed the trend, which includes increasing analyst coverage of the stock and high conviction in the Buy rating. The consensus forecasts a 40% upside from late-September highs, but the trend matters more, pointing to a high-end range of $515 and more than 100% upside.
Among NVIDIA’s catalysts is the launch of its open-source Open Agent Safety Platform. It responds to the growing number of AI “incidents” and is intended to keep developers ahead of the curve. The platform runs on two systems: the first lets users set and enforce controls; the second provides a watchdog to detect and intervene with suspicious agents. The assumption is that incidents such as the one at Hugging Face could have been prevented; the outcome is that NVIDIA’s leadership position remains unassailable.
NVIDIA’s biggest risk is obsolescence. It is essential to AI today, but labs and hyperscalers are working on proprietary technology across the industry. One or more of them could disrupt the hardware or software stack, making NVIDIA one of many choices. Until then, hyperscalers continue to rely on NVIDIA hardware, with proprietary technology years, if not a decade, away from availability at scale. Proprietary technologies will one day exist alongside NVIDIA, helping differentiate hyperscalers but not displacing NVIDIA from its moat.
The market gets the timing of AI monetization wrong; it comes in waves and plays out over years. The first wave is the initial build-out, which is what’s been underway and is expected to continue. The second is the monetization of investments made over the past three years, which has begun for NVIDIA and companies like Oracle NASDAQ: ORCL and is expected to gain momentum over the next three years. In this scenario, NVIDIA’s dependence on GPUs for growth fades over time in favor of the ancillary technologies built upon those GPUs, of which there are many. Key areas include automotive and robotics, as well as the implementation of physical AI.
Before you consider NVIDIA, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and NVIDIA wasn't on the list.
While NVIDIA currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
The AI boom extends far beyond the biggest tech names. Discover 10 companies supplying the memory, storage, networking, semiconductor manufacturing, and power infrastructure that make AI possible. Learn where the next wave of AI investment opportunities may emerge—and the key risks investors should watch as the global AI buildout accelerates.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
