The software business is a tough industry these days. A $100 billion company trading at 14 times earnings can report a double beat and raise guidance, and its stock still might sell off afterward. That’s exactly what happened to Adobe Inc. NASDAQ: ADBE when it reported its fiscal Q3 2026 results after hours on Sept. 10.
The stock had been slowly recovering some of its losses over the last few months, but was still down nearly 30% on the year. And despite the strong headline numbers, this earnings report did little to dispel market fears.
M&A Makes Headline Numbers Appear Stronger Than Reality
When Adobe’s fiscal Q3 2026 results first hit the screen, it appeared to be a clean-cut beat. The company reported record quarterly revenue of $6.76 billion, up 12.9% year over year (YOY).
Adobe Today
$265.60 +13.37 (+5.30%) As of 04:00 PM Eastern
- 52-Week Range
- $190.12
▼
$370.86 - P/E Ratio
- 14.82
- Price Target
- $282.68
Earnings per share (EPS) also surpassed expectations, total ending annualized recurring revenue (ARR) was up 11.2% YOY to $27.50 billion, and management raised full-year 2026 EPS and revenue projections ahead of the final fiscal quarter. But it’s that total ending ARR number that spiked the punchbowl, and it needs scrutiny due to the Semrush acquisition.
Earlier this year, Adobe acquired Semrush for $1.9 billion, with the transaction closing in Q2. Management projected Semrush to add $480 million in ending ARR, and fiscal Q3 was the first full quarter in which it realized this, with subscription revenue projected at $280 million for the period. If you subtract the M&A-aided portion of ending ARR from the total, you’re left with a growth rate in the single digits, not 11.2%. Management admitted that its push to add new members through “freemium” products contributed to a 36%-37% YOY decline in new net ARR, and this likely caused the sell-off. Current remaining performance obligation (cRPO) growth of 9% also lags revenue, suggesting forward demand growth is slowing relative to recognized revenue.
Guidance Projections Have Analysts Punting to Q4
The market hoped for color on fiscal 2027 projections, but management offered only fiscal Q4 updates and deferred all 2027 calls. Management expects fiscal Q4 revenue of $6.80 billion to $6.85 billion, bringing the full-year 2026 projection range to $26.58 billion to $26.63 billion. Year-end operating margin is projected at approximately 45%, with full-year EPS between $18.12 and $18.17.
But analysts weren’t impressed with the guide, especially since the company failed to make any 2027 projections amidst its freemium software push. When information is scarce, the market will confirm its priors, and analysts will kick the can down the road. And that’s the pattern playing out in the analyst community following Adobe’s earnings results.
Of the 33 analysts covering ADBE shares, seven adjusted their price targets on the Friday after the conference call. Among the five who raised, the average target climbed from $235 to $259. Meanwhile, JPMorgan Chase cut its target from $340 to $315, and Jefferies cut its target from $285 to $275.
The gap between price targets remains extreme, but it's closing as bullish analysts lower their targets and bearish analysts raise theirs. ADBE shares recovered some losses on Friday after the report, closing just over $250 per share. The average price target among the analysts who made post-earnings adjustments is $269, implying just 7% upside from the Friday close. Analysts covering ADBE must be practicing for the NFL season, since these adjustments are the equivalent of punting their calls into the fourth quarter.
ADBE Daily Stock Chart Shows Decline Accelerating
ADBE shares briefly joined the software renaissance this summer, rising from $193 to $293 in just over eight weeks. But the stock is still down more than 25% over the last 12 months, and when the calendar flipped to September, buyers fled the stock like beachgoers fleeing their rentals after Labor Day.
The stock closed lower in six of the seven trading sessions preceding earnings as traders began parsing the odds of a potentially poor report. And now, a few key technical levels are in jeopardy, threatening to intensify the decline even more.
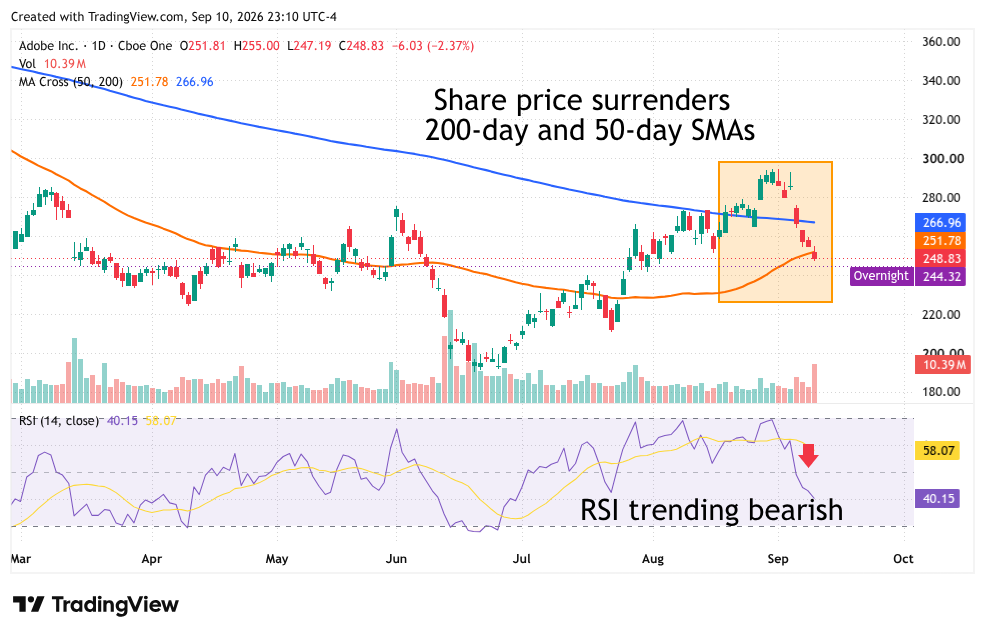
ADBE briefly poked its head above the 200-day moving average at the end of August, but this move turned out to be just a bull trap, and the stock quickly retreated back under this crucial level. Making matters worse, the 50-day moving average was breached for the first time since mid-July in the after-hours session following the earnings release.
The relative strength index (RSI) confirmed the downward momentum by falling below the bearish threshold of 50, indicating that sellers are once again firmly in control of the stock. Investors should watch the RSI for any oversold signals that could trigger a rebound, but the stock will likely need to retake the 200-day moving average to regain sustained upward pressure.
Before you consider Adobe, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Adobe wasn't on the list.
While Adobe currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
The AI boom extends far beyond the biggest tech names. Discover 10 companies supplying the memory, storage, networking, semiconductor manufacturing, and power infrastructure that make AI possible. Learn where the next wave of AI investment opportunities may emerge—and the key risks investors should watch as the global AI buildout accelerates.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
