Conagra Brands Today
CAG
Conagra Brands
$13.38 +0.18 (+1.36%) As of 10/2/2026 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $12.53
▼
$20.32 - Dividend Yield
- 5.23%
- Price Target
- $14.07
dividend
cut wasn’t pretty, but it was the right move at the right time, enabling a quicker turnaround for this value play. On the surface, the cut helps with debt reduction, supply chain upgrades, and brand investments, but it has a deeper implication, and the results are already evident: better-than-expected margins. Conagra’s turnaround efforts center on brand recovery and revenue growth, but also earnings quality, which improved
in Q1 fiscal year 2027 (FY2027), earlier than analysts or even the company had anticipated. In the words of CEO John Brase, the company shows “measurable progress across the business.”
The new dividend payment is reliable, yielding approximately 5% with shares near long-term lows. The risk today is that dividend increases won’t resume for years, but it's possible increases could resume as early as next year, assuming the company continues building momentum. Today’s catalyst, however, is confidence in the payment and turnaround efforts, as reflected in analyst and institutional trends. For them, the sub-10x current-year earnings price multiple and roughly 5% dividend yield make this market-leading consumer staple potentially compelling at current levels.
Institutions See Value Before Analysts Do
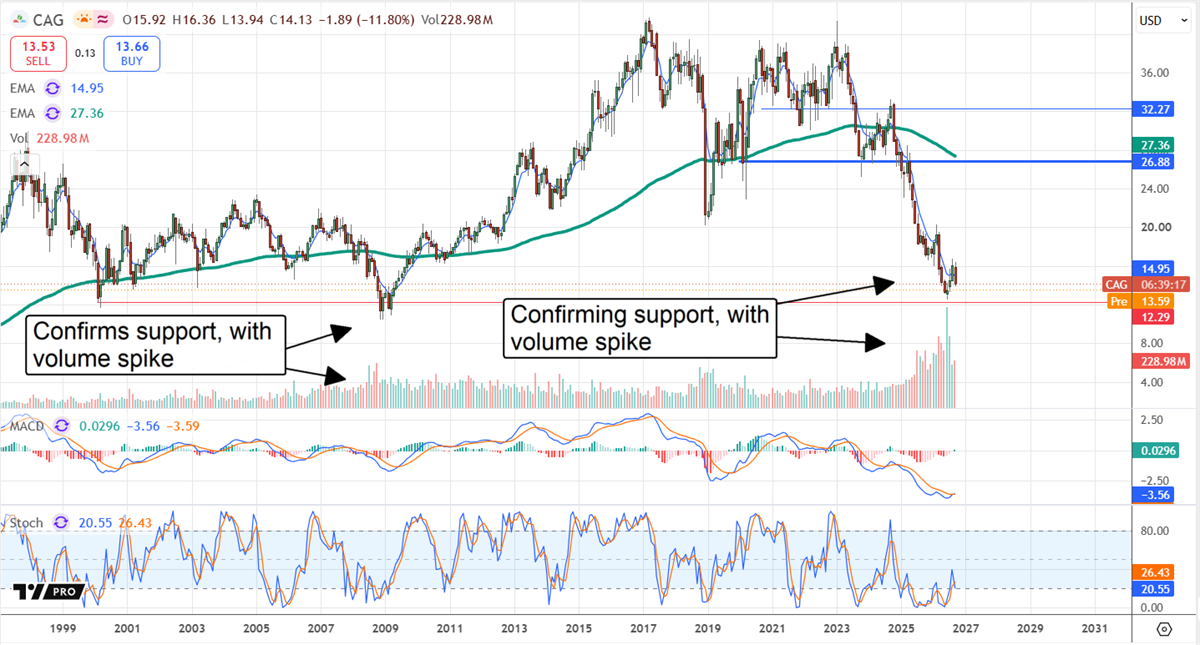
Institutional activity is noteworthy because this group, which owns about 84% of the floating shares, has bought on balance in most quarters over the past two years, through the stock's downturn. More importantly, activity ramped up as price action moved lower, with trading volume peaking as shares approached historically low levels, triggering a rebound just above the multi-decade support target. This suggests support at a critical level, though it does not rule out further downside while the market waits on Conagra’s turnaround to unfold.
Analysts' trends are less obviously bullish. The consensus of 18 tracked analysts is Reduce, and the average price target suggests limited upside from recent trading levels. Bullish signals include increased coverage, a consensus price target that has edged slightly higher over the past month, and six Sell ratings among the 18 analysts, suggesting bearish sentiment may be stabilizing rather than reversing. While they don't provide a catalyst for a rebound today, they reinforce the bottom signaled by institutions and may start improving ratings as the quarters progress.
Chart action is highly suggestive that a solid floor is in place. Volume has spiked to record-high levels, and the long-term monthly chart shows deeply oversold conditions and early signs of accumulation. While downside risk remains, the market is unlikely to move significantly below the $12 level, which would likely trigger a robust buying response if it does.
Conagra Beats Expectations But Keeps Guidance Conservative
Conagra’s Q1 FY2027 wasn’t great, but it beat expectations, especially on the bottom line, which matters most. Net revenue was $2.6 billion, down 1.4% year over year (YOY), slightly outpacing consensus as pricing offset the impact of volume decline. Organically, revenue fell by 1.1%, with a 1% pricing gain offset by a 2.1% volume loss. Segmentally, the company showed the strength of its operating model and growth avenues, with domestic Grocery and Refrigerated down by 2.6% and 2.1%, and International and Foodservice up by 2.7% and 3.2%, respectively. Within this, foreign exchange accounted for 20 bps of the total decline, and merger & acquisition activity accounted for about 50 bps.
Weak Growth Overshadows Conagra’s Structural Improvement
Conagra Brands MarketRank™ Stock Analysis
- Overall MarketRank™
- 69th Percentile
- Analyst Rating
- Reduce
- Upside/Downside
- 5.1% Upside
- Short Interest Level
- Healthy
- Dividend Strength
- Strong
- News Sentiment
- 0.21
- Insider Trading
- N/A
- Proj. Earnings Growth
- 6.85%
See Full AnalysisMargin news was also better than expected, with gross margin declining less than forecast and SG&A improving more. The net result was a 4.3% increase in adjusted earnings, or 41 cents per share, up 5.1% YOY and more than 10 cents above expectations. The bad news is that management only reaffirmed guidance, despite Q1 FY2027 strengths, setting the stage for outperformance in the upcoming quarters.
Other pertinent details include reduced debt and interest expense. Capital management and earnings quality reduced total debt, with a 2.5% decline in net debt and a 2.14% decline in interest expense, which helps free up future cash flow. With this in play, investors can expect debt reduction to accelerate in future quarters, keeping the company on track to reach its fiscal year-end goals.
Conagra’s risks are centered on consumer trends and the timing of its turnaround. As good as the Q1 FY2027 release is, signs of persistent weakness remain, including negative organic growth and free cash flow. The market gets it wrong, however, to punish the stock for its lack of growth while overlooking the strong execution and stabilization signals. The company is on the cusp of reverting to systemwide growth with stronger margins, reduced debt, and improved cash flow, which are levels for an accelerated earnings recovery and capital return machine.
Before you consider Conagra Brands, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Conagra Brands wasn't on the list.
While Conagra Brands currently has a Reduce rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Looking to profit from the electric vehicle mega-trend? Click the link to see our list of which EV stocks show the most long-term potential.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
