Medicare for All is back on Wall Street's radar. Democrats won control of both the House and Senate in the Nov. 3, 2026, midterm elections. Healthcare affordability ranked near the top of voter concerns. That raises a fresh question for investors. Which stocks could benefit if single-payer healthcare gains traction?
To be clear, the policy is not imminent and faces obstacles. President Donald Trump holds veto power until January 2029. The Senate filibuster remains a major hurdle. Still, markets price momentum while waiting on legislation. Recent KFF polling shows 66% of U.S. adults support Medicare for All, including 84% of Democrats. More than half of the House Democratic Caucus already back the idea.
The Trade May Lie in Companies That Have a Payer Problem
The instinctive trade is to reach for familiar healthcare names. Telehealth platforms and senior living operators come to mind first. But that perception may not be backed by fundamentals.
For example, Hims & Hers Health NYSE: HIMS built its model around cash-pay customers who avoid insurance. Universal coverage could weaken that appeal. Brookdale Senior Living NYSE: BKD relies mostly on private-pay residents for services Medicare doesn't cover.
The clearer winners may be companies with a payer problem. Medicaid typically reimburses providers at lower rates than Medicare. However, the proposed Medicare for All Act would establish a new fee schedule rather than automatically raise payments to current Medicare rates. It also restricts the use of program funds for provider profits. Expanded vision coverage could create additional opportunities. Here are three healthcare stocks that fit that thesis, along with what their charts are saying.
The Steady Compounder Already Breaking Out
Addus HomeCare Today
$126.46 -1.49 (-1.16%) As of 02:50 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $87.95
▼
$131.59 - P/E Ratio
- 21.08
- Price Target
- $130.25
Addus HomeCare NASDAQ: ADUS provides in-home personal care, hospice, and home health services. Personal care is the core business, and state Medicaid programs are its primary payers. Medicare for All proposals emphasize home- and community-based long-term care. That puts Addus squarely in the path of potential new spending.
The fundamentals are already solid. Third-quarter net service revenue rose 7% to $387.7 million. Adjusted EBITDA climbed 13.5% to $51.2 million. Adjusted earnings per share (EPS) reached $1.83, up from $1.56 a year earlier. The company also agreed to acquire AccentCare's personal care division for roughly $275 million.
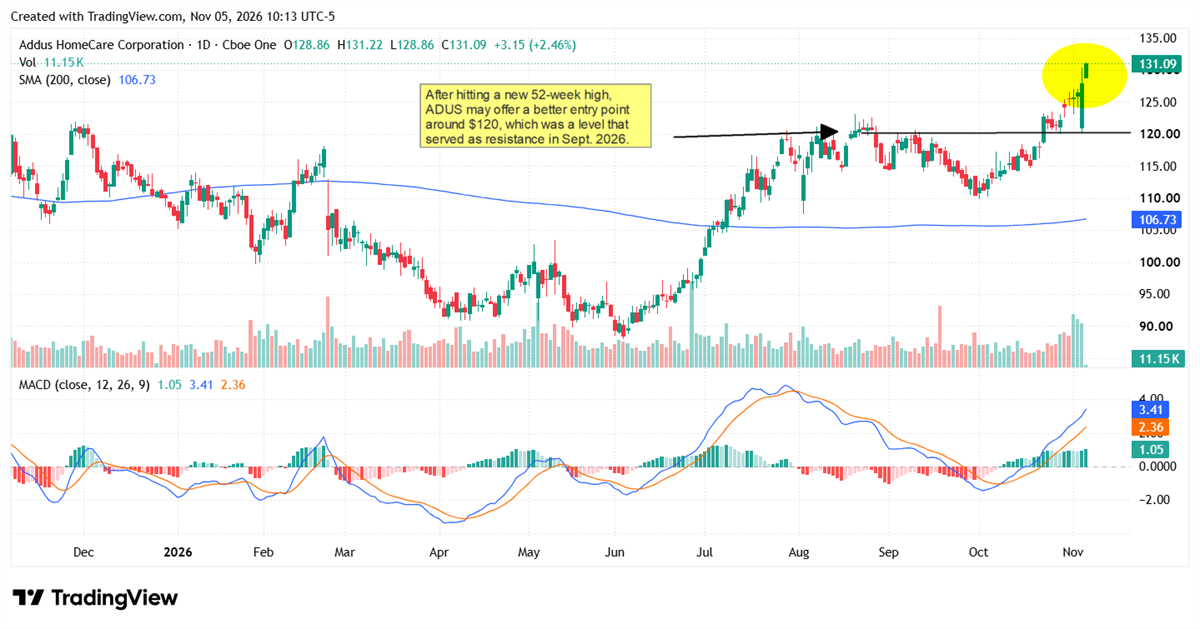
The chart confirms the momentum. ADUS traded at a new 52-week high near $131 on Nov. 5, clearing its prior peak around $124. Shares sit well above the 200-day moving average of about $107. The MACD is above its signal line and rising. The risk is extension. The stock trades roughly 23% above its 200-day, so a pullback toward $120 would not be surprising.
The High-Beta Reimbursement Story
Aveanna Healthcare Today
AVAH
Aveanna Healthcare
$13.72 -0.51 (-3.55%) As of 02:50 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $5.93
▼
$14.71 - P/E Ratio
- 11.16
- Price Target
- $14.25
Aveanna Healthcare NASDAQ: AVAH offers the most direct exposure to the reimbursement thesis. Its largest segment, private duty services, provides home nursing for medically fragile children and adults. Medicaid funds most of that care. Low state reimbursement rates have long pressured margins. Higher reimbursement rates could address the company's central constraint, but Medicare for All does not guarantee them.
Operations have already improved sharply. Private duty services revenue grew to $553.9 million in the second quarter, up from $486 million a year earlier. Companywide net income rose to $40.3 million from $27 million. However, private duty services gross margin fell to 28.9% from 32.5%. Investors will get a fresh update when Aveanna reports third-quarter results before the market opens on Nov. 12.
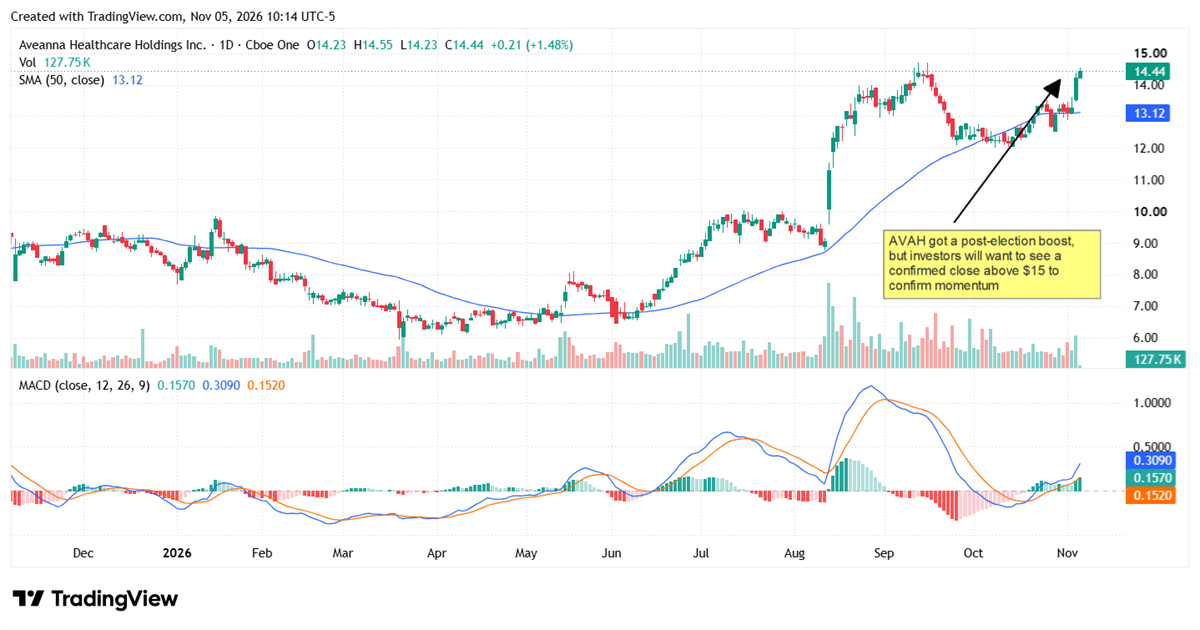
Technically, AVAH has roughly doubled since its spring lows near $6.50. Shares climbed to near $14.44 on Nov. 5, pressing against the September high just under $15. The 50-day moving average sits near $13.12 and is still rising. The MACD has crossed back above its signal line with an expanding histogram. A close above $15 would mark a breakout. Earnings make that a binary setup.
The Contrarian Turnaround
National Vision Today
EYE
National Vision
$17.92 -0.02 (-0.11%) As of 02:50 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $14.75
▼
$30.02 - P/E Ratio
- 29.33
- Price Target
- $29.82
National Vision Holdings NASDAQ: EYE operates more than 1,200 value-focused optical stores, led by America's Best. Major Medicare for All proposals would add vision coverage, although the current House bill does not explicitly guarantee coverage for eyeglasses. That could turn today's cash-pay shoppers into covered customers. Managed care accounted for about 42% of National Vision's 2025 revenue from continuing operations.
The turnaround is showing up in profits. Second-quarter adjusted operating income rose to $31.6 million from $23.8 million. Adjusted EPS increased to 25 cents from 18 cents. Revenue growth was slower at 2.5%. Still, management raised the low end of full-year adjusted EPS guidance. The new range is 94 cents to $1.09.
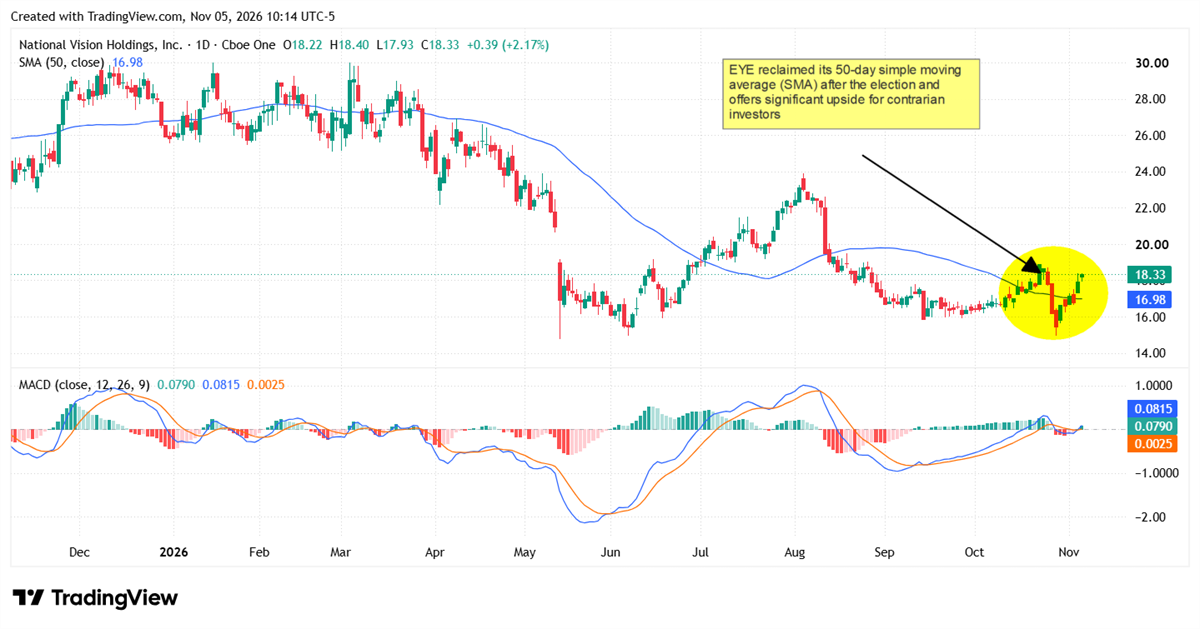
This is the weakest chart of the three, which makes it the contrarian pick. EYE remains far below its March high near $30. Post-earnings gaps in May and August broke the uptrend. But shares just reclaimed the 50-day moving average near $17 and traded around $18.33 on Nov. 5. The MACD has crossed above its signal line. Resistance near $19 and $20 is the real test.
Separating Policy Noise From Business Models
Medicare for All may not become law this decade, if ever. Even so, the debate will resurface often over the next two years. Each headline could move healthcare stocks. Investors should look past the obvious names and focus on payer exposure. Companies that rely on low Medicaid rates or uncovered services could see significant changes, though the extent of any benefit depends on the final reimbursement and coverage rules.
Addus offers momentum and steady profitability. Aveanna offers leverage to reimbursement reform. National Vision offers a turnaround with a policy kicker attached. None of the three needs Medicare for All to work. That may be the most attractive part of the setup.
Before you consider Addus HomeCare, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Addus HomeCare wasn't on the list.
While Addus HomeCare currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Discover the next wave of investment opportunities with our report, 7 Stocks That Will Be Magnificent in 2026. Explore companies poised to replicate the growth, innovation, and value creation of the tech giants dominating today's markets.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
