Cracker Barrel Old Country Store Today
CBRL
Cracker Barrel Old Country Store
$51.64 -0.20 (-0.38%) As of 01:11 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $24.85
▼
$60.26 - Dividend Yield
- 1.94%
- P/E Ratio
- 36.85
- Price Target
- $50.86
went on a two-day tear after earnings, with shares up over 12% since the company reported its
Q4 2026 earnings on Sept. 23. The stock had been under pressure since hitting a 52-week high in August, so it's possible that investors are responding favorably to better-than-feared news.
That's an important takeaway from the report. The headline numbers were solid, particularly in the area where it mattered the most. Adjusted earnings per share (EPS) of 99 cents blew away the consensus forecast for 17 cents per share by over 482%.
Adjusted EBITDA also climbed 11.4% to $62.1 million. Earnings growth goes hand in hand with stock price growth, so it explains some of the bullish sentiment. It was also the first report delivered under new CEO David Deno, who took the job in August 2026.
But the rally pushed CBRL above its consensus price target of $50.57. The sentiment of the 12 analysts tracked by MarketBeat is mixed, with four Hold and three Sell ratings tempering the five bullish calls.
Why the Bulls May Not Want to Get Carried Away
Cracker Barrel's earnings growth was truly impressive, and it's not a one-quarter phenomenon. The company has beaten expectations for four consecutive quarters and is back to posting positive EPS numbers.
But can it be sustained? Some of the earnings strength reflected non-recurring benefits. Specifically, the quarter included a $15 million tariff refund. After reinvesting $5.9 million, the net benefit was about $9.1 million. That's a meaningful lift for a quarter with $22.4 million in adjusted net income.
In a macroeconomic environment that includes sticky inflation, which increases the dining-out-the-home premium, Cracker Barrel will need to provide flawless execution. The company's fiscal 2027 outlook raises that bar. Management guided for comparable restaurant sales growth of 3% to 5% with pricing of about 3%.
To hit those numbers, restaurant traffic will have to turn flat to positive. That may be a big swing from a 6.1% decline in Q4.
The Top Line Still Has a Traffic Problem
Revenue for the quarter came in at $849.34 million, beating expectations of $834.57 million. The beat came even as Cracker Barrel reported that comparable store sales were down 2.1% in the quarter, fueled by a 6.1% slide in restaurant traffic.
However, a 4.4% price increase lifted the average check by 4.2%, cushioning the blow. Management also noted it was lapping a tougher prior-year quarter.
However, revenue was also lower on a year-over-year basis from the $868.01 million the company delivered in Q4 of its fiscal year 2025 (FY2025). For the full fiscal year, revenue was down 4.7% to $3.32 billion. Guidance for FY2027 calls for revenue of $3.325 billion to $3.4 billion. The midpoint sits slightly below analysts' expectations.
The company also made statements about continued pressure on lower-income consumers. That's in line with comments made by Darden Restaurants NYSE: DRI.
Cracker Barrel Is Controlling the Controllables
Cracker Barrel Old Country Store MarketRank™ Stock Analysis
- Overall MarketRank™
- 68th Percentile
- Analyst Rating
- Hold
- Upside/Downside
- 1.4% Downside
- Short Interest Level
- Bearish
- Dividend Strength
- Moderate
- News Sentiment
- 0.68

- Insider Trading
- N/A
- Proj. Earnings Growth
- 65.35%
See Full AnalysisThat's the overarching message from the company's Q4 report. Cracker Barrel management has listened to its customers and has responded in a way that's created measurably positive sentiment. Food taste and service scores rose by nearly 400 basis points. Google star ratings are near an all-time high. Hourly employee turnover fell 450 basis points.
The balance sheet is also cleaner. Total debt fell to $337.2 million from $484.6 million at the end of fiscal 2025, helped in part by a sale-leaseback that generated about $77 million for debt reduction. Management is guiding for an adjusted EBITDA of $180 million to $200 million in FY2027. That's up sharply from $147.7 million in FY2026.
But sentiment only goes so far with a stock that's up over 100% in 2026, even after a sharp pullback since CBRL hit a 52-week high in August. With a trailing price-to-earnings ratio well above the broader market, investors are already pricing in significant improvement, and the report was far from perfect.
Institutions own about 96% of the float, but buying activity has been tepid. Plus, short interest is over 23%, which is a signal that the stock likely has some downside risk that still needs to be washed out.
What the CBRL Chart Says About the Next Move
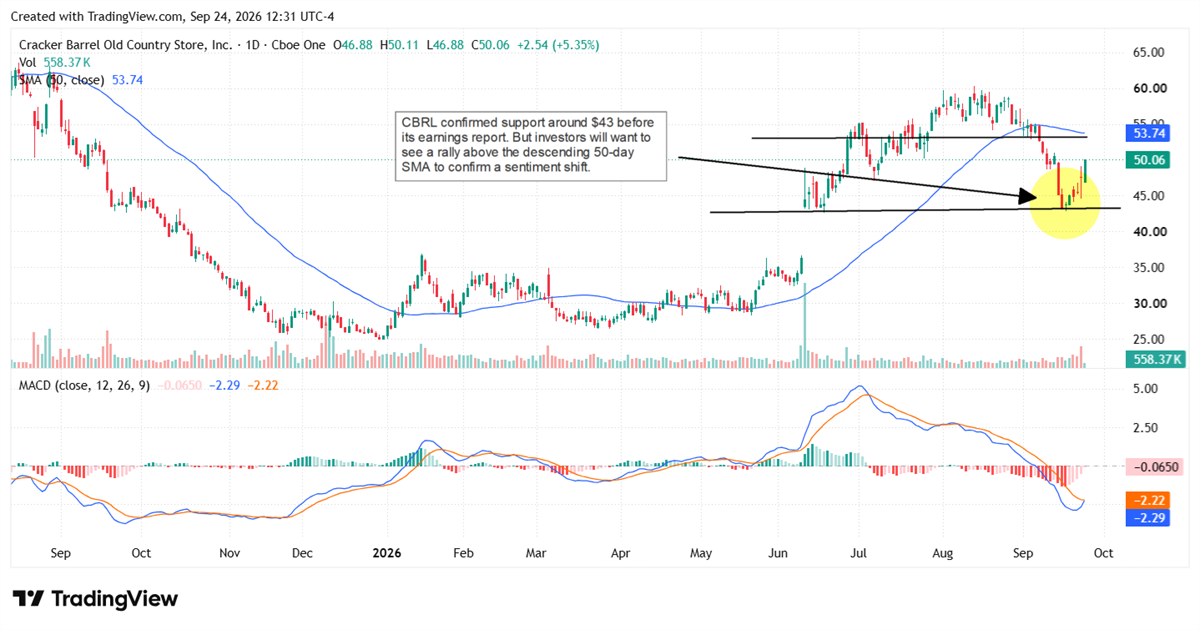
CBRL gapped up from about $36 to $44 in mid-June on the heaviest volume of the past year. The stock then ran to a 52-week high near $60 in August. The September pullback of roughly 28% stopped near $43. That's the top of the June gap, which acted as support.
The earnings pop lifted shares to about $50. But the stock remains below its 50-day simple moving average (SMA) of $53.74, which has started to roll over. That's the first line of resistance. Above it, bulls will need to clear congestion around $55 before retesting the $60 high.
Momentum is improving, but unconfirmed. The MACD line (-2.29) is on the verge of crossing above its signal line (-2.22). However, that crossover would happen deep in negative territory. Early-stage signals like this often fail without follow-through volume.
That's where the short interest becomes a wild card. A clean break above the 50-day SMA could force short sellers to cover, adding fuel to the rally. A failure there would put the $43-$45 support zone back in play.
Before you consider Cracker Barrel Old Country Store, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Cracker Barrel Old Country Store wasn't on the list.
While Cracker Barrel Old Country Store currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Tesla, Nvidia, and Google helped shape the last era of market growth, but the next wave could come from a new group of companies. Inside this report, you’ll find 7 stocks that could play a major role in the next tech-driven market boom.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
