Prediction markets have forced the gambling industry to take drastic action. While headlines often focus on Kalshi or PolyMarket users betting on politics or economics, more than 80% of activity still happens in sports markets, and that’s bad news for incumbent sportsbooks. Plus, prediction markets aren't just eating share; they also get preferential tax and legal treatment from the federal government, while traditional sports betting remains under the eye of state gambling commissions.
With the deck now stacked against them for a change, sportsbooks and casinos have been offering promotions to lure back wayward gamblers. And we aren’t just talking about the parlay boosts you see Kevin Hart hawking every Sunday. Gambling companies are spending millions of dollars on marketing and promotion, and as you might expect from a mature industry, the results are mixed. Flutter Entertainment PLC NYSE: FLUT, Las Vegas Sands Corp. NYSE: LVS, and Penn Entertainment Inc. NASDAQ: PENN each took a different approach to promotion, and their 2026 stock performance shows which strategy the market is rewarding.
Flutter Entertainment: Defending Market Share at Any Cost
Flutter Entertainment is the parent company of FanDuel, one of the two largest online sportsbooks in the U.S., alongside DraftKings Inc. NASDAQ: DKNG.
Flutter Entertainment Today
FLUT
Flutter Entertainment
$78.18 -1.60 (-2.01%) As of 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $73.50
▼
$255.26 - Price Target
- $144.70
FanDuel is the segment under the most pressure from prediction markets, and new CEO Dan Taylor is deliberately reinvesting in the platform through marketing and its own prediction-market buildout. Some of these initiatives are showing up in the numbers, and the results so far haven’t been pretty.
The fiscal Q2 2026 report showed revenue grew just 3% year over year (YOY), and the company reported a net loss of $296 million in the period. A 61% YOY increase in sales and marketing spend ate into profits, and adjusted EBITDA fell 45% from Q2 2025. The World Cup spiked user activity, but management doesn’t see it as sustainable and again reduced guidance for 2026 revenue and EBITDA. CEO Taylor expects continued marketing efforts to create a $270 million EBITDA drag for the remainder of the fiscal year.
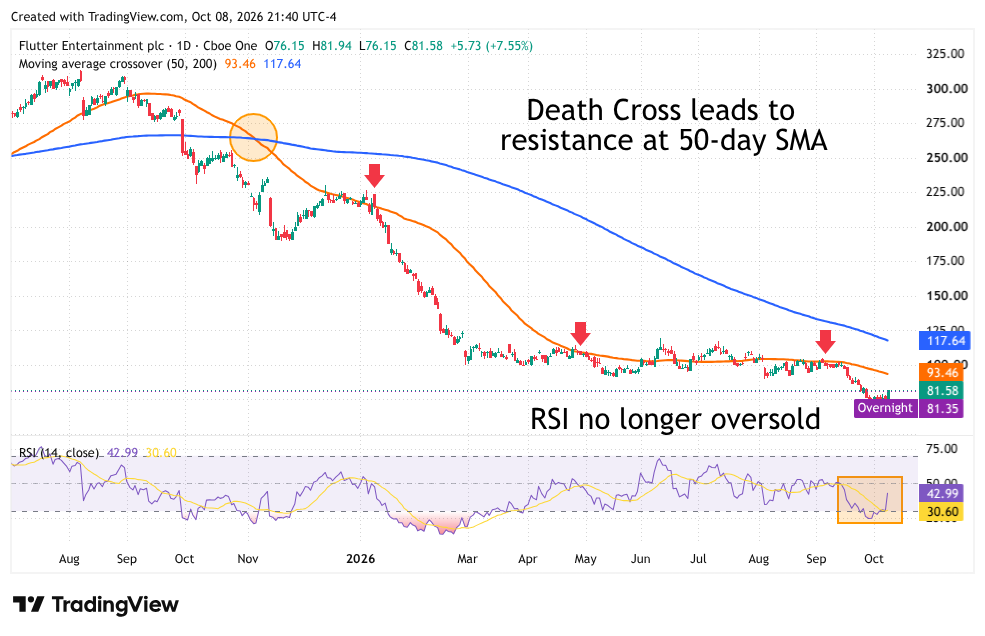
The World Cup happens once every four years, and this one-time boost goes away in Q3. The fiscal Q1 2026 report showed U.S. monthly players down 1%, and handle down 9%. The gambling ban in Brazil adds a $70 million revenue headwind, and the stock has hit new 2026 lows in recent weeks. The chart also flashes several bearish signals, including resistance at the 50-day moving average and a relative strength index (RSI) hovering between 30 and 50.
Las Vegas Sands: Retaining Share Without the Profit Gains
Las Vegas Sands has focused on reinvestment in Macau over the last year, with mixed success.
Las Vegas Sands Today
LVS
Las Vegas Sands
$36.13 -0.04 (-0.10%) As of 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $35.28
▼
$70.45 - Dividend Yield
- 3.32%
- P/E Ratio
- 14.06
- Price Target
- $60.16
Despite a top- and bottom-line miss in fiscal Q2 2026, Sands China's mass gross gaming revenue (GGR) grew 8% YOY (compared to 4% YOY for the overall market), and Marina Bay Sands in Singapore reported $689 million in EBITDA.
But management is working hard to retain clients, and it's getting increasingly expensive to keep them. Macau commissions and promotions topped 20% of GGR in Q2, the highest figure on record.
Q1 promotional spend was already up 28% YOY, and the company says this approach won’t change in the second half of fiscal 2026.
And while management does not provide guidance, it maintained its $700 million quarterly EBITDA target for Macau.
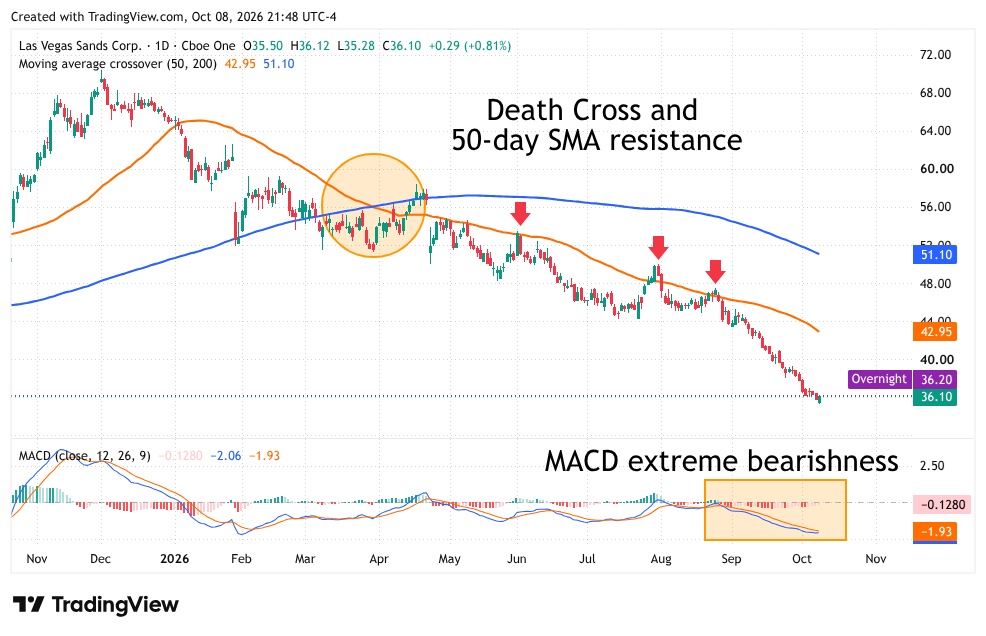
Despite LVS maintaining more share, the market hasn’t rewarded it. The stock is down more than 40% year-to-date (YTD), and the sell-off has intensified over the last month. A Death Cross created stiff resistance at the 50-day moving average, and now the MACD shows buying momentum has completely evaporated.
Penn Entertainment: Marketing Pullback Rewarded by the Market (Sort Of)
Penn Entertainment is the best-performing stock of the three so far in 2026. Despite a recent 20% drawdown, PENN shares are still up about 5% YTD, and the story here is more about what the company didn’t do.
PENN Entertainment Today
PENN
PENN Entertainment
$15.40 -0.08 (-0.52%) As of 04:00 PM Eastern
- 52-Week Range
- $11.65
▼
$22.36 - Price Target
- $24.06
Penn Entertainment exited its 10-year agreement with ESPN Bet in December 2025 and relaunched under its own moniker (theScore Bet). In the two months following the rebrand, interactive marketing spend dropped 65% while online sportsbook revenue doubled.
During the fiscal Q2 2026 conference call on Aug. 6, management raised its 2026 retail revenue guidance midpoint to $5.87 billion, citing expected margin growth in the second half of the year. In the online segment, adjusted EBITDA losses narrowed to $9.5 million from $62 million in Q2 2025. Handle is down 24%, but management says the customers leaving are promo-dependent, and it aims to attract more VIP-level clients. Most of Penn’s revenue still comes from its physical casinos. Still, the online losses have narrowed thanks to the marketing pullback, and the market currently sees that as a better value proposition than paying through the nose to retain clients.
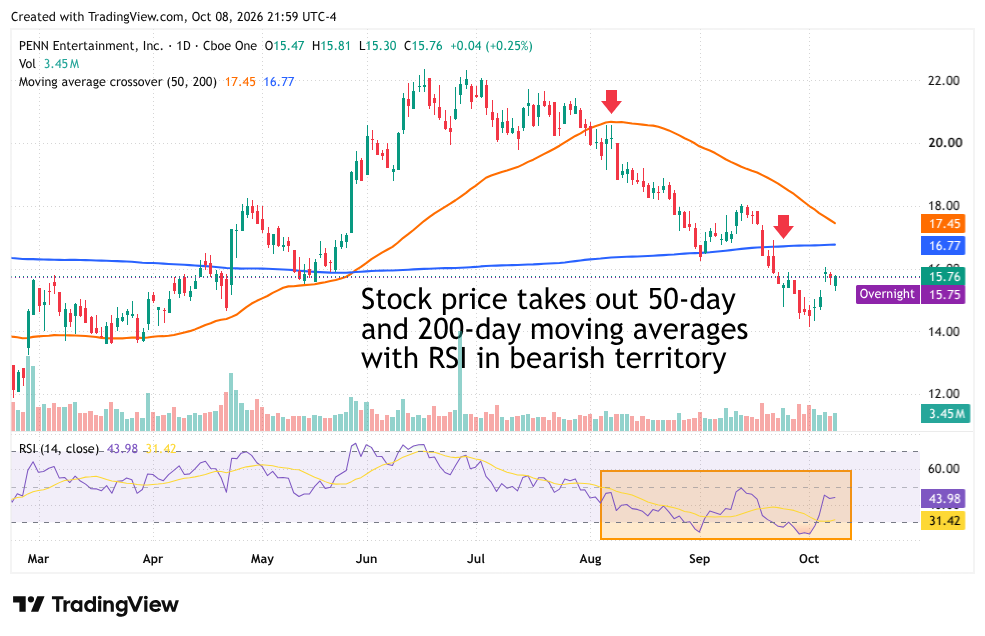
PENN shares have dipped more than 20% in the last three months, and the drawdown has pushed the price below the 50-day and 200-day moving averages. The RSI bounced off an oversold signal in the first week of October but remains below the bullish 50 threshold.
While PENN has been a winner in the gambling sector, it still lags far behind the S&P 500, and its digital business continues to shrink.
Getting leaner has limited losses, but this sector still needs evidence of growth before any of these stocks start beating the market again. Penn’s Q3 2026 conference call on Nov. 5 is the next potential catalyst; if the digital base stabilizes, it could prove that pulling back on promotions is the best way to operate.
Before you consider Flutter Entertainment, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Flutter Entertainment wasn't on the list.
While Flutter Entertainment currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Nuclear energy is entering a new growth cycle as rising power demand, expanding data centers, and renewed policy support bring the sector back into focus. After strong gains in recent years, the most impactful phase of nuclear investment may still be ahead. This report highlights seven nuclear energy stocks positioned across the value chain—combining near-term revenue with long-term upside as next-generation technologies scale. Click the link below to unlock the full list.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.

