Domino’s Pizza’s NASDAQ: DPZ Q3 report left something to be desired, but the market got it wrong and sold off in its wake. While near-term headwinds persist, the company is sustaining growth, expanding its footprint, and trading at a massive discount to historical norms.
Domino's Pizza Today
DPZ
Domino's Pizza
$304.29 +8.40 (+2.84%) As of 01:57 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $282.00
▼
$442.35 - Dividend Yield
- 2.62%
- P/E Ratio
- 16.76
- Price Target
- $380.87
Key factors for investors to consider are comp store numbers, central to the stock's weakness, and the root cause: consumer habits.
The company quickly pointed out that while ticket averages were down, traffic was up. Consumers are cutting costs, but turning to Domino’s more frequently, setting the stage for a robust acceleration when consumer habits shift.
Valuation is a critical element. At about 15x current-year earnings, Domino’s trades at a 40% discount to normal levels, pricing in persistent weakness and a slow growth trajectory.
As it stands, analyst consensus estimates point to annual earnings-per-share growth at a high single-digit pace over the next 5 years, supported by share buybacks.
Domino’s Pizza Outperforms in Q3
Domino’s Pizza struggled in Q3, as weaker consumer spending hurt overall results. That said, revenue grew 3.4% to $1.19 billion, narrowly beating MarketBeat’s consensus. Growth came from a 0.3% U.S. comp, a 4.39% increase in trailing 12-month store count, and a 3.2% gain in global retail sales.
Margins were also strong, with income from operations up 8.2%, net income up 9.25%, and GAAP earnings per share up 12%. GAAP earnings were boosted by aggressive share count reduction but don’t tell the whole story. More important are the improvements in operating and net income, which reflect the company’s optimization efforts. They include market basket price hikes for franchisees, as well as efficiency improvements and cost controls expected to be sustainable.
Guidance is a headwind for Q4 price action but aligns with the value opportunity. The company reduced its outlook for store count and profit growth, citing macroeconomic headwinds and a desire to help franchisees improve profitability, but expects to sustain growth, margin improvement, and expansion.
Domino’s Delivers Capital Returns, Dividend Growth Ahead
Capital returns are a catalyst for buyers, regardless of near-term headwinds. Dividends annualize to about 2.7% with shares trading at long-term lows; distributions are expected to increase annually, and buybacks are aggressive. Trailing 12-month activity reduced the count by nearly 3%, and the pace is expected to continue. With shares near long-term lows, the company could even accelerate the reduction and still lower expenses. Dividend growth is also expected to be robust; the company has sustained a high-teens CAGR over the last few years and pays about 40% of earnings.
Analysts responded cautiously following the earnings release, issuing numerous price target reductions because of the guidance cut. However, a major sentiment shift is not expected, with 32 tracked ratings pointing to a consensus Moderate Buy.
Price target reductions reflected some optimism despite the cuts, reaffirming a price floor near existing lows and the potential for a 30% rebound toward the consensus. The likely outcome is that DPZ continues to wallow near current lows, moving sideways until more news comes out.
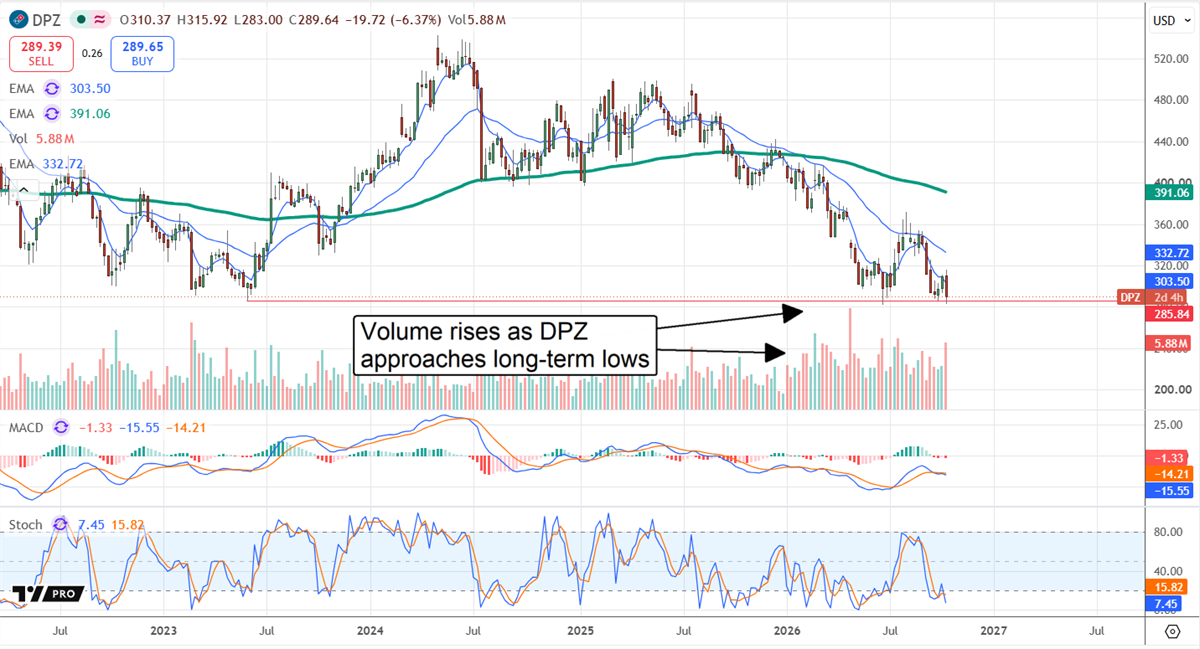
Market Volume Says DPZ Is Near Its Floor
Chart action shows that buying activity spiked when DPZ shares reached long-term lows, and institutional data suggests that institutions are the ones buying. Institutions own nearly 100% of this stock and bought on balance the first three quarters of the year, running a solid $2-to-$1 pace and underpinning the price bottom. They are likely to continue buying shares, given the cash flow and capacity for capital returns.
The market gets Domino's right in acknowledging that its growth trajectory has changed. Once a fast-growing enterprise, the company has matured, and now organic growth is harder to come by and is heavily influenced by consumer habits. This can create lumpiness, with consumer swings driving business and making capital returns more important than ever.
In this scenario, DPZ is a maturing fast-food operator suffering a macro strain, but it is also a high-quality compounder worth more than 15x its earnings. The question is what the business is worth, and industry comparisons are interesting. McDonald’s NYSE: MCD, the fast food king, trades at a premium to DPZ today and historically, suggesting at least a modest multiple expansion ahead.
Domino's moat is built on its franchise network. The company owns its own supply chain, providing products to its franchisees, and spends 4x more on advertising than its competitors. It not only has the reach but also the capacity to enforce and profit from aggressive marketing campaigns. To maintain its leadership position and drive a full price recovery, Domino's needs only to keep executing its strategy and patiently wait for consumer habits to shift.
Before you consider Domino's Pizza, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Domino's Pizza wasn't on the list.
While Domino's Pizza currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Discover the next wave of investment opportunities with our report, 7 Stocks That Will Be Magnificent in 2026. Explore companies poised to replicate the growth, innovation, and value creation of the tech giants dominating today's markets.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
