To see whether Novo Nordisk NYSE: NVO is closing the gap with competitor Eli Lilly NYSE: LLY in the GLP-1 market, investors need only look at patent-cliff timing and current market share. Eli Lilly commands a larger and growing market share and stands to keep exclusivity years longer than Novo. In this scenario, Novo has no option but to lose ground, which is why the long-term plan it laid out at its September Capital Markets Day failed to inspire investors.
Novo Nordisk A/S Today
NVO
Novo Nordisk A/S
$38.33 -0.25 (-0.65%) As of 12:16 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $35.12
▼
$64.16 - Dividend Yield
- 2.14%
- P/E Ratio
- 9.38
- Price Target
- $59.44
Novo's pipeline includes more than five drugs with "multi-blockbuster" potential by 2030, more than $23 billion in pipeline sales by 2035, and manufacturing capacity to treat 10 times more obesity patients on oral GLP-1s. The question is whether it can turn that pipeline into sales, and the outlook is dim, relatively speaking.
The signal for investors is that the plan promises only to sustain the business over time—an offset to looming GLP-1 weakness, not a driver of premium growth.
Since premium performance is no longer in the outlook, that means no more premium in the stock’s price.
With execs forecasting growth in line with industry trends, investors can expect the stock to wallow at its lows until a reason to buy emerges.
Is the Obesity Trade Over?
The obesity trade isn't over, but it has matured into a new era. The space is no longer a pure duopoly; competition is emerging, analysts are forecasting price erosion, and Novo’s own results reflect it. The risk for the company is disruption, and it needs a hit product just to retain its number two position. As it stands, the market is focusing on the winner, which is Eli Lilly at this time.
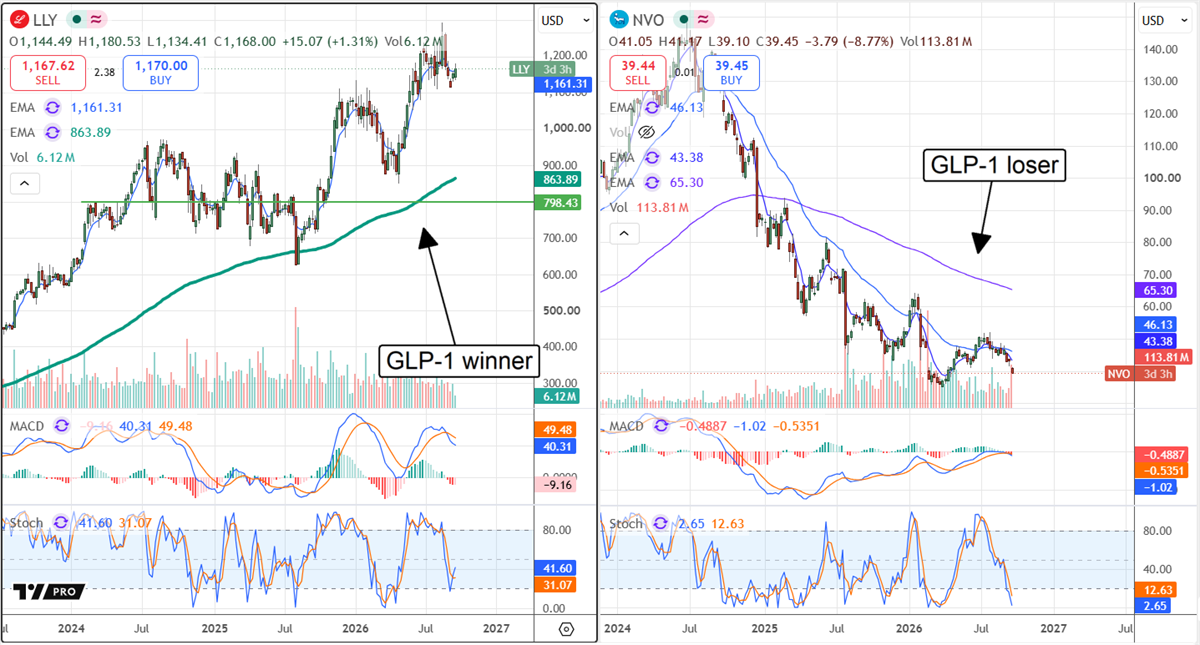
Novo Nordisk’s first-mover advantage is gone. Eli Lilly not only created a better molecule, with better results and tolerability, but also managed a flawless rollout and scaled to match demand. It outperforms Novo Nordisk’s drug in head-to-head trials, even while Novo struggles with capacity ramps, failing to capitalize on its position. Eli Lilly now commands more than 60% of the market, outsells Novo Nordisk by more than two to one, and has a prettier pipeline.
Eli Lilly’s pipeline is massive, funded by its still-growing GLP-1 cash haul. GLP-1 candidates include a triple agonist, compared with its current double-agonist and Novo Nordisk’s single-agonist approaches. It aims to reduce average weight by up to 25%, cementing its leadership position for years to come.
Other candidates include numerous blockbuster-potential ones, such as Kisunla for Alzheimer’s and a once-weekly basal insulin solution for diabetics. If approved, that weekly insulin would revolutionize a niche in this market, disrupting another business where Novo Nordisk has a first-mover advantage.
Analysts' Trends Highlight the Opportunity … in Eli Lilly Shares
Analyst trends summarize the difference between these stocks, highlighting one to shed and the other to accumulate.
Eli Lilly and Company Stock Forecast Today
12-Month Stock Price Forecast:$1,313.4310.98% UpsideModerate BuyBased on 30 Analyst Ratings | Current Price | $1,183.51 |
|---|
| High Forecast | $1,600.00 |
|---|
| Average Forecast | $1,313.43 |
|---|
| Low Forecast | $900.00 |
|---|
Eli Lilly and Company Stock Forecast DetailsWhile sentiment for Novo Nordisk isn’t outright bearish, analyst coverage is deteriorating, with 18 covering it compared to 30 for LLY.
Novo's sentiment rating has fallen to Hold; a few Sells have been logged, and price targets are declining.The consensus price target still forecasts solid upside, but the trend matters—and it has pushed NVO shares to the range's low end in late September.
The risk now is that analysts' trends continue to sour, leading this market to lower lows.
Eli Lilly analysts, on the other hand, rate LLY as a Moderate Buy by consensus with strengthening conviction.
MarketBeat tracks 30 analysts rating the stock; the data shows an 86% Buy-side bias, and price targets are rising.
Consensus offers only modest upside, but again, the trend matters—and it leads to the high end of the range, more than 22% above the late-September consensus.
The likely outcome is that analysts will remain bullish on this stock into 2027, underpinning its uptrend and keeping pressure on NVO.
CagriSema Could Be Novo Nordisk’s Next Major Catalyst
Novo Nordisk’s next catalyst is coming soon. The company expects regulatory approval of CagriSema, a next-generation combination weight-loss treatment. It targets the dual-mechanism advantage, focusing on amylin analogs to assist with feelings of fullness. The hope is to break the weight-loss plateau many GLP-1 users experience.
If successful, it could help Novo retain its position in the weight-loss market, potentially driving outperformance and improved market sentiment in the coming quarters. What the market may be getting wrong is the impact of CagriSema on the patent cliff; it's based on Wegovy but combines it in a new way, extending the revenue runway for many years. The approval decision is expected in Q4 this year.
Aside from lost market share, Novo's biggest risk is a growing number of lawsuits tied to its GLP-1 agonist. They allege severe gastrointestinal side effects and failure to report, which could hamper business moving forward. If the allegations prove true, users will likely flock to Eli Lilly’s solution or another competitor's, driving the business into decline.
Before you consider Novo Nordisk A/S, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Novo Nordisk A/S wasn't on the list.
While Novo Nordisk A/S currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
AI spending is reshaping the market, and the opportunity extends far beyond the biggest chipmakers. Discover 10 stocks set to benefit from powerful trends in AI infrastructure, cloud computing, energy, capital returns, and consumer growth this fall.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
