Fastenal NASDAQ: FAST had a good Q3, but raised concerns about margin compression. Investors should not get this wrong: the slim gross margin contraction is primarily due to customer mix, with some additional price-cost pressure, and is offset by several factors. Operating margin and profitability improved, keeping the capital return outlook unchanged, which matters most. Fastenal isn’t a flashy name or high-growth company; it's a nuts-and-bolts (literally) play on economic activity, producing healthy cash flow that it focuses on returning to shareholders.
Fastenal Today
$50.34 -1.66 (-3.20%) As of 01:09 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $38.97
▼
$52.92 - Dividend Yield
- 2.07%
- P/E Ratio
- 42.67
- Price Target
- $50.83
The dividend payout ratio is relatively high, at about 88% of trailing earnings, but the company's strong balance sheet and cash flow help support the payment. Increases are a key factor, with the company achieving a double-digit compound annual growth rate that outpaces inflation. Within that, the company is also a Dividend Champion, with 26 consecutive years of dividend increases, a record that may appeal to long-term income investors.
Fastenal Grows, Outperforms, Momentum Present
Fastenal had a good quarter, reporting $.2.46 billion in Q3 revenue. The top line is up 15.5% from last year and beat consensus estimates by a slim margin. A 15.5% increase in daily sales drove the strength, underpinned by market share gains, penetration, and pricing. Fastenal breaks down sales in several ways, showing strength in all metrics this quarter. Direct materials sales grew by 18.6%, while indirect materials sales increased 14.3%. Manufacturing sales rose 17.2%, and non-manufacturing sales grew 12.3%. By customer category, contract sales increased 18.8%, while non-contract sales grew 7.8%.
Margin news is a mixed bag but ultimately favorable to investors. While product mix is impairing the top line, the company is widening its client base, growing its sales, and improving efficiency, which more than offsets the decline. Looking ahead, Q3 trends could persist into Q4, driving another solid quarter. Longer-term, analysts forecast earnings to grow at a low-double-digit to high-single-digit pace over the next five years.
Fastenal’s balance sheet reflects its strong position, with cash down but offset by higher receivables, total and current assets, and equity. Liabilities are also rising to support growth, driven by higher payables, but remain well-managed. Long-term debt is down, below 0.25x cash, and total liabilities are below 0.35x equity. In this scenario, the high valuation is a concern, but prices in the balance sheet health and capital return.
Analysts Respond With Price Target Increases
The initial analyst reaction includes a price target increase from Robert W. Baird, which raised its target to $60 from $59. The increase follows Fastenal's top- and bottom-line beats and strength across its business. Although consensus remains at Hold, and the average price target sits below the current share price, the recent increase reflects continued confidence in the company's outlook. Institutional data also shows support, with institutions owning more than 80% of the stock and buying on balance over the trailing 12 months.
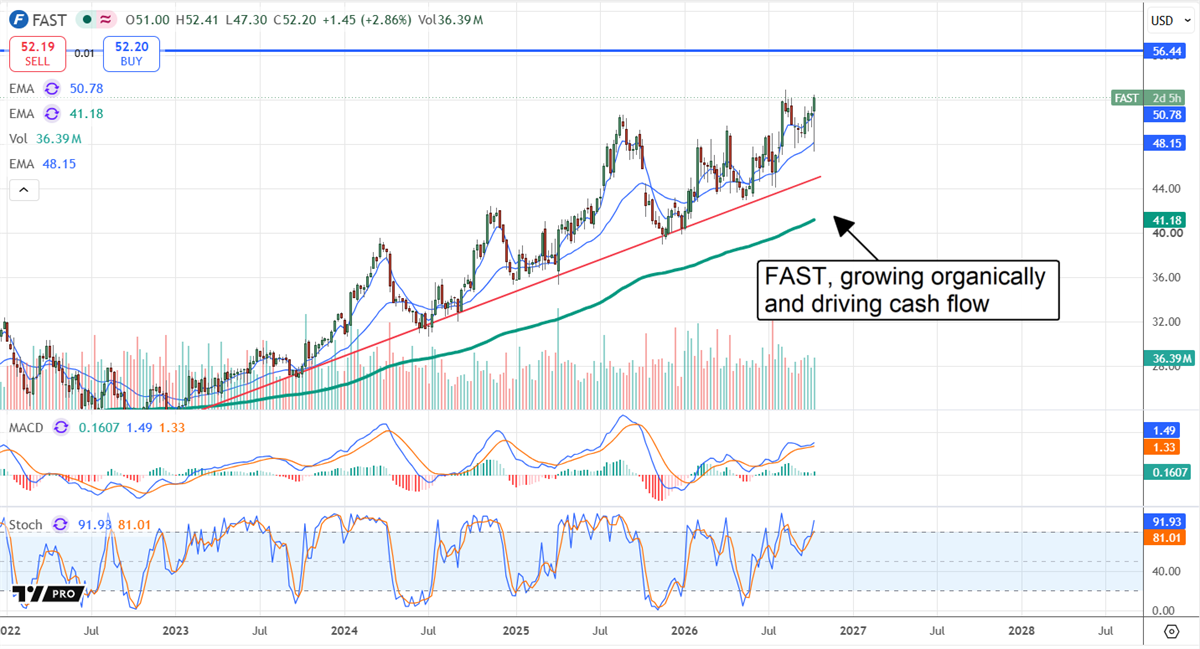
Price action is mixed but aligns with the trend. Shares initially dropped more than 5% following the release but hit support at the 30-day exponential moving average (EMA), triggering a buying spree and an intraday rebound. The signal suggests a trend-following entry point, with fresh all-time highs possible if bullish momentum continues. A sustained breakout above the previous high could open the door to further gains.
Fastenal MarketRank™ Stock Analysis
2.902336571275 of 5 stars- Overall MarketRank™
- 58th Percentile
- Analyst Rating
- Hold
- Upside/Downside
- 0.9% Downside
- Short Interest Level
- Healthy
- Dividend Strength
- Strong
- News Sentiment
- 0.42
- Insider Trading
- Selling Shares
- Proj. Earnings Growth
- 10.32%
See Full AnalysisFastenal’s biggest risk is cyclicality. Economic expansion supports its growth today, but economic downturns happen, and risks abound. The risk is slowing or sluggish growth or, worse, contraction, and downward pressure on capital returns. The offset is that the company’s balance sheet is a fortress, and cash flow can be diverted to sustain the dividend, although distribution cuts may still be needed.
Tailwinds include its centralized role in industrial supply chains, onshoring US capacity (across industries), and an expanding digital footprint. These factors drive steady growth, provide multiyear visibility, and support margins. Its moat lies in vendor lock-in; once its on-site vending and inventory management services are established, switching is costly and time-consuming. Again, when established, the on-site tools improve business efficiency and reduce costs, providing tangible benefits to Fastenal clients. If you doubt its strength, consider this: nearly all its growth is organic, with no acquisitions.
Before you consider Fastenal, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Fastenal wasn't on the list.
While Fastenal currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
MarketBeat just released its list of the 7 hottest IPOs expected to hit Wall Street in 2026. See which companies are preparing to go public and why investors are watching closely.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
