Kinder Morgan Today
KMI
Kinder Morgan
$34.47 +0.75 (+2.24%) As of 10/23/2026 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $25.60
▼
$34.81 - Dividend Yield
- 3.45%
- P/E Ratio
- 21.28
- Price Target
- $36.60
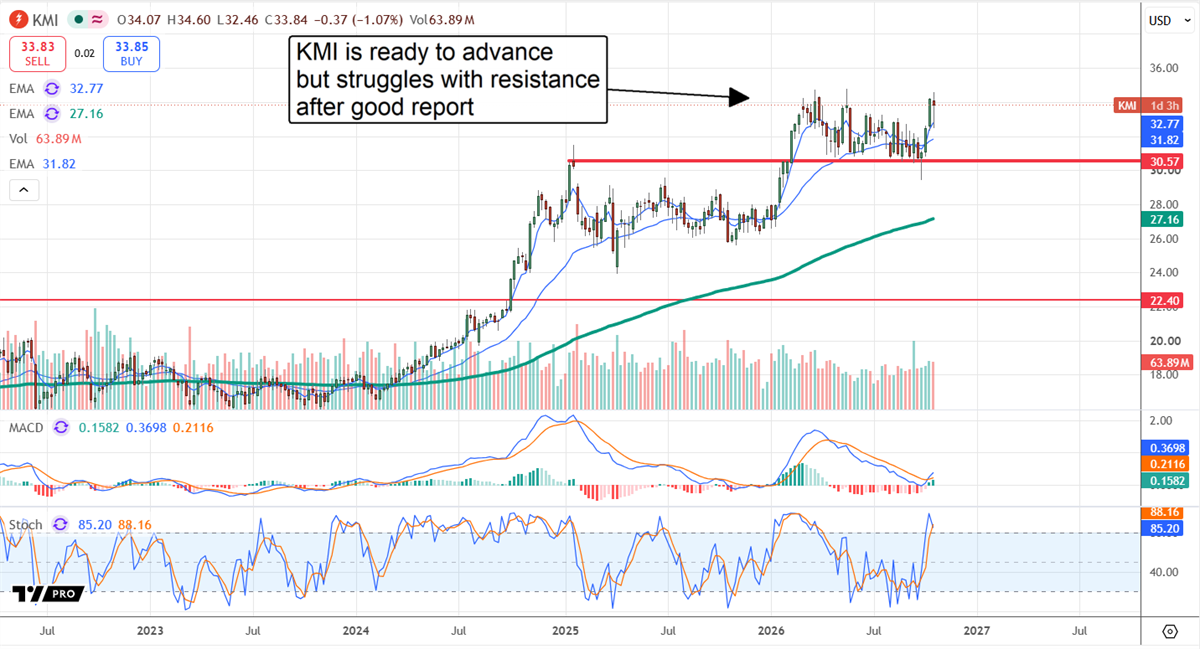
is a growing company with highly visible revenue and cash flow. While visibility can hinder stock price action by enabling the market to accurately price in the outlook, Kinder Morgan’s trends are bullish—this market is perpetually catching up with an improving outlook. Key details from the Q3 results include
monetizing prior investments alongside $4.7 billion in newly approved pipeline investments, representing its share of two joint ventures.
The takeaway is that Kinder Morgan, which primarily self-funds its growth, is adding two major natural gas pipelines to its network, backed by long-term distribution agreements that cement its growth trajectory and visibly increase its long-term revenue-generating and cash-flow potential. Its stock price could follow. Both projects are expected to begin service in 2030, subject to regulatory approvals.
Analysts are generally supportive of this thesis. Recent activity has included reaffirmed ratings and price-target increases, strengthening the trend. While consensus forecasts only modest upside from recent share prices, it forecasts a fresh high and is rising in 2026, while the high-end target implies double-digit upside. The likely outcome is that Kinder Morgan continues expanding its network, growing sales volume and revenue, keeping analysts and KMI investors in a bullish posture long-term.
Kinder Morgan Outperforms: Dividend Increases Are Coming
Kinder Morgan had a good Q3, with revenue up 9.3% to $4.53 billion, beating analysts' estimates by approximately 3.7%. Strength was underpinned by capacity expansion and demand, specifically for natural gas, driven by power generation, industrial, and export demand. More importantly, the strength helped drive systemic leverage, enabling accelerated earnings growth in nearly all comparisons. Adjusted EBITDA grew 9%, trailing revenue slightly, but a 22% increase in net income and 21% growth in both GAAP and adjusted earnings per share (EPS) helped offset that, along with an improving outlook for capital returns.
Kinder Morgan Dividend Payments
- Dividend Yield
- 3.45%
- Annual Dividend
- $1.19
- Dividend Increase Track Record
- 9 Years
- Annualized 5-Year Dividend Growth
- 2.38%
- Dividend Payout Ratio
- 73.46%
- Upcoming Ex-Dividend Date
- Nov. 2
KMI Dividend HistoryKinder Morgan did not adjust its 2026 budget but raised expectations for how far results will exceed it, including adjusted EBITDA by more than 6% and adjusted EPS by more than 13%. This leaves the company in better shape than expected, with excess cash flow after paying dividends and capital expenditures. Investors should not get dividend safety wrong, which sometimes looks strained relative to actual EPS. The company is a cash-flow machine, paying dividends with a focus on cash flow and targeting sustainable annual increases with ample cash-flow coverage. During the first nine months of 2026, operating cash flow was more than twice the amount paid in dividends, while dividends consumed about 90% of free cash flow after capital expenditures. The yield is around 3.5% as of late October.
Institutions may provide a headwind in Q4. The group provides a solid support base, owning about 63% of the shares and accumulating over the past year, although some institutions have reported reduced holdings in recent filings. Those filings do not establish that the selling occurred immediately before earnings. Renewed institutional selling could reinforce signs of market resistance and could keep this market from advancing if distribution persists. The question is whether the Q3 results can prompt them to adopt a more bullish posture, and the odds are high that they can.
Kinder Morgan Helps Unstick AI Bottleneck
The market should not overlook the nature of the new projects. One is in the Southeast, one of the nation's fastest-growing demand centers, while the other targets power generation serving data centers. It will take natural gas from the Permian Basin north toward the Texas Panhandle to support new electricity generation.
While the customer has not been publicly named, Kinder Morgan described it as an A-listed hyperscaler. That is important because natural gas connections can help address power-grid constraints by supplying fuel for dedicated power generation, potentially including fuel cells from companies such as Bloom Energy NYSE: BE. However, Kinder Morgan has not disclosed the customer's generation technology. The new pipeline is a big deal, not only for KMI but also for the AI and data center industry—existing and new projects will focus on locations where power and/or gas infrastructure exists.
Investors should not misinterpret visibility as a no-growth environment. While visibility means significant surprises are unlikely and big gains get priced in quickly, a slow-growth environment can still drive value. In this scenario, KMI shares can trend higher over time, providing a dual tailwind for portfolio growth, as they have over the last few years. The caveat is that share price appreciation may come in fits and starts, as it has over the past few years, with price surges followed by prolonged consolidations.
Kinder Morgan’s risks are operational, execution, and regulatory. Operationally, it faces high maintenance costs, litigation, and third-party damage to its infrastructure. Execution risks are tied to project timelines and completions, including costs and budgets. Regulatory risk is critical, as regulators have the final say on whether projects get the go-ahead. Both newly announced projects are awaiting final regulatory approval.
Before you consider Kinder Morgan, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Kinder Morgan wasn't on the list.
While Kinder Morgan currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
The space race is growing fast, and you don’t have to have gotten in early on SpaceX to profit. This report shows seven space stocks you can buy today that may grow as rockets, satellites, defense, space internet, and new space technology become more important.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.

