ManpowerGroup NYSE: MAN triggered a 16% decline in its stock price when it released Q3 results, creating a solid entry point for long-term investors.
ManpowerGroup Today
MAN
ManpowerGroup
$41.48 -2.27 (-5.18%) As of 10/16/2026 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $25.15
▼
$63.88 - Dividend Yield
- 3.47%
- P/E Ratio
- 16.39
- Price Target
- $51.88
The company is in the midst of turnaround efforts, revealed core strengths, and the “bad” news wasn’t exactly unexpected, merely poorly timed. Among the factors that impaired price action was the surprise revelation that a longtime insider and current Chief Strategy Officer would take over as CEO.
The board has indicated the transition as a natural course of business, and Becky Frankiewicz is the logical choice to lead the next business phase. The news was poorly timed because it came alongside visible impacts of turnaround efforts, i.e., rising costs and a significant variance between GAAP and adjusted earnings. The critical detail is that the company is positioning itself for sustainable growth and wider margins, and will begin to see the positive impacts of cost-cutting, efficiency improvements, and higher-margin revenue streams next year.
ManpowerGroup Has a Capital Return Catalyst Waiting to Be Unleashed
ManpowerGroup is a cash flow machine, capable of sustaining a solid dividend and aggressive share buybacks. Although buybacks are effectively paused during the company's financial turnaround, they will likely resume at the prior pace within the next year or so. Historically, the count has declined by 3.5% to 4.5% annually, providing significant leverage for share prices and earnings growth.
The dividend offers a reason to buy. Cut in 2025 alongside the buyback, the payout yields 3.5% with shares near long-term lows and is on track for robust increases. The caveat is that dividend increases will be tied to margin improvements expected in the coming year, leaving the market in limbo as it waits for better news.
ManpowerGroup Grows in Q3, Margins Widen
ManpowerGroup didn’t have a bad Q3, just one with headwinds and uncertainty. Revenue rose to $4.8 billion, up 4.4% year over year (YOY), but fell short of consensus by a slim margin. Growth was supported by expansion across all segments, with 6% systemwide organic growth, currency-neutral.
Currency is a factor in the margin details, but not the only headwind, as restructuring costs also play a role. The key is that spotty weaknesses are improving, are offset by strengths, and systemwide results show progress. While gross margin contracted by 20 basis points, SG&A improved, leaving operating income up by 23.7%, GAAP net income up by 89%, and adjusted earnings per share at $1.01, up 24% YOY and as expected despite the top-line miss. The bad news is that earnings per share (EPS) fell short of expectations, fueling investor anxiety.
Q4 guidance is a headwind for price action, with the EPS forecast below consensus, but the same caveats apply: the company is investing in its future and positioning for better performance next year. The question isn’t so much about what the company is spending today as about the long-term impact on operations. Execs target $200 million in operational savings by 2028, bolstering the outlook for improved capital returns over the next two to three years.
Manpower’s Major Catalyst? Improved Hiring Trends
Business improvements are good despite hiring trends being as tepid as they are. Labor market data doesn’t reflect a downturn, but employers aren’t hiring robustly, merely holding on to the employees they have while they wait out rising oil prices, inflation, and interest rates. The International Monetary Fund estimates a broad-based acceleration in employment in mid-to-late 2027, driven by non-tech, cyclical industries and the effects of this year’s balance sheet strengthening.
Analyst trends reflect a cautious stance, with only nine analysts tracked and the consensus rating at Hold. However, no Sell ratings are logged.
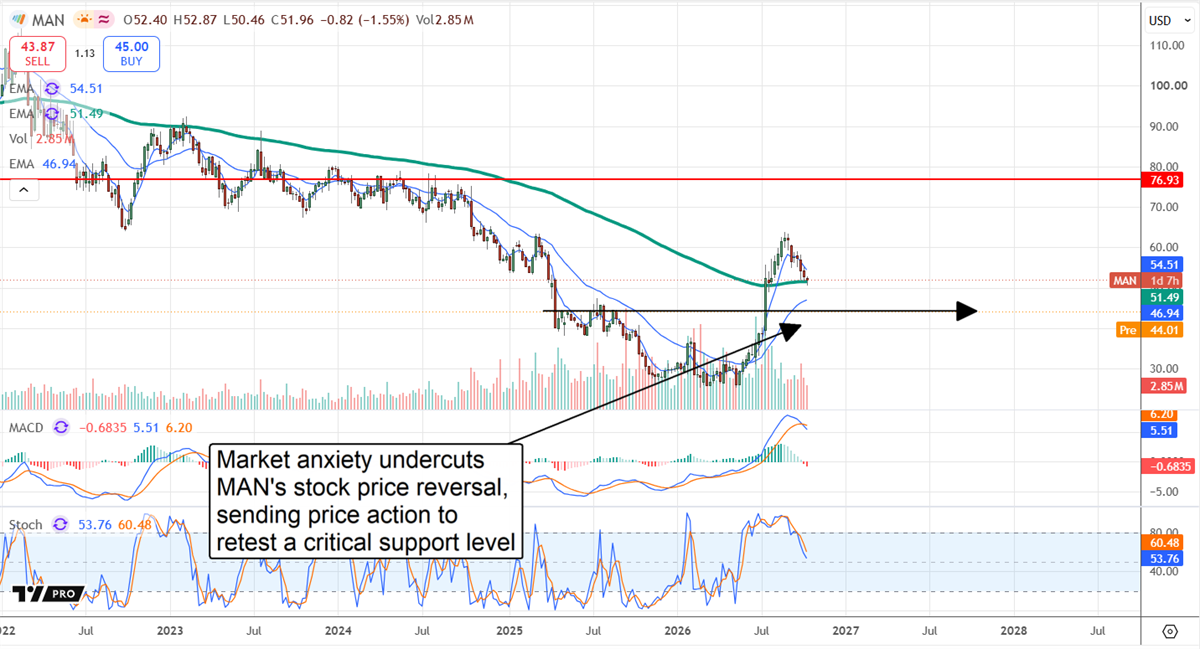
Institutions reflect a high degree of confidence, owning more than 98% of the shares and buying in late 2026. They underpin the stock price bottom seen in the charts and are likely to buy the dip in Q4, given the deep discount and potential for turnaround efforts to gain traction in upcoming quarters.
This year’s catalysts include platform upgrades, technological advancements, and shifts toward higher-margin business. The company is integrating AI and agentic tools into its platform, while also focusing on more specialized talent. Experis connects employers with in-demand IT employees while Talent Solutions provides end-to-end, data-driven strategies across the employee cycle.
What the market gets wrong today is thinking economic headwinds and staffing headwinds will last forever. In this scenario, the market is pricing the stock as if there is no recovery ahead, pushing it to 19x earnings, a 50% discount to cyclical highs.
Before you consider ManpowerGroup, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and ManpowerGroup wasn't on the list.
While ManpowerGroup currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
The AI wave will soon hit public markets with Anthropic and OpenAI set to go public later this year. However, you don't have to wait to invest. This report shows seven AI stocks that you can buy today while the big model providers get ready to go public.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
