Investors watching Cintas NASDAQ: CTAS and wondering where the stock price may go next need to focus on its durable growth and unmatched capital returns. They, alongside fundamentally bullish market conditions, market-leading performance, and analysts, say this stock can reach new highs, potentially before the year’s end.
The backdrop is a still-expanding labor market, which matters because Cintas's uniform and facility-services revenue grows with its customers' headcount. Labor market strength cooled over the past two years, but did not evaporate.
Cintas Today
$199.77 +2.09 (+1.06%) As of 09:42 AM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $161.16
▼
$219.16 - Dividend Yield
- 1.04%
- P/E Ratio
- 38.99
- Price Target
- $214.00
The key takeaway from the labor market data is that it normalized after the COVID-19 economic disruption and is at historically strong levels. At face value, labor markets are “weak” because jobs aren’t growing as fast as they did in the wake of COVID-19. Fundamentally, though, they are as strong as they’ve been, adjusting for the impact of a forced holiday, trillions in stimulus spending, the subsequent rebound, and the supply-chain snafus it all caused.
The story in 2026 is that headcount is expanding, albeit moderately, and that the trend is expected to continue as the year progresses, driven in large part by AI and the data center buildout. While some fear the AI-driven hiring boost will be short-lived, data center buildouts take years, the industry is still in its early stages, and AI is not the only driver of labor market growth. In this environment, Cintas is positioned for several more years of strength, and the market will soon price it in.
Cintas Beats on Earnings, Raises Guidance
Cintas posted a solid quarter, showing the durability of its model and the strength of its cash flow. Revenue grew 10.9% to just over $3 billion, slightly better than expected, supported by an 8.9% organic increase.
Growth was broad-based, with Uniform Rental and Facility Services revenue up 9.7%, First Aid and Safety Services up 16.1%, and All Other—which includes Fire Protection Services and Uniform Direct Sale—up 13.1%.
Margin was another strength. The company leveraged its acquisitions effectively, integrating costs while expanding its territories, increasing its client count, and driving cross-selling opportunities. The net result in the last quarter was a 120 basis point (bps) improvement in the gross margin that carried through to a 90 bps improvement in adjusted operating margin. Key details include accelerated operating, net, and adjusted earnings per share (EPS) growth, with adjusted EPS up by 15.8% year-over-year (YOY) and 4 cents better than expected.
Guidance is yet another catalyst for this cash cow, as management improved its outlook for full-year revenue and earnings, expecting strengths to persist and potentially underestimating the tailwinds. The revenue range was lifted at the low and high ends and narrowed, leaving the midpoint and earnings targets above consensus forecasts. The likely outcome is that Cintas continues to execute and outperforms guidance.
Cintas’ Dividends and Buybacks Keep Compounding Returns
Cintas’ stock price faced many hurdles over the past year, including labor market normalization and a stock split, but the headwinds are clearing, leaving the capital returns to do their work. Cintas targets cash flow for dividends and share buybacks, which attract strong institutional interest, reduce volatility, and provide shareholders with quarterly leverage.
The dividend distribution is worth about 1.1%, not much, but enough, and it is compounded by share count reduction. Trailing 12-month buyback activity reduced the count by about 1.2%, a pace expected to continue in upcoming quarters.
One risk is that distribution growth will slow, but given the company’s 33-year history of increases and strong financial metrics, this is unlikely. The payout ratio is low, well below 60%, and dividend increases are offset by lower share counts; earnings growth also mitigates distribution risk. Cintas is not only improving its outlook for this year, but analysts also forecast low double-digit earnings growth to continue for many years.
UniFirst Deal Could Be the Catalyst That Sends Cintas Higher
One catalyst is UniFirst NYSE: UNF. The two have a definitive agreement to merge and are waiting only on FTC approval. The deal is expected to close at any time and will trigger a revaluation of the stock price. In this scenario, CTAS revenue grows by 20% overnight, margins improve almost immediately, and cash flow capacity improves significantly.
Institutional and analyst trends reflect confidence in Cintas’s long-term outlook. Fifteen analysts tracked by MarketBeat rate the stock as a consensus Moderate Buy with approximately 9% upside relative to the critical support target, and the price target rose in Q3 after a period of reductions. The takeaway is that one headwind has been removed from the price action, and institutional data suggests a tailwind is already in place. Institutions own more than 60% of the stock, accumulated throughout early 2026, and ramped up activity in early Q3, helping to lift the stock price off of its long-term lows.
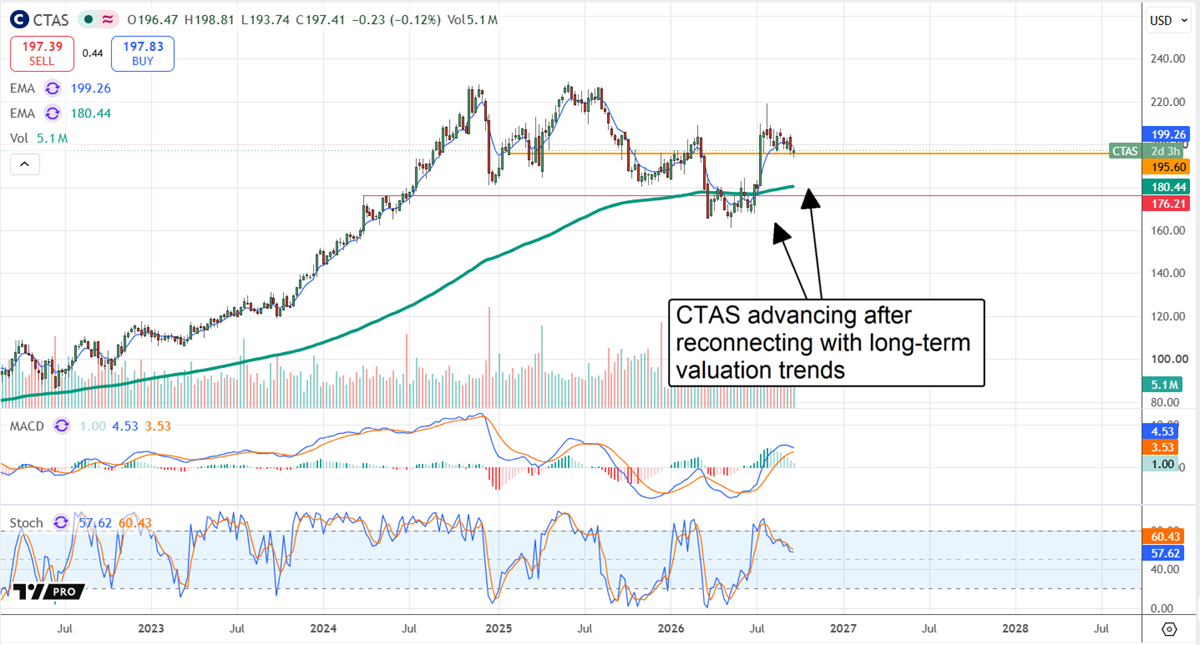
Cintas's price action shows the impact of headwinds, but also a market reconnecting with its trend and rebounding. The key detail is that Q3 activity shows solid support at the long-term exponential moving average (EMA) and the potential to continue advancing, possibly to the existing high by year’s end. Longer-term, Cintas' move to new highs is all but assured, needing only time, cash flow, and capital returns to get there.
Before you consider Cintas, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Cintas wasn't on the list.
While Cintas currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Discover the 10 Best High-Yield Dividend Stocks for 2026 and secure reliable income in uncertain markets. Download the report now to identify top dividend payers and avoid common yield traps.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
