Navan Inc. NASDAQ: NAVN wouldn’t be the first company investors would think of as a target of the recent sell-off of artificial intelligence names. But that may be part of the trouble facing NAVN after the company’s Q2 earnings report for its 2027 fiscal year.
Navan Today
$22.38 +1.01 (+4.71%) As of 02:16 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $8.10
▼
$30.88 - Price Target
- $30.50
That’s because in the case of Navan, a slowdown in AI growth would directly contradict the company’s current growth initiatives. The company is significantly increasing its AI spending, but investors are worried that its growth won’t keep pace.
Navan (formerly TripActions) is a corporate travel and expense management platform that bundles business travel booking, corporate cards, expense reporting, and now meetings and events into one AI-powered system. It competes against fragmented, legacy point solutions in that market, such as SAP Concur and American Express Global Business Travel (Amex GBT).
Navan Delivered a Strong Quarter
NAVN is down over 15% since the earnings report. That’s despite impressive headline numbers. Quarterly revenue was up 35% year over year (YOY) to $233 million. Perhaps more significantly, the company reported its third consecutive quarter of positive earnings on a non-GAAP basis.
Both numbers exceeded analysts’ expectations. The company also raised its full-year guidance for both revenue (32% at the midpoint) and non-GAAP income (a 9% margin).
That would normally be enough to push the stock higher, but that wasn’t the case. The concern is the execution of its AI strategy. Navan reported that its AI support agent, Ava, handled roughly 60% of the company’s customer interactions in Q2. Plus, over 50% of Ava calls ran on Navan’s own models, up from 30% in Q1.
But at what cost? Navan reported a 46% increase in operating expenses, which can be attributed to the company’s AI growth. That sets up the contradiction for investors. Navan is a growing company in a resilient sector. But that growth is being fueled by AI, which creates an execution risk.
That execution risk got put into even sharper focus when the company announced an acquisition that adds another variable to the equation.
Will BoomPop Change the Momentum?
The same day Navan reported earnings, the company announced it had acquired BoomPop, an AI-powered platform for planning corporate meetings and events. Terms weren't disclosed.
The deal wasn’t a surprise, which may explain the muted market reaction. Navan and BoomPop partnered earlier this year, and BoomPop's technology was already integrated into Navan's events offering before the acquisition made the relationship permanent. It's a pattern the company has used before, most recently with its Smartrips deal in Latin America: partner first, prove out demand, then buy and fully integrate.
BoomPop brings a track record that fits Navan's consolidation pitch. The company says it has supported events for roughly 250,000 people at customers, including Accenture NYSE: ACN, Amazon NASDAQ: AMZN, Alphabet NASDAQ: GOOGL, Salesforce NYSE: CRM, and Shopify NASDAQ: SHOP, and estimates it has cut customers' event-booking costs by about 30% on average.
Management has pointed to meetings and events as a category in which most customer spend still occurs outside any managed platform. That’s the same space Navan has already targeted with travel and expense.
For investors, the question is timing. Navan said the acquisition is expected to have no material impact on guidance, which helps rule out BoomPop as the source of the expense growth that spooked the market.
But layering another integration onto a company already under scrutiny for rising costs explains why the post-earnings reaction ties into the AI spending debate. Will this be the kind of platform-building that pays off, or just another line item that investors have to trust management to convert into growth?
How to Consider NAVN Post-Earnings?
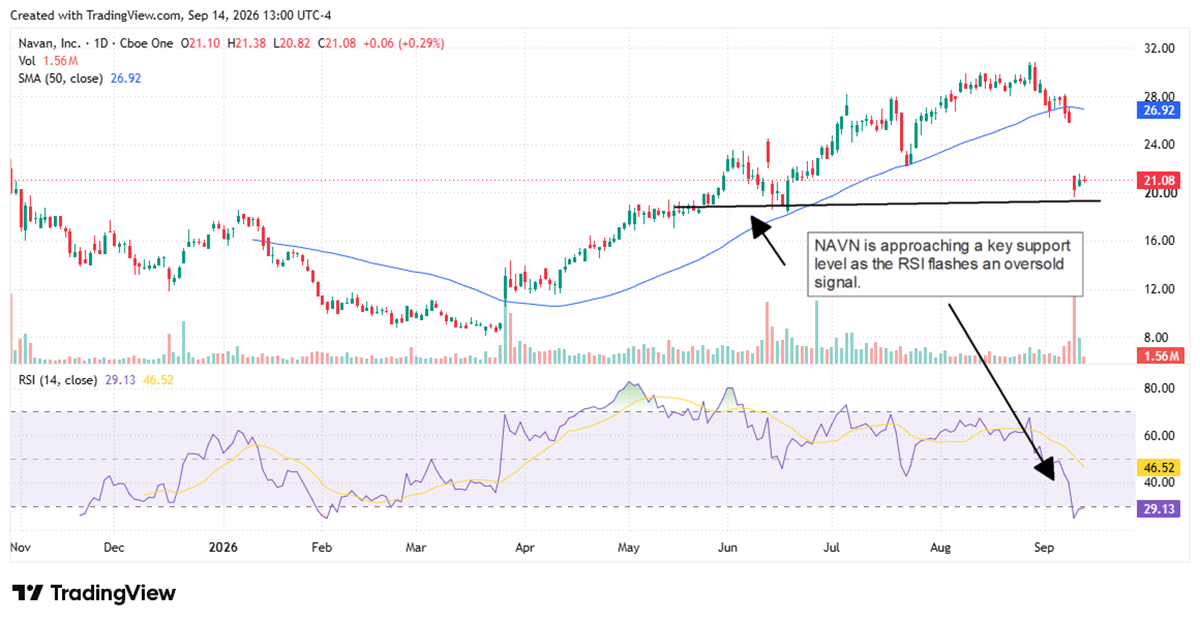
The gap down after the company’s earnings report has reversed nearly all the gains NAVN made over the summer. With negative sentiment surrounding AI, investors should watch a level around $18.30 as potential support.
At the same time, the relative strength indicator (RSI) has moved into oversold territory. While the RSI is not a perfect indicator, it can be a signal that bearish sentiment is overdone.
The Navan analyst forecasts on MarketBeat support a bullish outlook. From the 17 analysts tracked by MarketBeat, NAVN gets a consensus Moderate Buy rating with a $30.50 price target. That’s a gain of approximately 43% from recent prices.
On the other hand, short interest in NAVN, while only around 10%, has stayed higher than average in the last four quarters, which could keep some downward pressure on the stock.
Before you consider Navan, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Navan wasn't on the list.
While Navan currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
The AI wave will soon hit public markets with Anthropic and OpenAI set to go public later this year. However, you don't have to wait to invest. This report shows seven AI stocks that you can buy today while the big model providers get ready to go public.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
