NVIDIA Today
$152.11 -3.35 (-2.15%) As of 10:44 AM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $148.80
▼
$243.37 - Dividend Yield
- 0.66%
- P/E Ratio
- 19.21
- Price Target
- $266.88
NVIDIA’s NASDAQ: NVDA Q3 fiscal year 2027 (FY2027) earnings report, guidance, and conference call mark a turning point for AI investors. While fears and risks remain, the Huang Affair effectively ended AI’s speculation phase, and the Q3 results point to the next phase: execution. Execution means converting massive backlogs into cash flow, turning plans into data centers, and capitalizing on investments that, for NVIDIA, span its ecosystem and future revenue paths.
The primary takeaway from the release is momentum. NVIDIA’s results reflect momentum, as do the guidance and longer-term forecasts. As interim CEO Colette Kress pointed out, the long-term 2028 guidance is higher than the prior forecast on a larger base, representing a massive increase in the forward outlook sufficient to validate signals from other AI-critical companies.
Oracle NYSE: ORCL, Micron NASDAQ: MU, Astera Labs NASDAQ: ALAB, and Credo Technologies NASDAQ: CRDO are just a few companies indicating strength, with guidance forecasting acceleration over the next few quarters. More importantly, these companies are inflecting or on track to reach positive cash flow and profitability, perhaps the single most important factor for investors.
NVIDIA Signals Multi-Year Roadmap Intact: Vera Rubin Sales Are Ramping
NVIDIA’s Q3 results continued the trend, outperforming MarketBeat’s consensus estimates by several percentage points on strength in Data Centers and AI. The Data Center business led, growing more than 100% year over year (YOY), but it isn’t the only strength, as Edge Computing also posted solid growth of about 42%. Within this, Vera Rubin added nearly $20 billion in sequential revenue, representing the fastest product ramp in company history (since Blackwell).
As strong as the revenue is, margins and guidance are the market triggers. Margins improved, driving ample cash flow and balance sheet improvements to backstop NVIDIA’s investment and spending commitments. Guidance, including management commentary, reflects a steady, stable market in which customers remain committed to product cycles, with Q4 FY2027 revenue expected to grow nearly 91% YOY, ahead of consensus expectations, in addition to Q3 strength. Further out, Kress and team expect approximately 75% growth in fiscal 2028, up 5 percentage points from the prior forecast.
Board Signals Confidence, Shifting Focus With Buyback Authorization
Buyback plans are a signal for investors to watch, and they are strengthening along with the business. The board authorized an additional $150 billion in September, bringing the total available funds to over $225 billion, a sign of confidence in the cash flow. The $225 billion is a relatively small amount compared with NVIDIA’s market cap but sufficient to reduce the share count, and more repurchases are expected. Execs remain committed to focusing free cash flow on capital returns, net of investments, which some analysts forecast to slow. Speculation is that the company will slow its aggressive investment cycle, having secured its multi-year growth trajectory, and shift cash flow to capital returns, specifically buybacks.
Balance sheet and cash flow highlights support the thesis that buybacks will accelerate; cash is up nearly 3x year-to-date, and investments, receivables, inventory, current, and total assets are up, outpacing liabilities and driving equity, despite the business investments. Liabilities remain low relative to equity and cash flow, and cash flow is forecast to improve sequentially in fiscal 2028. Q3 operating cash flow topped $48 billion, leaving more than $43 billion in free cash flow after capital spending. Quarterly returns topped $28 billion, up more than 120% year over year, leaving ample cushion for future increases.
Initial analyst responses reflect cautious optimism and reinforce NVDA's upside potential. MarketBeat tracks a downgrade to Hold and a price target reduction, but the reduction is to near the consensus target, and a half dozen analysts reaffirmed ratings and targets to offset them. The read is that upside potential is diminished, but only slightly, with a consensus of 60 analysts pegged at Moderate Buy and forecasting about 70% upside as of mid-November.
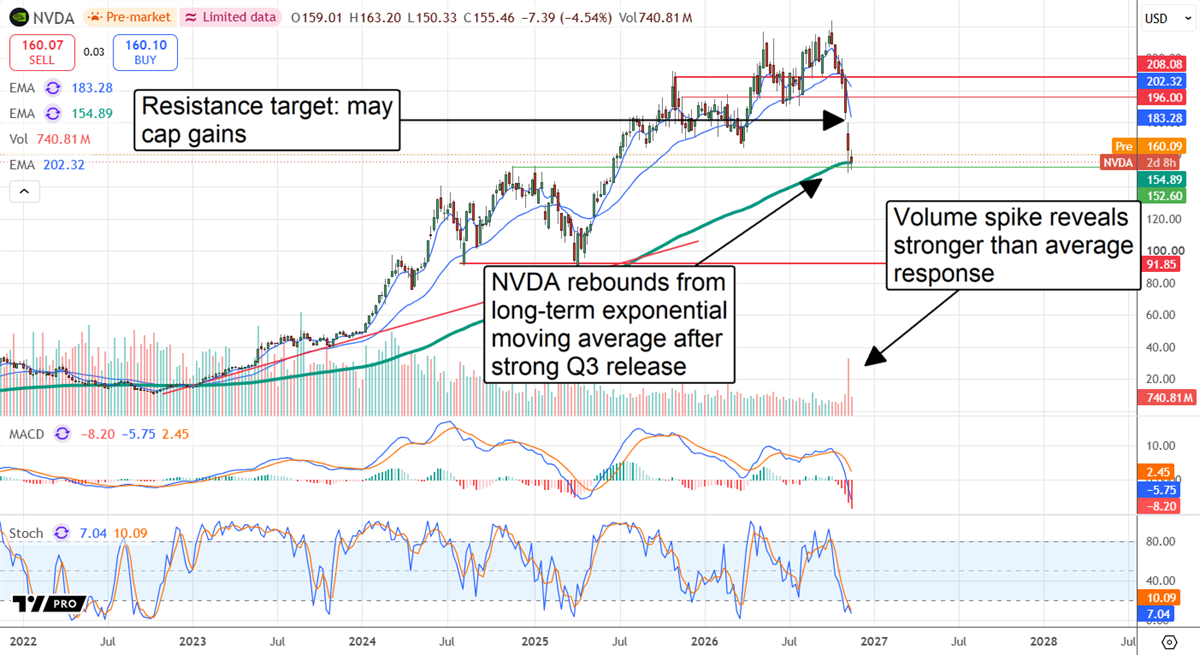
NVIDIA at Bottom? Signs Say Yes, Too Soon to Be Sure
NVIDIA’s price action suggests a potential bottom, with volume spiking as it hit closely watched technical levels and then rebounding afterward. The post-release price action suggests the rebound will continue, but near-, mid-, and long-term risks remain. The near-term risk is volatility; a rebound today may be followed by a sell-off tomorrow.
NVIDIA MarketRank™ Stock Analysis
4.918818206015 of 5 stars- Overall MarketRank™
- 98th Percentile
- Analyst Rating
- Moderate Buy
- Upside/Downside
- 74.3% Upside
- Short Interest Level
- Healthy
- Dividend Strength
- Weak
- News Sentiment
- -0.04
- Insider Trading
- Selling Shares
- Proj. Earnings Growth
- 68.43%
See Full AnalysisInvestors who want to avoid this risk can wait for the follow-on signal, which is likely, given the fundamentals, and expected in generally accepted technical trading theory. That could come soon, but it may take time to develop; the mid-term risk is that more bad news emerges and keeps NVIDIA shares volatile for an extended period.
NVIDIA’s long-term risk lies in its executive transition. Although some investors are calling for Huang’s return, the board’s signals suggest it won’t happen. The market needs to see a clear transition to a respected and capable CEO who can execute the roadmap Huang created.
The trading risk is that NVIDIA’s stock price could fall by more than 30%. It creates significant overhang that may cap future gains. However, valuation metrics suggest NVIDIA stock is deeply undervalued, pricing in deterioration and implosion rather than the acceleration indicated by Q3 results. Trading in the mid-teens relative to current-year forecasts, NVIDIA can rise by 50% in the near term and still be discounted relative to its historical premium; trading in the low single digits relative to the 10-year outlook, NVIDIA’s stock price could rise by several hundred percentage points if the company successfully executes its plans.
Before you consider NVIDIA, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and NVIDIA wasn't on the list.
While NVIDIA currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
The space race is growing fast, and you don’t have to have gotten in early on SpaceX to profit. This report shows seven space stocks you can buy today that may grow as rockets, satellites, defense, space internet, and new space technology become more important.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
