Investors looking at NXP Semiconductors’ NASDAQ: NXPI "weak" Q4 guidance and subsequent stock price decline, thinking now might be a good time to get out, are getting it all wrong. Wall Street set the bar so high that guidance calling for 15% year-over-year revenue growth is being treated as a disappointment.
NXP Semiconductors Today
NXPI
NXP Semiconductors
$266.00 +14.31 (+5.69%) As of 04:00 PM Eastern
- 52-Week Range
- $183.00
▼
$339.95 - Dividend Yield
- 1.53%
- P/E Ratio
- 19.94
- Price Target
- $295.78
Since NXP Semiconductors' last earnings report in July, nearly every analyst revision has been bullish, with commentary focused on the AI buildout, NXP’s position in NVIDIA’s NASDAQ: NVDA ecosystem, and the firm's long-term growth potential.
The mixed Q4 outlook overshadows the company’s strengths, pushing the stock down and creating a buying opportunity in a highly profitable, capital-returning machine.
Highlights from the Q3 release included significantly wider margins, accelerated earnings growth, ample free cash flow, and a $5 billion increase in the share buyback authorization. The increase reflects the board’s confidence in cash flow and sets the stage for sustained share count reduction. NXP Semiconductors doesn’t buy shares aggressively. Instead, it steadily reduces its share count each quarter. The net result is steadily improving shareholder leverage and equity, a dual lever for stock price advances.
NXP’s Strong Q3 Overshadowed by Mixed Q4 Guidance
NXP Semiconductors posted a strong quarter, with revenue up 19.3% to $3.79 billion, beating consensus by a slim margin. Revenue rose 8% sequentially, supported by growth in all but one segment.
Communications, which includes data center business, led with a 54% advance, while Industrial/IoT advanced 39% and Automotive 13%. Mobile was the single weakness, down 4%, but it could have been worse. The mobile business is struggling industry-wide, with carriers shifting away from the subsidies that supported device sales and supply chain issues compounding the problem.
Margin news would have been a catalyst for share prices if not for the guidance issue. Margins expanded at the gross and operating levels, driving accelerated earnings growth and adjusted earnings per share (EPS) of $4.20. Adjusted gross profit grew 22%, operating income 31%, and adjusted net income 35%. Cash flow topped $1.25 billion, with a 96% free cash flow (FCF) conversion rate. Free cash flow topped $1.21 billion, more than sufficient to cover the $359 million in combined capital return.
Guidance is the hurdle for share prices in Q4. Management forecasted sequential growth, 15% year-over-year revenue growth, and widening margins. The bad news is that analysts had expected more on the top line; the good news is that the EPS forecast was better than expected, and business strengths are expected to persist into 2027.
The balance sheet raises no red flags and offers clear incentives to buy, with cash, assets, and equity up and total debt, net debt, and liabilities down. Equity improved by 20% year over year (YOY) while leverage fell to 1.3x.
Analysts Respond With Caution, Strengthen Outlook for 20% Upside
Analysts responded with caution to the release, citing the guidance miss and the expected Q4 slowdown. Initial responses included several reduced price targets and some raised ones. KeyCorp lowered its price target to $330, which is still 10% above the consensus forecast. Consensus forecasts a solid 20% upside as of late October, placing the stock near its all-time high.
This year’s catalysts include accelerating software-defined vehicle adoption, reacceleration in automotive and industrial end markets, margin strength, and buybacks. Software-defined vehicles are gaining traction globally, with Volkswagen OTCMKTS: VWAGY (and others) choosing NXPI’s microcontrollers to power onboard architectures.
The biggest risks are the company's legacy businesses, which are winding down and facing margin compression, tariffs, and supply chain exposure. The company has massive exposure to international supply chains, being headquartered in Europe and doing more than 25% of its business in the U.S. and more than 60% in Asia.
Institutional activity is a factor that investors should note. The institutional group owns more than 90% of the stock, reflecting strong confidence, and has aggressively accumulated shares in the mid-$200 range. If this company’s capital return or growth were in danger, the data would tell a different story.
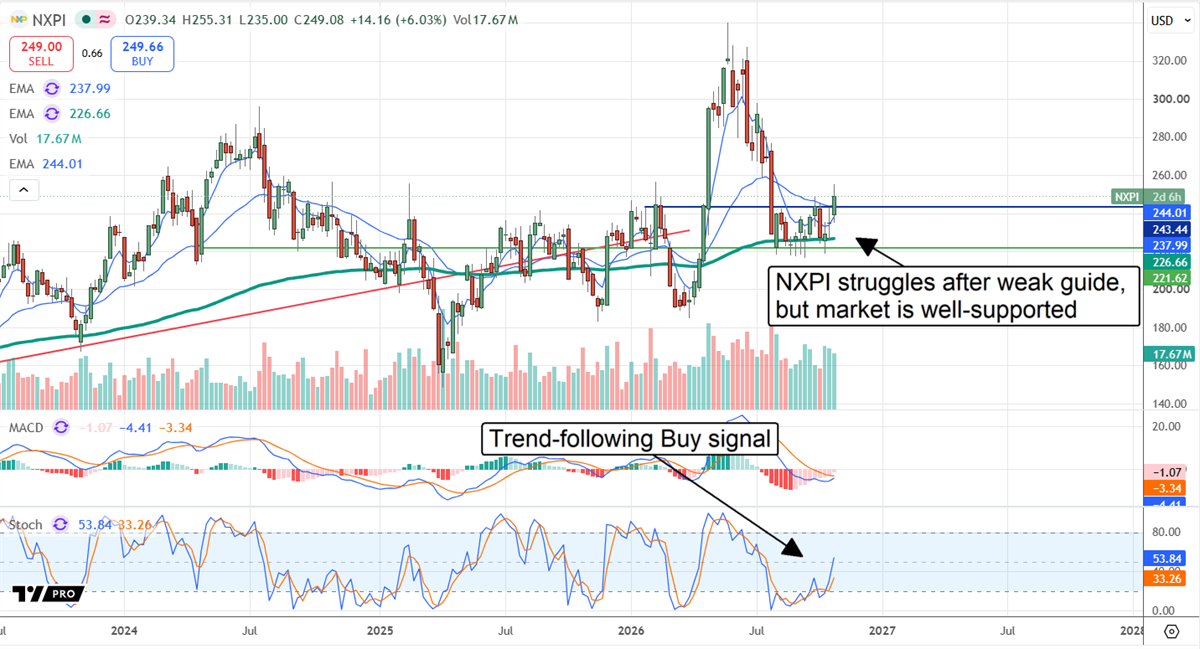
The charts likewise reflect institutional interest, with clear support along the 150-week exponential moving average (EMA). Investors can use it as a buying trigger, accumulating shares when price action reverts to the EMA and taking profits when it extends to overbought levels.
Before you consider NXP Semiconductors, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and NXP Semiconductors wasn't on the list.
While NXP Semiconductors currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
MarketBeat just released its list of the 7 hottest IPOs expected to hit Wall Street in 2026. See which companies are preparing to go public and why investors are watching closely.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.

