Pegasystems Today
$36.55 +1.37 (+3.89%) As of 03:01 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $25.10
▼
$68.10 - Dividend Yield
- 0.33%
- P/E Ratio
- 22.70
- Price Target
- $45.91
is easy to overlook because it operates in a highly competitive field against players ranging from
UiPath NYSE: PATH to
Salesforce NYSE: CRM. What sets it apart is its low-code approach to business automation, customer engagement, and compliance, which resonates with critical industries.
Its business is underpinned by highly regulated, customer-facing industries such as financial services, insurance, and healthcare that are well-suited to automation, and its low-code functionality makes the software accessible to users with limited coding experience. It is, effectively, a drag-and-drop platform built on a modular architecture that enables quick setup and adjustments, including built-in AI capabilities and governed integrations with AI assistants such as ChatGPT and Claude.
Pegasystems Cash Flow Is the Story, and the Moat Deepens
The narrative for late 2026 is that the shift to agentic AI could support substantial long-term cash flow growth. Management continues to target at least $700 million in free cash flow by 2028. While growth is slowing sequentially, investors should not get this wrong: the slowdown stems from industry-wide uncertainty affecting IT spending plans as well as go-to-market execution challenges that management has acknowledged. Management says underlying demand remains intact, but IT managers are hesitant to commit in a world where disruption lurks around every bend. What the market may overlook is that Pegasystems is an orchestration layer, providing a reliable interface with AI technology, however it advances, and not merely a business services software provider.
In this environment, its business is well entrenched with a narrow but deepening moat. Its moat is built on a differentiated platform that enables real-time, compliant decision-making in high-traffic environments and is strengthened by switching costs. Once established, the system becomes more valuable to users each day, as it builds on proprietary data and deep-seated existing relationships. The company has long-standing relationships with large enterprises and government agencies, supported by software designed to meet their compliance requirements.
Pegasystems Whiffs in Q3: Aggressively Buys Shares
Pegasystems had a tough Q3, growing only 3.1% to $393.36 million in net revenue and missing the consensus estimate by approximately 6.6% basis points. The bad news is that pipeline conversion was weaker than expected; the offset is that management recognizes the issue and has acted decisively to accelerate go-to-market activities. Within that, annual contract value (ACV) grew 6% as reported and 7% in constant currency, underpinned by Pega Cloud. Pega Cloud ACV grew by 20%, accounting for 59% of total ACV, and is expected to remain strong in the upcoming quarters.
Margin news is as mixed as revenue: gross margins expanded and adjusted earnings per share rose, while GAAP net income fell 68% year over year. Key details include profitability on both a GAAP and adjusted basis, a 17% increase in adjusted earnings per share, sufficient cash flow to sustain capital returns, the fortress-like balance sheet, and business development.
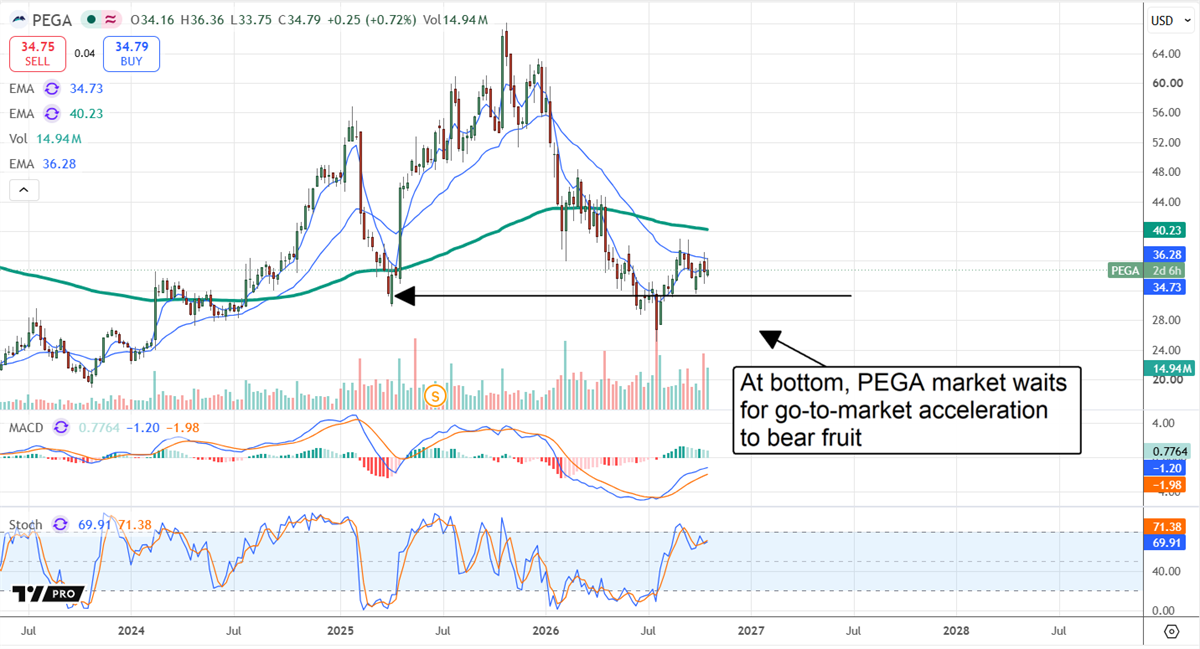
Balance sheet highlights reflect aggressive share buybacks, with cash, assets, and equity down, but reduced liabilities and a zero-debt position offset these factors and leave investors in a strong position. Shares are down by 8.4% on average for the quarter, over 6% year-to-date, with $810.1 million remaining under a buyback authorization extending through June 2027. The only question is when revenue growth will accelerate, and it will likely come over the next two to three quarters. The company’s backlog is growing faster than revenue, underpinned by a 20% increase in cloud demand.
Analysts Caution Caps Upside in Q4
Analysts are expressing caution due to Pegasystems slowdown and Q3 miss. Their concern centers on valuation and growth forecasts, focusing on near-term headwinds rather than the long-term opportunity. As it stands, the stock trades at a depressed valuation, about 23x earnings, failing to price in the opportunity, which suggests 50% or more upside over the next two to three years.
Pegasystems Stock Forecast Today
12-Month Stock Price Forecast:$45.9124.38% UpsideHoldBased on 15 Analyst Ratings | Current Price | $36.91 |
|---|
| High Forecast | $60.00 |
|---|
| Average Forecast | $45.91 |
|---|
| Low Forecast | $25.00 |
|---|
Pegasystems Stock Forecast DetailsLooking ahead, analysts expect double-digit earnings growth to continue, putting the stock in the low teens relative to the 2030 earnings consensus.
Sentiment trends are as mixed as any other PEGA metric, with the consensus rating at Hold and price targets trending lower over the last year. The analysts' low-end target aligns with the market bottom, while consensus forecasts around 22% upside as of late October, suggesting room for recovery if execution improves.
This year’s catalysts include the launch and rollout of new tools, such as Pega Infinity ‘26 and its responsible AI capabilities. Pega Infinity ‘26 elevates the platform from copilots and assistance to agentic orchestration, enabling multiple agents to work collectively on tasks and problems.
Its responsible AI capabilities provide built-in governance and safeguards, including a “center-out” architecture that binds AI to specific logic layers. The biggest risk now is execution; if the company can’t accelerate contract acquisition, the stock price recovery will take much longer.
Before you consider Pegasystems, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Pegasystems wasn't on the list.
While Pegasystems currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Nuclear energy is entering a new growth cycle as rising power demand, expanding data centers, and renewed policy support bring the sector back into focus. After strong gains in recent years, the most impactful phase of nuclear investment may still be ahead. This report highlights seven nuclear energy stocks positioned across the value chain—combining near-term revenue with long-term upside as next-generation technologies scale. Click the link below to unlock the full list.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.

