RPM International’s NYSE: RPM earnings report for Q1 of its fiscal year 2027 (FY2027) shows why Dividend Kings make such good buy-and-hold stocks.
While macroeconomic headwinds persist and affect activity across industries, RPM International quietly grows, sets new records, and drives robust cash flows.
RPM International Today
RPM
RPM International
$98.06 -0.25 (-0.26%) As of 09:54 AM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $92.92
▼
$121.78 - Dividend Yield
- 2.20%
- P/E Ratio
- 18.81
- Price Target
- $125.85
Cash flow is the critical factor—its business is well-entrenched and as mature as it gets—because it remains strong, enabling accelerated capital returns.
RPM International looks like not only a good Hold, but also a good Buy in 2026, because its stock currently trades at depressed levels.
Down more than 30% from their 2024 highs, RPM shares are trading at rock-bottom (approximately 15x current-year earnings) with nowhere to go but up. Technical signals show solid support, with a rebound likely in Q4 2026.
RPM Builds Leverage for Stock Price, Robust Rebound Possible
RPM's capital return isn’t huge but is reliable and growing, which matters. The stock yields a historically high 2.2% as of early October, with total capital returned to shareholders up 10% year over year. This includes buybacks, which incrementally reduce the share count each quarter, increasing shareholder leverage and improving capacity for future distribution increases.
Total capital returned to shareholders was less than 45% of Q1 FY2027 free cash flow, leaving plenty of cash for debt reduction and balance sheet improvements. Balance sheet highlights include reduced total debt, increased liquidity and assets, and improved shareholder equity despite the buybacks. Equity, which measures shareholder value, grew by nearly 14% year over year, setting the stage for a robust price recovery once the market gains traction.
Analyst trends align with the potential for robust price recovery. While analyst activity in 2026 included several price target reductions and a slight downturn in the consensus target, the market overreacted, creating a deep-value opportunity. Trading at $98 in early October, the stock is about $13, or over 10%, below the analysts' lowest target, with about 30% upside to the consensus. Initial reactions to RPM's earnings report were positive, so investors can assume the analysts' price floor is firm.
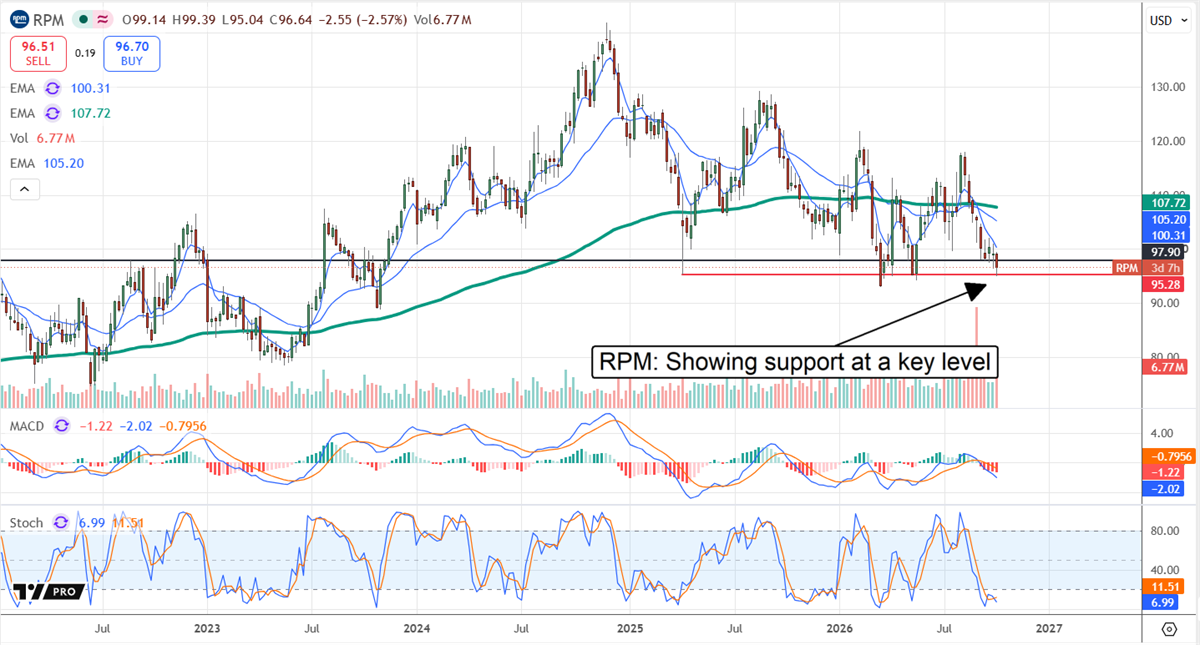
Institutions, which own about 80% of the shares, are likewise bullish on the stock, having bought aggressively in Q2 as the price tested its technical floor. Technically, their price floor is near $95, a level tested three times, going on four, since early 2025, coincident with resistance levels reached and broken during the COVID-19 recovery and economic surge.
RPM International Outperforms Where It Counts: The Bottom Line
RPM International had a good quarter, given the macroeconomic headwinds, with revenue growing by 4.8% to $2.22 billion, as expected. Growth came from a mix of organic strength, pricing, and acquisitions, with the Construction Products Group (CPG) up a modest 0.8%, led by a 5.3% increase in the Consumer Group and a 10.2% gain in the Performance Coatings Group (PCG). Regionally, all grew, with results varying across regions and strength in emerging markets. Execs revealed more than 20% growth across emerging markets, driven by infrastructure spending and business investments.
Margin news was also positive. The company offset inflation through price increases and efficiency, driving an 11.1% increase in cash from operations, more than $200 million in free cash flow after capital expenses, and a 5.3% increase in adjusted earnings per share. More importantly, management reaffirmed guidance with a narrower range, expecting mid-single-digit growth to persist all year and margins to remain healthy.
RPM International Has a Moat
RPM’s moat is easy to see. Consumer specifications, selling systems rather than products, and high switching costs keep consumers coming back. The company's products help protect construction, infrastructure, and manufacturing investments at a negligible cost compared to the cost of failure. It's better to put a coat of paint on something you can trust than to replace the whole thing.
This year’s catalysts include restructuring and Margin Achievement Program (MAP) gains, strategic acquisitions, and governmental tailwinds. Restructuring and MAP gains are pushing gross margins above 40% while reducing SG&A, enabling accelerated earnings growth. Strategic acquisitions aim to complement the existing portfolio while aiding the streamlining process. Headwinds remain, but are offset by tailwinds linked to the Infrastructure and Jobs Act, which provides funding for a range of RPM products.
RPM’s risks are macroeconomic and systemic, unrelated to its operational quality. They include segment softness, with the CPG segment lagging; cost pressures; execution; and credit. Cost pressures are being mitigated but remain a threat, while execution and credit remain the bigger risks. Missteps will be reflected in the stock’s price, as will systemic risks linked to client credit. Defaults, or even the fear of defaults, could trigger a massive sell-off in this stock.
Before you consider RPM International, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and RPM International wasn't on the list.
While RPM International currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Discover the 10 Best High-Yield Dividend Stocks for 2026 and secure reliable income in uncertain markets. Download the report now to identify top dividend payers and avoid common yield traps.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
