Valero Energy Today
VLO
Valero Energy
$386.78 -39.99 (-9.37%) As of 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $159.90
▼
$461.52 - Dividend Yield
- 1.24%
- P/E Ratio
- 8.70
- Price Target
- $379.94
Earnings season is in full swing, and for energy companies, that means another quarter of record-smashing numbers. That includes one of the world's largest refiners,
Valero Energy Corp. NYSE: VLO, which reported its results before the market opened on Oct. 22. The company posted another quarter of sharply higher revenue and record earnings, yet the stock sold off in the session after the conference call. One potential cause is geopolitical, as the Trump administration plans to bring Russian diesel into the U.S. to push down record prices. Now that Q3 is in the rearview mirror, the big question is how much of this margin survives into Q4, when Washington wants prices lower. Has a new baseline formed, or has Valero peaked in its earnings cycle?
What Valero’s Q3 2026 Report Actually Showed the Market
Valero’s headline results were terrific, but it's the guidance numbers under the hood that may give investors pause. In fiscal Q3 2026, the company earned $46.1 billion in revenue and $23.90 in earnings per share (EPS), both quarterly records. Sales rose more than 43% year-over-year (YOY), but EPS growth of about 550% over Q3 2025 really raised eyebrows. And if you’ve been following our refining stocks coverage, you likely already know why the company’s margins have soared.
Record crack spreads have enabled U.S. refiners to grow margins in ways their executives could previously only imagine. Management reported its Gulf Coast refining margin grew to $37.55 per barrel in Q3, up from $24.42 per barrel in Q2 and $12.21 per barrel in Q3 2025. The system-wide margin reached $39.24 per barrel, about $3 above analysts’ consensus and well above last year’s $13.14 per barrel figure. Valero continues to capture huge margins, and this gap appears at least partly structural.
Light guidance could be contributing to the negative market reaction. Management offered Q4 operating throughput guidance slightly below Q3, at 2.875 to 2.975 million barrels per day. However, the team hopes its $9.8 billion cash pile will offset any Q4 margin weakness, and it has yet to see any demand destruction from high fuel prices.
How Russian Diesel Could Impact Valero’s Refining Margins
One factor beyond the company’s control is Russian diesel entering U.S. markets. The Trump Administration announced an executive order on Oct. 16 granting a waiver to Russian petroleum products that the Graham Act would have sanctioned. The agreement calls for purchasing about 2.25 million barrels of oil (with more later in the year) to reduce pump prices ahead of the midterm elections.
Valero Energy MarketRank™ Stock Analysis
4.20977754785 of 5 stars- Overall MarketRank™
- 84th Percentile
- Analyst Rating
- Moderate Buy
- Upside/Downside
- 4.3% Downside
- Short Interest Level
- Healthy
- Dividend Strength
- Moderate
- News Sentiment
- 1.19
- Insider Trading
- N/A
- Proj. Earnings Growth
- -5.15%
See Full AnalysisHowever, the Valero Q3 conference call cooled the idea that this volume would impact tight supplies. Responding to an analyst question, Chief Operating Officer (COO) Gary Simmons said the announced Russian diesel exports would only bring volume back to July levels, and the market would still be short 600,000 to 700,000 barrels per day compared with the same period last year. Simmons said Russian diesel could limit disruptions, but is unlikely to ease supply shortages. The deal has also drawn bipartisan criticism, with 12 senators from both sides of the aisle calling it “a gift to our adversary and a betrayal of our allies.”
What could squeeze Valero’s refining margins? Ironically, higher crude prices. If raw crude prices rise from here while refining is near max capacity, Valero has limited ability to keep capturing high spreads. Headline diesel crack spreads have already dipped below $100 after hitting a record near $112 a few weeks ago, and management has already conceded seasonal weakness in its conservative Q4 guidance. Plus, normalizing Strait of Hormuz traffic hurts the company’s Gulf Coast export system as its freight-driven cost advantages dwindle, which in theory should suppress margins.
Investors Sell the News as Stock Pulls Back From Overbought Range
VLO shares had strong technical momentum ahead of the print, but shaky signals began to appear in the days before the release. The stock price trades well above the 50-day and 200-day moving averages, and hasn’t dipped below the 50-DMA since early July. The Moving Average Convergence Divergence (MACD) indicator flipped positive on Oct. 5, and shares closed at a new all-time high of $459.73 on Oct. 14. But the Relative Strength Index (RSI) hit 76 on the same day, triggering its second Overbought signal in as many weeks.
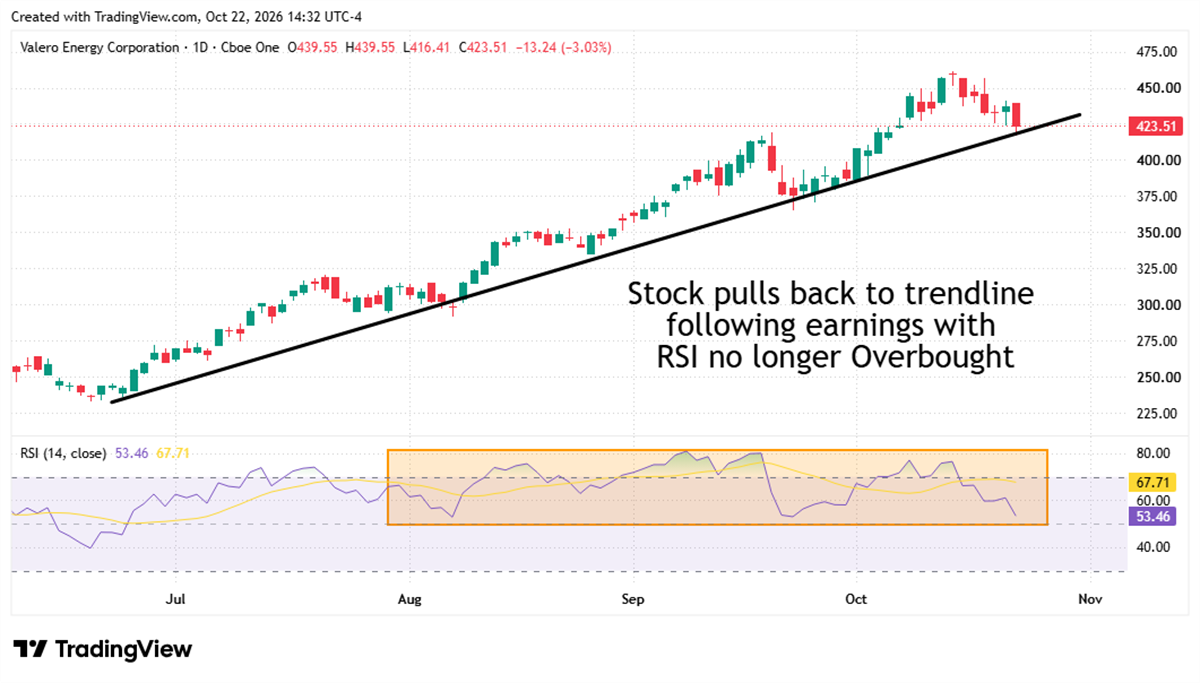
Profit-taking began softening momentum during the week of the report, and investors hit the cash register on the day of the release despite record-setting numbers. While peak crack spreads may be in the rearview mirror, the sell-off came on lighter-than-average volume, and the setup for a strong finish remains. VLO shares have retreated to a trendline that has marked the low in each of the previous two drawdowns. The RSI is also out of Overbought territory but has yet to fall below the bullish threshold of 50. If the trendline and RSI hold, this drawdown might be another entry point for new positions.
Before you consider Valero Energy, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Valero Energy wasn't on the list.
While Valero Energy currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
The space race is growing fast, and you don’t have to have gotten in early on SpaceX to profit. This report shows seven space stocks you can buy today that may grow as rockets, satellites, defense, space internet, and new space technology become more important.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.

