Amprius Technologies Today
AMPX
Amprius Technologies
$8.39 -0.16 (-1.92%) As of 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $7.02
▼
$24.23 - Price Target
- $20.50
Investors looking for fault in Amprius Technologies’ NYSE: AMPX Q3 earnings report will be hard-pressed to find it. While reported losses were a penny per share worse than expected, the news isn’t all that bad, considering where Amprius Technologies is in the business cycle.
Amprius Technologies is a disruptive tech start-up in the midst of a capacity and production ramp. Capacity and production ramps cost money; investors should focus on shrinking year-over-year losses and the company's contract manufacturing strategy. In this scenario, AMPX is moving toward full commercialization and profitability, although management still expects a GAAP net loss for 2026.
Amprius Builds Momentum in Q3: Raises Guidance
Amprius Technologies' quarter was as strong as whispers suggested, with revenue up 83% year over year to $39.1 million. Improving demand across key segments such as aerospace, drones, defense, and mobility drove the top line, outpacing the consensus estimate by about 9%. Equally important, the company revealed scale leverage, improving its gross margin by about 12 percentage points to 27%.
Executives raised revenue guidance to about $145 million, about 3% above consensus, and the forecast could prove conservative given the strength shown in Q3. Reasons to believe guidance is cautious include surging domestic demand, with U.S. revenue growing 2.3 times sequentially, the shift toward National Defense Authorization Act (NDAA) compliance, new product launches, and a history of conservatism. New products include the SiCore 500, launched in September. It provides enhanced energy density, commands premium pricing, and is seeing demand from aviation and unmanned vehicle manufacturers. However, Amprius also lowered its 2026 adjusted EBITDA guidance from more than $4 million to at least $2.5 million as it increased spending to support growth.
Amprius Technologies’ balance sheet helps highlight the strength of its position. The pivot away from building its own manufacturing facility to contract manufacturing lightened its load, reducing the capital spending required to expand production. Q3 highlights include nearly $61 million in cash versus $7.8 million in quarterly operating cash burn, higher receivables, current and total assets, and lower liabilities. Equity surged by about 20%, and the company reported no debt, reducing balance-sheet risk.
Analysts' Trends Support AMPX Price Action: Downside Risks in Decline
Amprius Technologies Stock Forecast Today
12-Month Stock Price Forecast:$20.50136.04% UpsideModerate BuyBased on 14 Analyst Ratings | Current Price | $8.69 |
|---|
| High Forecast | $33.00 |
|---|
| Average Forecast | $20.50 |
|---|
| Low Forecast | $14.00 |
|---|
Amprius Technologies Stock Forecast DetailsAMPX has plenty of risk, mostly centered on strategy execution and the potential hiccups and hurdles that may develop. Even so, analysts' ratings remain favorable and point to significant potential upside.
Trends leading into the release include improving coverage and broadly positive sentiment, with 14 analysts contributing to a Moderate Buy consensus rating, an 85% Buy-side tilt in the data, and approximately 130% upside to the consensus price target. The Q3 release may not trigger massively bullish revisions, but it could be sufficient to keep the group in a bullish posture.
The biggest trading risks include limited institutional ownership and short interest. Institutions own only about 5% of the stock, although recent filings show significant buying activity, and short interest remains high.
With this in play, the stock price may struggle to advance without a catalyst, and the next catalysts may not emerge until the Q4 release in early 2027. However, at 16%, the short interest suggests a rapid price advance is brewing, needing only time and the catalyst to trigger it.
Amprius on Track for Catalyst-Filled Year
Upcoming catalysts center on the recently awarded $75 million Department of Defense contract. Executing on it unlocks milestone awards while advancing NDAA compliance. Amprius expects to achieve full NDAA compliance with domestically produced cells in 2027 and plans for the upgraded U.S. production line to have capacity for up to 12 million cells annually by early 2028. New contracts could follow over the next four quarters as the company advances toward compliance, and they could contribute to future revenue growth. Advancing strategy, improving cash flow, and the transition to profitability are crucial, as they could attract greater interest from analysts and institutions.
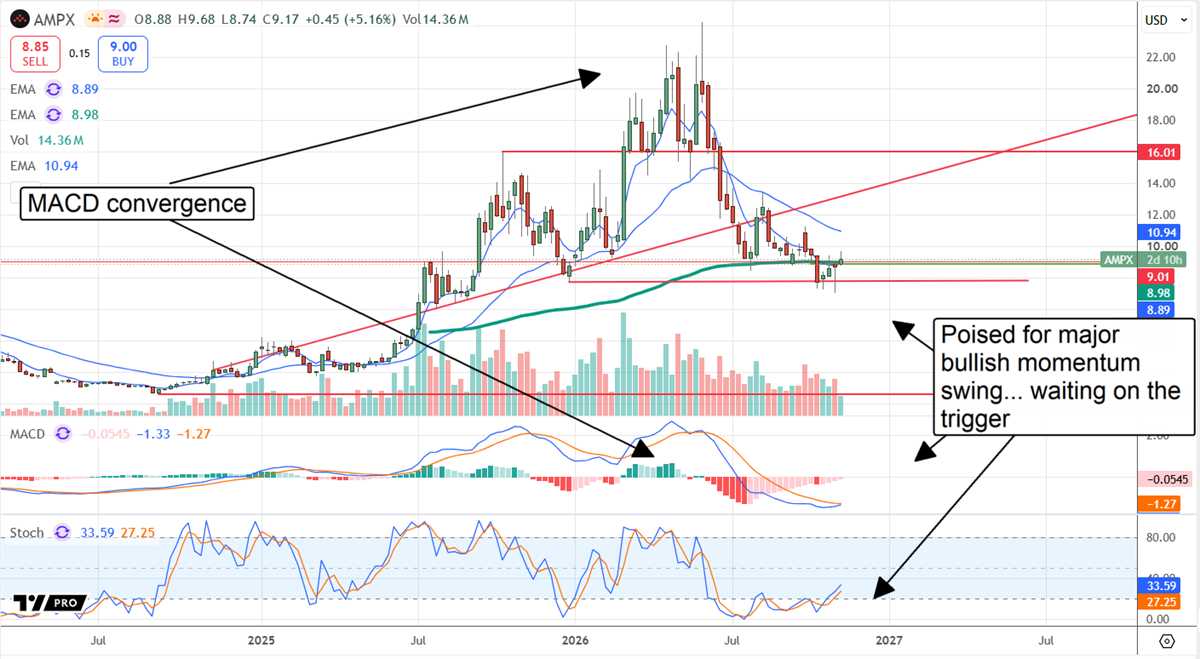
Price action reflects a knee-jerk reaction to the headline miss and a potential buy-the-dip opportunity. The initial response was a more-than-7.5% drop in after-hours trading, which later narrowed. The signal is that fear remains in this market; it's ready to sell on the drop of a bad headline, but the fundamental story remains intact. With moving average convergence divergence (MACD) and stochastic indicators aligning with strong support and a major market reversal, AMPX could sustain support near the early November lows, build its base, and eventually reverse.
Technical targets are robust, with MACD convergences suggesting a retest of existing highs is possible in the near- to mid-term. Longer-term upside could be substantial if the company succeeds, but those gains will depend on expanding production and achieving sustained profitability.
Before you consider Amprius Technologies, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Amprius Technologies wasn't on the list.
While Amprius Technologies currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Oil still powers the global economy, but AI is reshaping the energy opportunity. Discover seven stocks spanning traditional energy, infrastructure, and next-generation power.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
