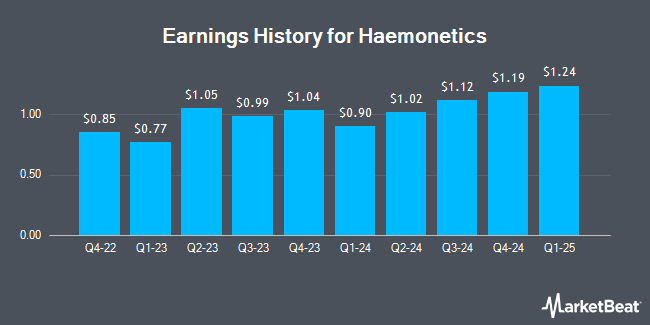
Haemonetics (NYSE:HAE - Get Free Report) issued its quarterly earnings data on Thursday. The medical instruments supplier reported $1.35 earnings per share (EPS) for the quarter, topping analysts' consensus estimates of $1.29 by $0.06, FiscalAI reports. The business had revenue of $357.76 million during the quarter, compared to the consensus estimate of $345.15 million. Haemonetics had a net margin of 7.52% and a return on equity of 27.42%. The firm's quarterly revenue was up 9.4% compared to the same quarter last year. During the same period in the prior year, the firm posted $1.27 EPS.
Here are the key takeaways from Haemonetics' conference call:
- Second-quarter organic revenue grew 10% and adjusted EPS rose 6% to $1.35. Haemonetics raised its fiscal 2027 organic revenue growth outlook to 6%–9%, from 4%–7%.
- Apheresis revenue grew 14% in the quarter, including 18% growth in plasma, and the company raised its fiscal-year apheresis outlook to high-single-digit growth. Persona PLUS adoption and CSL center conversions are supporting the outlook, though it excludes incremental revenue from second-half collection growth and unconfirmed additional CSL conversions.
- The expanded CSL relationship is expected to provide a multiyear growth opportunity, with the full Persona PLUS suite rolling out across CSL’s U.S. centers by the end of calendar 2027. Management said capacity and device investments will weigh in the near term but expects operating leverage as volumes scale, particularly in fiscal 2028 and beyond.
- Fiscal 2027 adjusted operating margin expansion guidance was cut to 0–50 basis points from 50–100 basis points, reflecting performance-based compensation, inflation, freight costs, and spending ahead of plasma growth. Management expects second-half margin expansion to be weighted toward the fourth quarter.
- Cash generation strengthened: first-half operating cash flow rose 40% to $180 million and free cash flow increased about 57% to $143 million. The company expects fiscal-year free cash flow conversion above 80% of adjusted net income and cited cash generation as support for growth investment, debt reduction, and potential share repurchases.
Haemonetics Stock Performance
HAE traded down $4.24 during trading on Friday, hitting $119.87. 834,665 shares of the company traded hands, compared to its average volume of 721,582. The firm has a market cap of $5.45 billion, a P/E ratio of 23.56, a price-to-earnings-growth ratio of 2.40 and a beta of 0.63. The stock's fifty day moving average is $111.48 and its 200 day moving average is $80.05. The company has a quick ratio of 1.91, a current ratio of 2.84 and a debt-to-equity ratio of 1.24. Haemonetics has a one year low of $51.00 and a one year high of $132.00.
Wall Street Analysts Forecast Growth
Several equities analysts have commented on the stock. JPMorgan Chase & Co. lifted their target price on shares of Haemonetics from $62.00 to $86.00 and gave the stock a "neutral" rating in a research report on Friday, August 7th. Mizuho set a $165.00 target price on Haemonetics in a report on Thursday. Weiss Ratings raised Haemonetics from a "hold (c-)" rating to a "hold (c)" rating in a research report on Tuesday, August 11th. Barrington Research lifted their price target on Haemonetics from $140.00 to $145.00 and gave the stock an "outperform" rating in a report on Friday. Finally, BTIG Research lifted their price target on Haemonetics from $130.00 to $142.00 and gave the stock a "buy" rating in a report on Thursday. One equities research analyst has rated the stock with a Strong Buy rating, seven have assigned a Buy rating and three have issued a Hold rating to the company's stock. Based on data from MarketBeat.com, the stock has a consensus rating of "Moderate Buy" and a consensus target price of $126.38.
Check Out Our Latest Research Report on HAE
Key Stories Impacting Haemonetics
Here are the key news stories impacting Haemonetics this week:
- Positive Sentiment: Quarterly results beat expectations: Haemonetics earned $1.35 per share versus estimates of $1.29 and generated $357.8 million in revenue, above the $345.2 million consensus and up 9.4% year over year. Earnings and outlook report
- Positive Sentiment: Raised fiscal 2027 outlook: The company increased its full-year revenue and organic-growth outlook, forecasting organic growth of 6%–9%. Fiscal 2027 outlook
- Positive Sentiment: Analyst price targets rose: Citigroup raised its target to $149 and maintained a Buy rating; Barrington Research lifted its target to $145 with an Outperform rating; and BTIG raised its target to $142 with a Buy rating. Citigroup recommendations
- Neutral Sentiment: Growth comes with execution considerations: Haemonetics plans to scale the CSL Persona PLUS rollout through calendar 2027, and earnings-call coverage noted growth and margin tradeoffs. This may temper enthusiasm if rollout costs or margins disappoint. Earnings call highlights
Haemonetics Company Profile
(
Get Free Report)
Haemonetics Corporation NYSE: HAE is a healthcare technology company that develops and supplies products and services for blood and plasma collection, processing, and management. Its solutions are used by blood and plasma collection organizations, hospitals, and other healthcare providers to support the efficient handling of blood components and improve patient care.
The company's offerings include automated plasma and blood-component collection systems, disposable collection sets, blood-processing equipment, and software designed to manage collection and transfusion-related operations.
Read More
This instant news alert was generated by narrative science technology and financial data from MarketBeat in order to provide readers with the fastest reporting and unbiased coverage. Please send any questions or comments about this story to contact@marketbeat.com.
Before you consider Haemonetics, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Haemonetics wasn't on the list.
While Haemonetics currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Discover the next wave of investment opportunities with our report, 7 Stocks That Will Be Magnificent in 2026. Explore companies poised to replicate the growth, innovation, and value creation of the tech giants dominating today's markets.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
