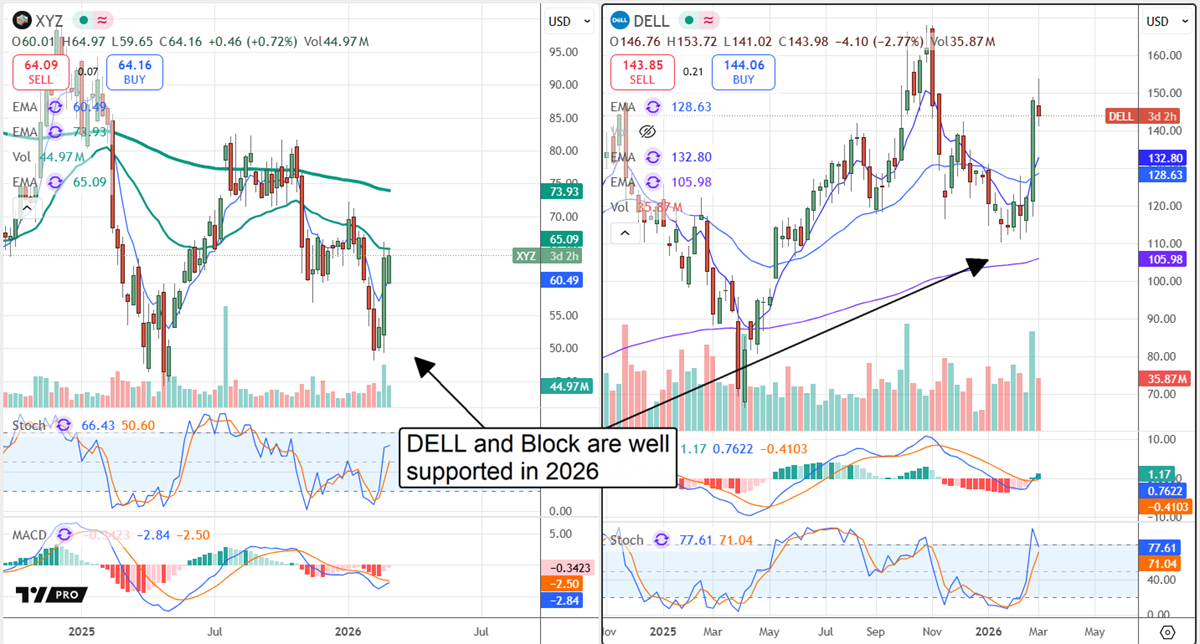
In today’s markets, where macroeconomic concerns, fears centered on AI spending and disruption, inflation, and interest rates weigh on performance, cash flow is king. Companies that produce revenue and, more importantly, free cash flow and profits, are being rewarded while those that aren’t get punished. For example, Dell NYSE: DELL (generating record cash from AI) and Block NYSE: XYZ (cutting costs to boost cash) are rebounding from early 2026 lows, while others, like Lucid NASDAQ: LCID, which also show business improvement, continue to flounder.
It All Starts With Gross Margin: Is The Underlying Business Profitable?
Gross margin is where this story begins. Gross margin is a measure of the underlying operation’s profitability, separating the cost of revenue from the actual product. In this case, Dell and Block both produce positive gross margins, are widening margins in 2026, outperforming expectations, and working to sustain and/or build on their strengths.
Lucid Group Today
$2.95 -0.31 (-9.51%) As of 11/13/2026 04:00 PM Eastern
- 52-Week Range
- $2.37
▼
$14.91 - Price Target
- $7.11
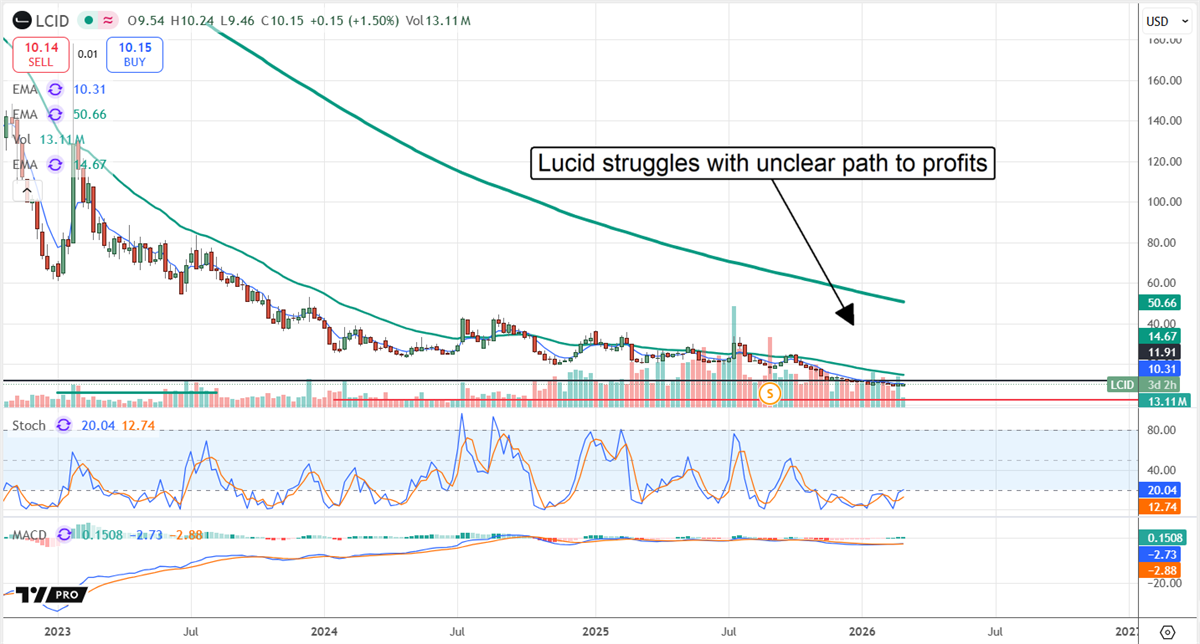
On the other hand, Lucid, whose car business could be profitable with scale, isn’t. The company not only generates negative cash flow, but its cost of revenue far exceeds revenue, excluding the impacts of R&D and general administrative costs. When it comes to picking cash flow winners, Lucid is out of the game before it even starts.
Looking forward, there is hope. Lucid is accelerating production and delivering cars faster than anticipated, accelerating its timeline to profits along with it. The bad news is that profitability isn’t expected for several more years, leaving plenty of time for execution risk and industry disruption to damage market sentiment. In the meantime, Dell and Block are both forecasted to grow at steady paces while improving their profitability.
Balance Sheets Reflect the Impact of Cash Flow
Dell Technologies Today
DELL
Dell Technologies
$344.32 -26.85 (-7.23%) As of 11/13/2026 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $110.22
▼
$595.51 - Dividend Yield
- 0.73%
- P/E Ratio
- 19.98
- Price Target
- $569.96
Quarterly results provide insights into operations, quality, and business momentum, but the balance sheet reflects the company’s health. Companies with healthy cash flow tend to show increases in cash or assets, or both, alongside reductions in debt or liabilities, or both, and increases in equity. They also enable capital returns, such as dividends and share buybacks, to improve shareholder leverage.
Dell, however, is a unique story. Its cash flow is robust enough to enable aggressive capital return alongside business investment, resulting in negative shareholder equity. The offset is that its cash balance runs hot, leverage runs cool, and capital returns are sustainable, yielding about 1.35% in early 2026, while buybacks reduced the count by more than 5% in 2025.
Block Today
$84.43 +2.17 (+2.64%) As of 11/13/2026 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $48.21
▼
$89.39 - P/E Ratio
- 114.10
- Price Target
- $100.67
Block does not pay dividends nor buy back shares in sufficient quantities to reduce the count, but it does return capital, and its balance sheet reflects an ability to sustain and improve the return over time. Year-end highlights include a reduced but still ample cash position, offset by increased assets, managed debt, and increased equity.
Lucid’s balance sheet, however, reflects its cash burn. The highlights at the end of its fiscal year 2025 include reduced cash, current, and total assets, compounded by increased debt and liabilities (not counting the substantial dilution), thereby undercutting shareholder value. Equity fell from nearly $4 billion to under $1 billion and is likely to continue eroding in 2026.
Cash Flow Equals Market Support in 2026
Evidence of the importance of cash flow on market sentiment is reflected in the analysts' sentiment and institutional trends. Where analysts rate Dell and Block as Moderate Buys with a 70% and 75% Buy-side bias, respectively, showing high conviction in sentiment via a high number of ratings, only a few analysts rate Lucid, and it is pegged at Sell. The price target suggests LCID could rebound substantially, but the trend is toward the low end, and institutions are selling, keeping this market down. Conversely, price target revisions are bullish for Dell and XYZ, leading them higher as of early March.
The risk for investors is more than just lagging the market. The lack of gross margin, cash burn, dilution, and tepid market support leaves stocks like Lucid susceptible to short selling, and short sellers are leaning hard into this trade. The short interest is running near 40%, more than sufficient to keep this market wallowing at long-term lows if not moving lower. There is potential for a short-squeeze and short-covering rally, but the odds of those are low in 2026.
Before you consider Dell Technologies, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Dell Technologies wasn't on the list.
While Dell Technologies currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
AI spending is reshaping the market, and the opportunity extends far beyond the biggest chipmakers. Discover 10 stocks set to benefit from powerful trends in AI infrastructure, cloud computing, energy, capital returns, and consumer growth this fall.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
