Cerebras Systems Today
CBRS
Cerebras Systems
$108.72 +10.97 (+11.22%) As of 11/13/2026 04:00 PM Eastern
- 52-Week Range
- $77.84
▼
$386.34 - Price Target
- $237.80
Cerebras Systems’ NASDAQ: CBRS Q3 results echo a message reflected across AI-critical companies: the leading hardware, software, and services that produce value for hyperscalers are in increasing demand. The industry has shifted from speculating on which technologies might be best to focusing on the best, forecasting several quarters of growth acceleration and sustained long-term strength.
While CBRS faces its own company-specific headwinds, including dilution associated with its IPO and customer warrants, they are being weighed against the growing demand for Cerebras hardware, which delivers high-speed, cost-efficient inference. Its utility shows up in the results, which beat consensus and were compounded by strong guidance and a backlog worth more than 100x Q3 revenue.
Cerebras Is on the Verge of Explosive Growth
Cerebras Systems grew core revenue 70% in Q3, outpacing consensus by about 7 percentage points, driven by strength from new and existing customers. Hardware sales fell versus the prior year but are offset by surging cloud and services demand. Core cloud, which excludes pass-through revenue and costs and adds non-cash charges, grew more than 270% to about 67% of revenue and is expected to accelerate in upcoming quarters.
Cerebras improved its core gross margin, supported by scale leverage, but offset it with increased spending tied to its capacity ramp. Management expects spending to continue, but rising capacity and utilization could improve core margins and shorten the path to profitability.
Cerebras expects core revenue to grow about 40% sequentially to about $320 million, and the guidance may prove cautious. The company has another 700mw capacity under contract, supported by new hyperscale and neocloud wins, including a top-three hyperscaler that remains unnamed, and the backlog. In this scenario, the company needs to execute on its capacity ramp and contractual commitments to drive better-than-forecasted results.
The new top-tier hyperscaler is a validating factor. While the report didn't name it, CEO Andrew Feldman later revealed it was Microsoft NASDAQ: MSFT, making Alphabet NASDAQ: GOOGL a notable hyperscaler without a publicly disclosed Cerebras partnership. Other relationships include OpenAI, Amazon NASDAQ: AMZN, and Oracle NYSE: ORCL, plus a model-integration partnership with Meta Platforms NASDAQ: META.
The takeaway is the scale of Cerebras demand, which is hyperX3: several major cloud providers and neoclouds have agreements to deploy or offer Cerebras technology, broadening its customer base. As it stands, management expects revenue to roughly triple next year, although projections for later years depend on continued execution.
Analysts Respond With Cautious Optimism
Cerebras Systems Stock Forecast Today
12-Month Stock Price Forecast:$237.80118.73% UpsideModerate BuyBased on 14 Analyst Ratings | Current Price | $108.72 |
|---|
| High Forecast | $325.00 |
|---|
| Average Forecast | $237.80 |
|---|
| Low Forecast | $155.00 |
|---|
Cerebras Systems Stock Forecast DetailsAnalysts generally like what they see in Cerebras's report, citing the backlog and capacity ramp as triggers for the stock price. However, they also expressed caution tied to execution, citing delays with OpenAI and the general risks of expanding high-tech manufacturing. Delays with OpenAI are concerning but offset by CEO commentary; Mr. Feldman says delays are tied to land, construction, and power, rather than supply constraints or manufacturing hiccups. The good news is that sentiment remains intact, and consensus forecasts a triple-digit upside as of mid-November. The bad news is that analysts trimmed targets, some drastically, creating a headwind for price action.
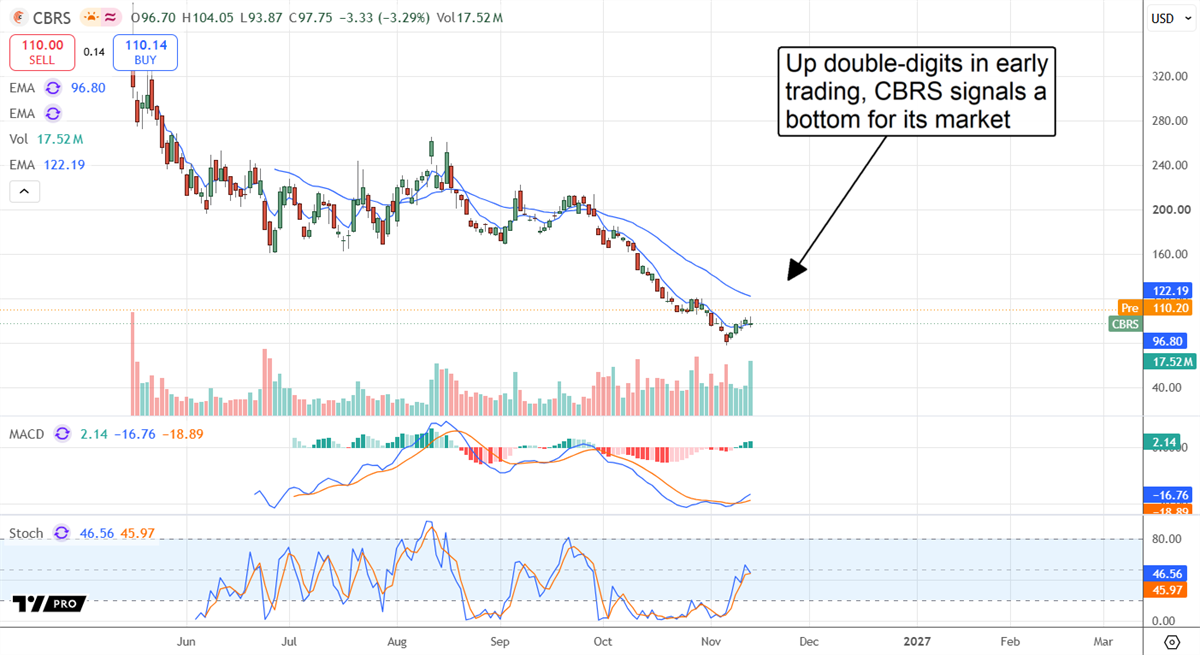
CBRS stock price responded favorably to Cerebras’ report despite the analysts’ revisions. Shares surged by more than 10% in extended trading, suggesting a possible market bottom and potential for short-covering over the next few months. Short interest was high ahead of the release, above 9%, sufficient to lift share prices with covering, but the relatively low 2.1 days to cover may limit the potential for a sustained squeeze. Other signs of market strength, a price floor, and potential for a rebound include bullish crossovers in the stochastic and MACD indicators, steadily increasing trading volume, and conspicuous volume spikes coinciding with the latest lows and pre-release price action: signs of possible short covering.
Time is the biggest risk: the time it takes to ramp capacity, execute on remaining performance obligations, and transition to profits. The balance sheet suggests the capital runway is clear, with substantial cash and investments to support expansion, although spending requirements remain significant. The catalysts are executing the backlog and transitioning to profitability, with management forecasting core operating results near breakeven in Q4, while sustained GAAP profitability remains uncertain.
The market is right to treat this stock with caution, given the execution risks, but it is wrong to treat it as a run-of-the-mill startup. Its product is validated; it has revenue, signs of acceleration, and a pathway to near-term profitability. Long-term earnings forecasts suggest substantial potential upside, but the case for deep value depends on ambitious growth assumptions.
Before you consider Cerebras Systems, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Cerebras Systems wasn't on the list.
While Cerebras Systems currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
The AI boom is creating opportunities across semiconductors, cloud computing, enterprise software, infrastructure, cybersecurity, and automation.
Inside this report, you’ll find 10 companies positioned to benefit as artificial intelligence moves from hype to real-world deployment and becomes a core growth driver for corporate America.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
