Darden Restaurants Today
DRI
Darden Restaurants
$199.42 -7.82 (-3.77%) As of 09/25/2026 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $169.00
▼
$229.76 - Dividend Yield
- 3.25%
- P/E Ratio
- 19.49
- Price Target
- $232.38
price pullback could be a sell-the-news, buy-the-dip event because the strengths were expected. Investors should focus on the strengths: a portfolio of well-known, market-leading brands in key categories, including niche fine dining, which is about as good as it gets. Tepid results don’t necessarily mean weak results when analysts forecast industry-leading growth and sufficient profitability to sustain financial health, capital returns, and the
uptrend in stock prices.
As always, the brand, management, and results influence stock-price valuation and outlook, but cash flow and capital returns drive it. In this case, capital returns include dividends and buybacks, providing significant leverage, even with share prices trading near record levels. Darden’s dividend annualizes to about 3.1%, and aggressive share buybacks compound it. Trailing-12-month (TTM) activity reduced the count by 2.7% as of Q1 fiscal year 2027 (FY2027).
The net result is that cash flow, aided by a reduction in share count, enables aggressive annual increases that could continue into the upcoming year. As it stands, Darden’s distribution compound annual growth rate (CAGR) is a modestly high double-digit figure, well above inflation.
Darden’s Balance Sheet Supports Capital Returns
Darden Restaurants’ high-yield, aggressive buyback might be a red flag, but it isn’t. While higher yields and sudden share-count drops often lead to stalled or declining returns, Darden is well-positioned to sustain its payouts and increase them in the coming year. The worst news is that equity declined 6% in Q1 FY2027, but the share-count reduction and dividend payment offset it. Key details include flat cash, higher current and total assets, persistently low leverage, and ample cash flow. Coverage matters, and cash flow covered Q1 FY2027 activity, including capital returns and investments in store count and technology.
Institutions and analysts reflect strong conviction in this investment thesis. The institutional group owns more than 90% of the stock and has been aggressively accumulating, with analysts urging it to reach fresh peaks. MarketBeat’s data shows institutions buying on balance for 10 consecutive quarters, averaging a $2.8-to-$1 pace over the TTM period, and ramping activity into early calendar Q3 as analyst trends strengthened.
The 27 analysts MarketBeat tracks rate the stock a Moderate Buy, with an average price target of $232.09. Consensus forecasts only modest upside as of late September, but the trend is positive, pushing the stock toward the high end of its range and fresh all-time highs. With analysts having lifted targets and ratings just ahead of the report, the trend is likely to continue in calendar Q4 if operating trends remain strong.
Darden’s Q1 Results Show Steady Growth, Not Weakness
Darden’s Q1 FY2027 results and guidance update are tepid compared to analysts' expectations, but are no less strong for it. Revenue grew by 5.1% to $3.2 billion, slightly below forecasts, on a 3.1% systemwide comp and 2.4% store count increase. All segments reported positive comparable sales, led by LongHorn Steakhouse’s 6.2% gain.
Margin is another area of hidden strength. The company faced margin pressure but offset it to some degree, enabling better-than-expected bottom-line results. Key details include $279 million in cash from operations and $2.05 in adjusted earnings per share, as expected, versus the slight top-line miss. Looking ahead, the company expects steadiness, which is good enough and affirms guidance for 3.1% revenue growth.
Darden’s Uptrend Holds Despite Near-Term Risks
Among Darden’s risks are higher interest rates and their impact on costs and consumers. Higher rates can increase costs while impairing consumer dollars and, by extension, Darden’s revenue-generating capacity. Catalysts include closing Bahama Breeze locations and converting them to higher-yielding formats. This creates upfront cost pressure but also an opportunity to drive growth, comp-store strength, and cash flow.
Darden Restaurants MarketRank™ Stock Analysis
- Overall MarketRank™
- 91st Percentile
- Analyst Rating
- Moderate Buy
- Upside/Downside
- 16.5% Upside
- Short Interest Level
- Healthy
- Dividend Strength
- Moderate
- News Sentiment
- 0.25

- Insider Trading
- Selling Shares
- Proj. Earnings Growth
- 10.31%
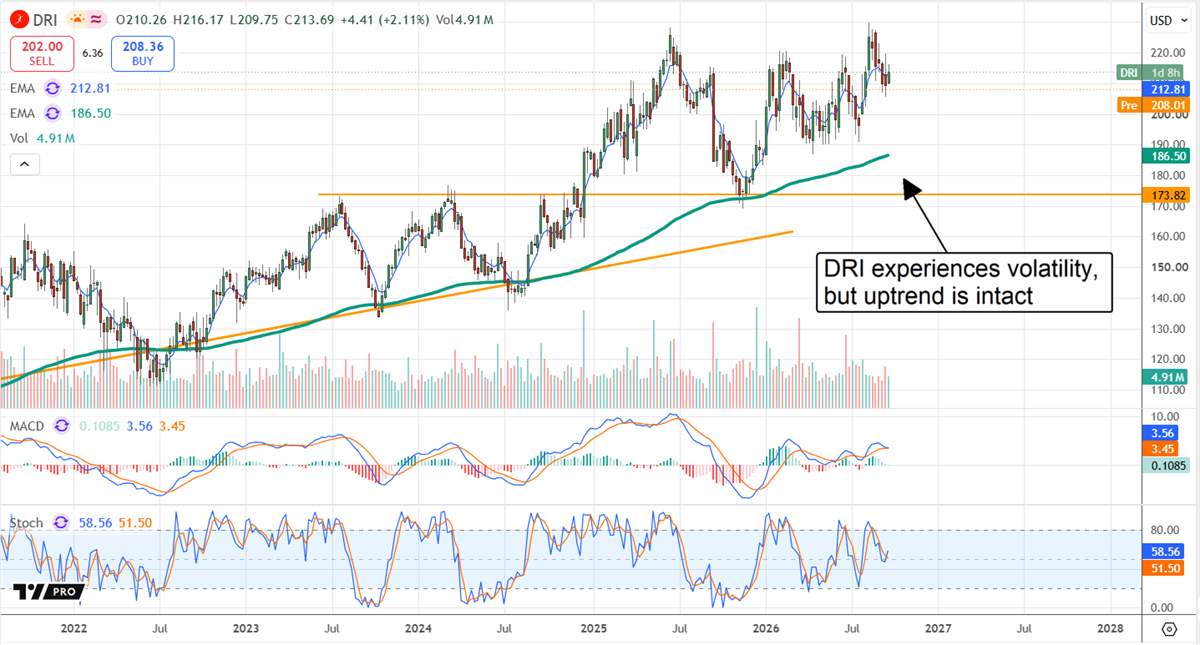
See Full AnalysisStock price action is mixed after the release. The market is pulling back and may deepen the correction, potentially falling to $200 or lower before hitting solid support. Even so, the stock price uptrend remains intact, and institutional investors might view the pullback as a buying opportunity. The question is how soon the rebound may form, and the answer is likely to be soon. Near-term pressures aside, consumers remain resilient, and forecasters expect some strength this holiday season. Retail sales, an indicator of consumer habits, are expected to increase by nearly 5% on average, with restaurants a potential beneficiary of the increased traffic.
Investors often get Olive Garden wrong: its slower growth isn’t an issue, as it remains a pillar of the company’s cash-generating power. Additionally, its size and scale enable supply chain efficiencies, including purchasing power, that many restaurants lack. That combination of brand strength, scale and dependable cash generation helps support Darden’s broader growth and capital-return story even when quarterly results are less exciting.
Before you consider Darden Restaurants, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Darden Restaurants wasn't on the list.
While Darden Restaurants currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Robotics and automation are rapidly becoming essential infrastructure across healthcare, manufacturing, logistics, and many other industries. "Physical AI" is coming. Learn which seven companies are most positioned to benefit as intelligent robots enter the workforce.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
