L3Harris Technologies Today
LHX
L3Harris Technologies
$277.79 -0.64 (-0.23%) As of 10/30/2026 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $232.34
▼
$379.23 - Dividend Yield
- 1.80%
- P/E Ratio
- 25.91
- Price Target
- $343.50
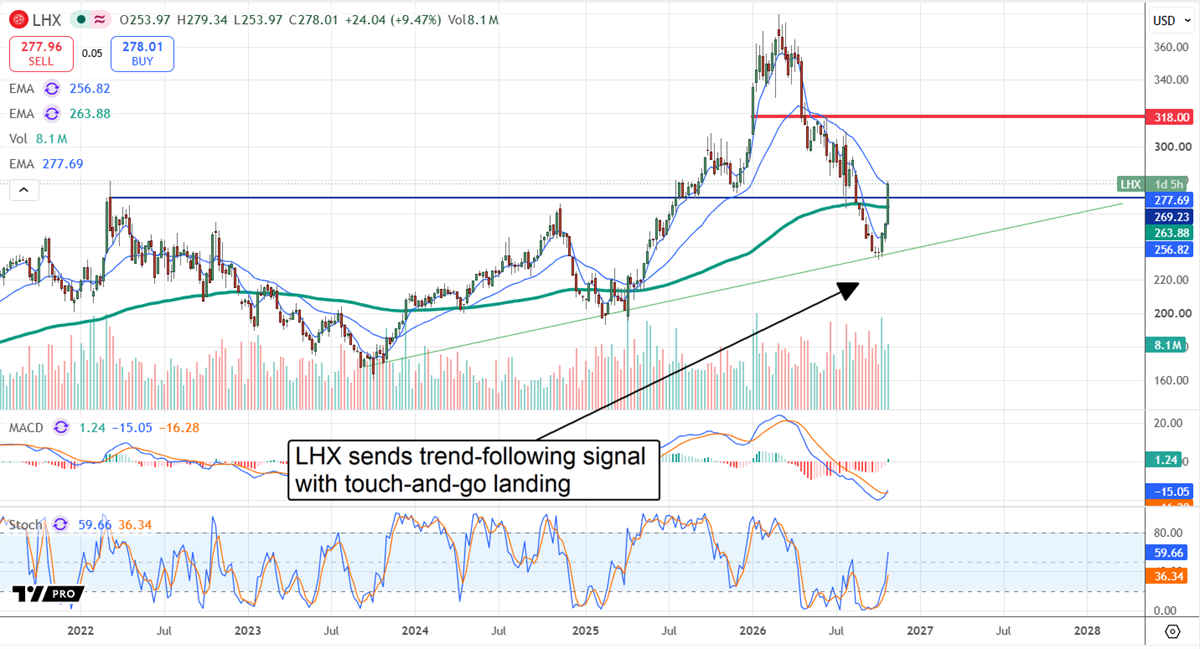
Despite its massive 2026 correction, L3Harris Technologies' NYSE: LHX stock price uptrend remains intact, as recent price action shows.
Backed by a solid earnings report, LHX performed a touch-and-go landing on an existing trend line, produced a strong trend-following signal, and provided an entry point with high double-digit to triple-digit return potential.
The stochastic and MACD indicators support this outlook. Both reflect bullish crossovers near the bottom of their ranges, aligning with the trend-following move and suggesting ample room for the market to run. In this scenario, the next major hurdles are technical resistance in the $300 to $320 range and again at the existing highs, which are likely to be tested within the next 12 months.
L3Harris Q3 Earnings Beat and Record Backlog Strengthen the Bull Case
L3Harris Technologies Stock Forecast Today
12-Month Stock Price Forecast:$343.5023.65% UpsideModerate BuyBased on 19 Analyst Ratings | Current Price | $277.79 |
|---|
| High Forecast | $418.00 |
|---|
| Average Forecast | $343.50 |
|---|
| Low Forecast | $280.00 |
|---|
L3Harris Technologies Stock Forecast DetailsAnalysts’ trends are part and parcel of LHX’s stock price action, with mid-year price target reductions undermining market appetite, but that trend is ending.
Initial analyst responses to L3Harris's Q3 results included cautious commentary on execution hurdles but no price target reductions; ratings were only reaffirmed, helping stabilize the consensus price target.
Down from its peak, consensus forecasts more than 20% upside as of late October, and enough analysts cover the stock to support the forecast.
LHX’s Q3 results were good, revealing broad-based strength, segment-specific strength in Space & Mission Systems, and scale leverage in earnings and cash flow. Revenue grew 7% to $6.1 billion, beating consensus by 270 basis points (bps), driven by a 10.3% gain in Space and Mission Systems, a 3.1% gain in Communications and Spectrum Dominance, and a 4.9% increase in Missile Solutions.
Margin was a strength. The company logged a 200 basis-point improvement in GAAP operating margin, driving a 26.6% increase in operating income and comparable bottom-line strength. Earnings per share of $3.28 beat by more than 1,000 bps, growing by more than 30% year over year (YOY) to a quarterly record. More importantly, cash flow was strong at $1.4 billion, nearly 23% of revenue, and free cash flow (FCF) reached $1.26 billion, driving 195% YOY FCF growth.
Guidance was strong and may be cautious, given the internals and ongoing global conflicts. Management raised its revenue and earnings targets (earnings significantly), putting both above consensus forecasts. For full-year 2026, L3Harris now expects earnings of $12.25 to $12.35 per share, with even the low end exceeding analysts’ $11.90 consensus estimate.
Reasons to believe the guidance may be cautious include $19.3 billion in new orders, a record backlog, and a 3.2-to-1 book-to-bill ratio. This metric reveals new orders are coming in more than three times as fast as old orders are filled.
Capital Returns Provide Lift to LHX Shares
LHX share buybacks have slowed due to government scrutiny, but have not ceased, while the capacity to buy shares has improved. Q3 buybacks helped reduce the share count marginally over the trailing 12 months, with the company returning about 24% of quarterly free cash flow to shareholders through dividends and share repurchases.
Cash, current assets, and total assets all grew during the quarter, while liabilities increased at a slower pace, boosting shareholders’ equity and strengthening the balance sheet. The company also pays a quarterly dividend of $1.25 per share, or $5 annually, providing an additional source of shareholder returns.
Institutions played a role in LHX’s stock price correction and now underpin the upswing. The group owns about 85% of the shares, has an outsized impact on the share price direction, and sold, on balance, in Q1 and Q2 as the share price corrected, then reverted to a bullish posture in Q3 and early Q4 ahead of the release. The likely outcome is that they continue to provide support and buy dips when they occur, but they risk capping upside and selling into rallies as they approach resistance targets at $300, $320, and $360.
What the market got wrong about LHX was its near-term headwinds: they aren’t structural decay or a business implosion, but growing pains that will lead to improved results. The market has started to get the pipeline and backlog right, as shown by clear Q3 strength.
Q3 strength points to sustained growth, acceleration, and cash flow to fuel capital returns. Upcoming catalysts include the potential spin-off of non-core assets gained through acquisitions. These will reduce balance sheet weight, generate cash, and allow management to focus on the growth pillars, including space and next-generation defense applications.
Valuation and short selling are not issues right now. With earnings improving and backlogs swelling, LHX may still offer upside as its recovery gains momentum. Short sellers may have been blamed for the correction, but MarketBeat data shows low single-digit short interest, insufficient to affect price action.
Before you consider L3Harris Technologies, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and L3Harris Technologies wasn't on the list.
While L3Harris Technologies currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Oil still powers the global economy, but AI is reshaping the energy opportunity. Discover seven stocks spanning traditional energy, infrastructure, and next-generation power.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
