Consumer staples stocks offer generational-quality entries in 2026, and none more so than McCormick & Company NYSE: MKC.
McCormick & Company, Incorporated Today
MKC
McCormick & Company, Incorporated
$44.60 +0.46 (+1.05%) As of 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $43.25
▼
$72.41 - Dividend Yield
- 4.30%
- P/E Ratio
- 7.42
- Price Target
- $55.30
The main criticism has long been McCormick's persistently high valuation, typically at the high end of the consumer discretionary range, creating a hurdle for value-conscious investors—but that hurdle is not present this year. Trading at approximately 15x its current-year earnings forecast, the stock is as cheap as it's going to get, and a robust recovery could lie ahead.
MKC’s historical valuation premium reflects its strong position in the grocery store. Consumer headwinds impact choices, but everybody needs flavors to make meals taste good, and that’s where McCormick shines. Its position and branding promote intense pricing power that, in 2026, is compounded by efficiency efforts.
The net result is growth, albeit tepidly due to headwinds, but also wider margins, improved profitability, and capacity for capital returns.
McCormick: Dividend King in the Making
MKC’s premium pricing reflects premium cash flow, enabling a healthy dividend and opportunistic share buybacks. Share buybacks are the lesser of the two returns, offsetting share-based compensation and dilutive activities; the dividend is more substantial. 2026’s stock price discount lifted the distribution yield to the high end of its historical range, above 4%, an attractive payout, especially when combined with the company's growth outlook.
McCormick’s has increased its dividend for nearly 40 consecutive years, putting it on track to be crowned Dividend King. Dividend King is more than a nifty name; it signals dividend stability that can increase total ownership and reduce market volatility.
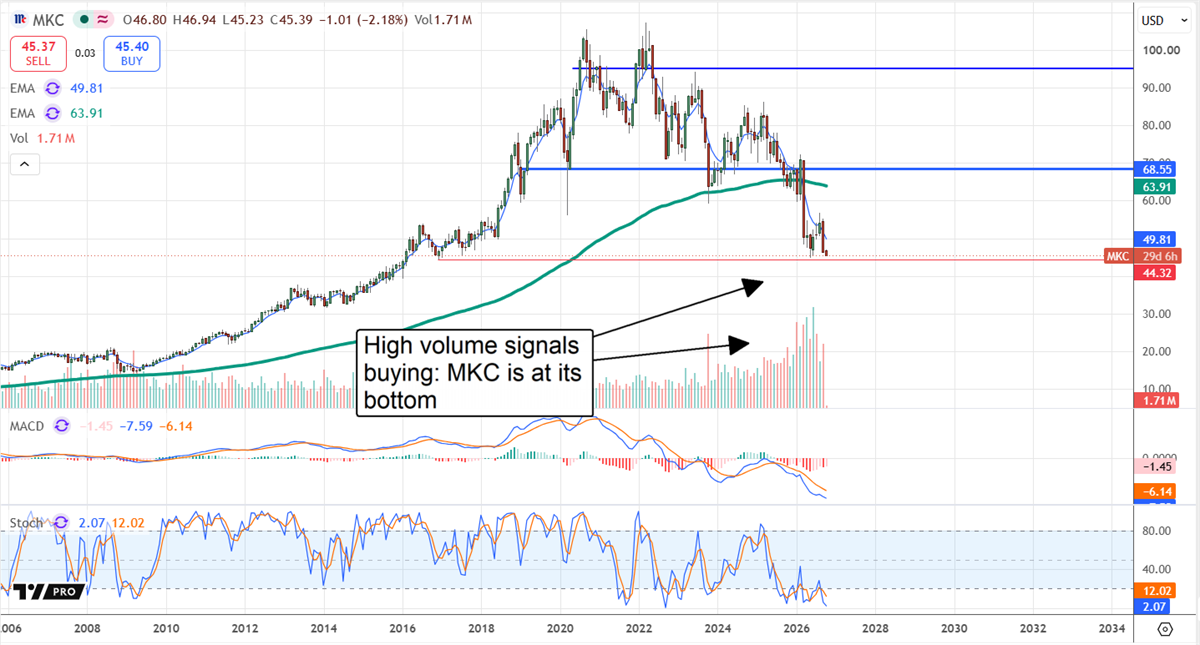
Analysts and institutional trends reflect the deep value present. While analyst trends have been central to MKC’s multi-year price downtrend, they also reflect the stock's long-term potential, with sentiment strengthening in 2026 and again following the Q3 release. Initial analyst responses to the release were cautious, focusing on macroeconomic headwinds and near-term hurdles rather than structural improvements, but they also signaled the potential for a price bottom. As it stands, the rebound could be vigorous, once triggered, because MKC shares trade well below the analysts' lowest target.
Institutional data also suggests a potential price bottom. Institutions, which own nearly 80% of the stock, reduced selling to nearly nothing in Q2 and Q3, ramping activity to multi-year highs as price action reached 10-year lows.
McCormick Executes Strategy, Widens Margins and Outperforms
McCormick had a decent Q3, with the addition of McCormick de Mexico driving most of the gains. Revenue grew 17.4% to just over $2 billion, approximately 200 basis points (bps) better than expected, with gains seen across regions and categories. Organically, revenue grew by 1.9%, underpinned by a 2.2% pricing gain, and foreign exchange added 0.9% to the top line. Segmentally, Consumer grew 24.9%, and Flavor Solutions grew 7.7%, both contributing to margin gains.
Gross and operating margins improved, revealing the strength of McCormick’s efforts. Gross margin improved by 190 bps, and adjusted margin by 180 bps, driven by operational improvements that lifted adjusted operating income 22% year over year. More importantly, earnings and cash flow were stronger than expected, alleviating concerns over dividend payments.
McCormick & Company Has Major Catalysts Ahead
Looking ahead, two catalysts could push McCormick’s market back into a more aggressive posture: Q4 earnings results and a merger with Unilever NYSE: UL. Q4 results will likely reflect additional improvements, healthy cash flow, and capital returns, as well as merger updates. The latest word is that planning is progressing well, with numerous synergies to unlock and completion planned by the middle of next year. The resultant company will be a global flavor powerhouse, more than double McCormick’s current size.
McCormick’s risk lies in the merger. While it will be accretive almost immediately, it carries significant execution and financial risks. First, Unilever must isolate and spin off its foods business, and McCormick must integrate it. While McCormick will retain its U.S. headquarters, operations will shift to the Netherlands to support its global footprint.
The deal will cost McCormick about $15.7 billion in cash. The company plans to use new debt, a bridge loan, and cash on hand, which will strain its balance sheet, but the risk isn’t as big as it may seem. Brands such as Hellmann’s and Knorr, which account for about 70% of Unilever’s food business, could help McCormick service and reduce the additional debt.
The market gets MKC wrong on three counts: the debt, the target, and the reality. The debt is concerning, but it isn’t swelling because of failing business; quite the opposite. McCormick’s business is intact, with improving margins, and uses the debt to expand operations. The target isn’t the brands—though they are important—so much as the distribution network. McCormick can channel its high-growth, high-margin brands to international markets to drive revenue growth and margin expansion, while leaning on Hellmann’s and Knorr for cash flow. The reality is that McCormick isn’t struggling; it's thriving amid headwinds and is well-positioned with ample pricing power.
Before you consider McCormick & Company, Incorporated, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and McCormick & Company, Incorporated wasn't on the list.
While McCormick & Company, Incorporated currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Looking to profit from the electric vehicle mega-trend? Click the link to see our list of which EV stocks show the most long-term potential.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
