Micron’s NASDAQ: MU stock could double and still look undervalued, because the Q4 earnings report for its fiscal year 2026 (FY2026) answered three important questions about the duration of high-bandwidth memory (HBM) shortages, operational leverage, and cash flow.
Micron Technology Today
MU
Micron Technology
$1,053.38 -11.73 (-1.10%) As of 12:41 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $179.61
▼
$1,255.00 - Dividend Yield
- 0.06%
- P/E Ratio
- 23.86
- Price Target
- $1,378.08
Simply put, the market is misjudging HBM demand and how tight capacity remains. Micron says its capacity is already 75% booked through the end of 2027, with supply/demand forecasted to tighten further in 2028.
Longer term, capacity is 35% booked through 2030, a figure backed by signed contracts and likely to increase as the year progresses.
The gains in monetization, operational leverage, and cash flow that the report revealed were impressive, but they won't last forever.
Eventually, the HBM market will stabilize, but the odds are high it won't be until sometime in 2028 or later, with the chances of an even later recovery increasing each quarter.
In Micron's fiscal Q4, gross margin nearly doubled year over year, operating margin more than doubled, operating cash flow jumped 7.7x to more than 81% of revenue, and net income and adjusted earnings per share grew by 11x. Looking ahead, management expects an even stronger year and issued guidance for fiscal Q1 well above consensus forecasts.
Micron’s Blowout Quarter Shows AI Memory Demand Is Still Accelerating
Micron had a robust quarter with demand supporting higher pricing, driving revenue gains and wider margins. Net revenue rose to $54.23 billion, up 379.1% year over year (YOY) and 30.8% sequentially, more than 500 basis points (bps) above expectations, driven by strength in both DRAM and NAND markets. NAND strength is especially important because it stores the vast amounts of data AI systems generate and use, pointing to broader, sustained AI demand beyond HBM. DRAM, which includes HBM, grew 27% sequentially and 252% for the year, while NAND grew 42% sequentially and 274% for the year.
All segments produced triple-digit growth, led by the Core Data Center business. It grew 11.4x YOY, followed by 4.75x growth in Automotive and Embedded, 3.6x in Cloud Memory, and 3.5x in Mobile and Client.
Micron’s guidance was strong, which has positive implications for analyst estimates. While strength was expected, the size of the beat suggests the group will need to adjust its Q1 and full-year forecasts and will likely do so again as the year progresses, keeping the bullish trends intact. The likely outcome is that Micron continues to show strength, outperforms its guidance, and raises its full-year forecast before year-end.
Analysts' Conviction in Micron’s Bull Case Strengthens
Analysts responded enthusiastically to the release, highlighting top-line strength and durability signals and reaffirming bullish ratings or raising price targets. As it stands, the 45 MarketBeat tracks show strong conviction in the Moderate Buy rating, with an 88.8% Buy-side bias, no Sell ratings logged, and an uptrend in price targets. The consensus forecasts about 30% upside from September’s closing price, but the trend matters, pushing the high end to $2,000, nearly 100% upside when reached.
Institutional trends suggest an upside movement is brewing. The group owns more than 80% of the shares and reverted to buying in Q3 after posting mixed activity in Q2. Their buying aligns with the August price bottom and subsequent rebound, setting the stage for the uptrend to continue now that fiscal Q4 results and forward guidance have been released. More importantly, the group signals a floor for price action, limiting downside risk.
Micron’s Balance Sheet Derisks the Outlook
Investors should not overlook Micron’s balance sheet. Improved leverage, margin expansion, and cash flow have driven significant improvements since the previous quarter and year. Key details include cash up 4x to over $38 billion; higher investments, inventory, and receivables; current assets up 3x YOY; and total assets more than doubling.
Other key details include higher current and total liabilities, but growing more slowly than assets; massive debt reduction; and improved cash flow capacity and shareholder equity. Equity, the measure of shareholder value, grew by 38% sequentially and more than 2.5x YOY, and is expected to continue expanding in the coming year.
Micron’s price action was iffy in after-hours trading following the release. Shares fell on the news, revealing a market expecting strength. However, the market did not fall far, suggesting buyers were waiting, if not aggressively eager, to buy on good news.
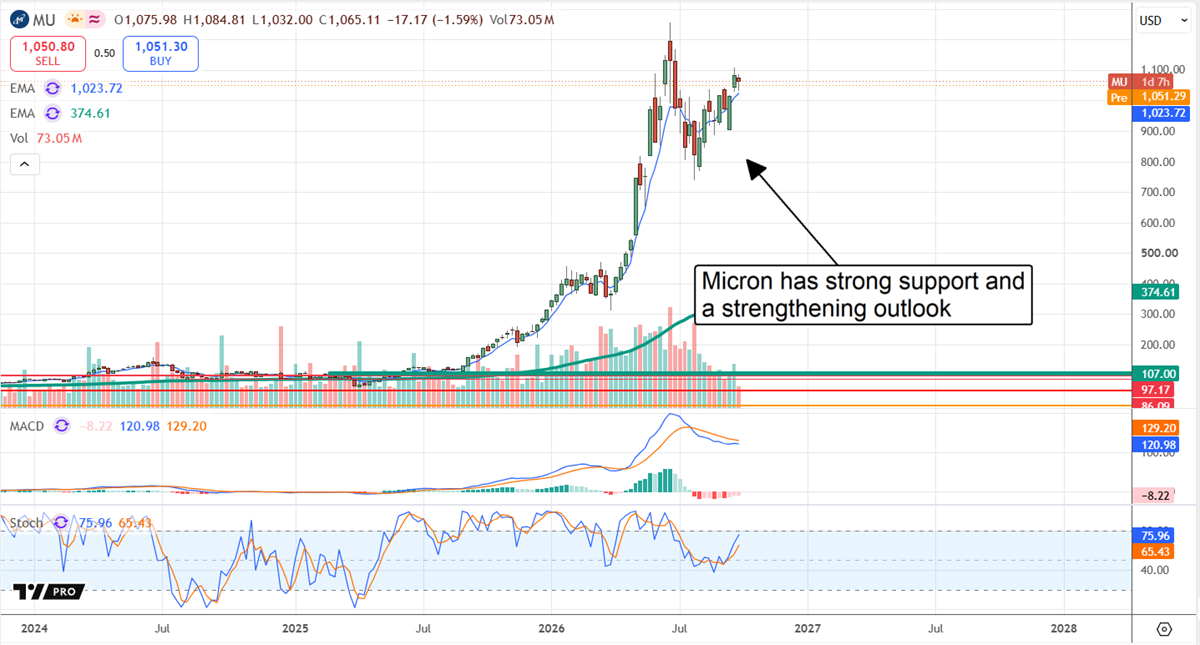
The likely outcome is that MU continues consolidating within its existing range, potentially gaining traction by year’s end. The biggest risks are macroeconomic, including inflation, higher interest rates, and the cost of capital for expansions, but cash and cash flow mitigate them. Micron is well-positioned to execute its strategy in 2027, including plans to accelerate capacity increases.
Before you consider Micron Technology, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Micron Technology wasn't on the list.
While Micron Technology currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Discover the next wave of investment opportunities with our report, 7 Stocks That Will Be Magnificent in 2026. Explore companies poised to replicate the growth, innovation, and value creation of the tech giants dominating today's markets.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.

