NVIDIA Today
$225.07 +0.49 (+0.22%) As of 04:00 PM Eastern
- 52-Week Range
- $164.27
▼
$236.54 - Dividend Yield
- 0.44%
- P/E Ratio
- 28.45
- Price Target
- $324.14
forecast to double its chip volume next year strengthens an already bullish growth outlook for the company and its stock. Rapid computing expansion, underpinned by sovereigns and enterprises, coupled with product launches, creates
an ecosystem flywheel and virtuous cycle that could keep NVIDIA growing at a solid pace well into the future.
For NVIDIA investors, this means the potential for persistent upgrades to revenue and earnings targets, sentiment, and price targets—a bullish cycle for the stock price outlook. As it stands, 55 analysts cover this stock; new coverage is still emerging, and only one Hold rating. Price targets are the operative factor here, with the consensus up more than 50% over the trailing 12 months and forecasting about 45% upside relative to late-September price action. A 50% upside isn’t a triple-digit gain, but it is a step in the right direction and the trend matters. Summer revisions push the high end into the $515 range, representing more than 100% upside from the critical resistance point—and it could still prove to be a low-ball estimate.
NVIDIA’s Valuation Is Disconnected From AI’s Reality
NVIDIA’s latest growth outlook also reinforces the case that it could retain its dominant position in AI. Advanced Micro Devices is a solid up-and-comer, positioned for its own explosive growth cycle, but NVIDIA remains the dominant player, particularly for the most advanced workloads. With this in mind, the valuation gains suggested by the price multiples become clearer.
NVIDIA’s price-to-earnings (P/E) ratio aligns with the S&P 500 average as of late September, but fails to price in the company’s dominance. Trading at about 24x current-year earnings, the market puts no premium on it, and no growth expectation is priced in. Looking forward, the discount deepens to only 10x earnings within two years, and the 10-year forecast suggests this stock trades at pennies on the dollar, about 5x earnings, revealing a structural disconnection with the fundamental outlook.
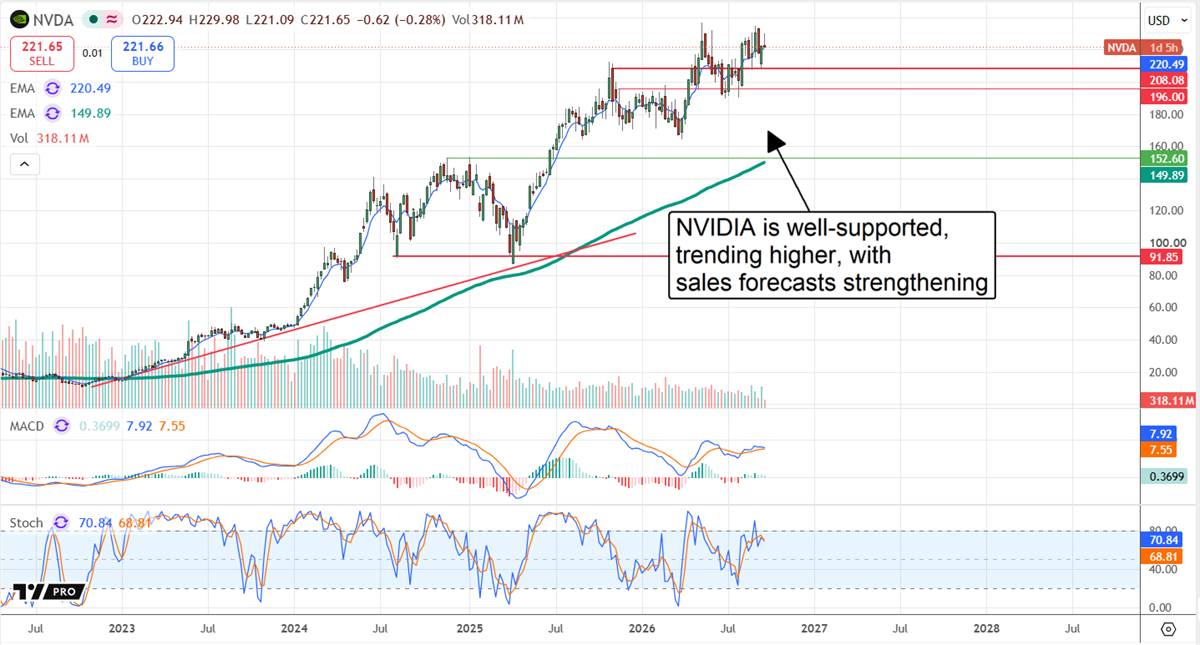
If NVIDIA continues to fire on all cylinders and grows into or exceeds its earnings forecast, its stock price could rise by several hundred percentage points over the next few years, potentially as much as 500%.
The trigger for this move could come from subsequent earnings reports and continued progress with Vera Rubin. The platform is already in full production, with NVIDIA reporting production shipments beginning in August and purchase orders from every major hyperscaler, AI cloud and system original equipment manufacturer (OEM). That rollout could unlock another wave of data center construction. Many investors get it wrong that all the data centers are being built now; many, including much of Oracle’s NASDAQ: ORCL backlog, are back-ended and waiting on the next-gen performance Vera Rubin promises.
Which Companies Benefit Most From NVIDIA’s Sales Forecast?
The companies benefiting most from NVIDIA’s sales explosion include the OEMs that put NVIDIA’s hardware and software into commercialized packages. While one GPU is powerful, AI requires servers, server clusters, rack clusters, and buildings filled with racks to work. Companies deploying NVIDIA technology at scale include Dell Technologies NYSE: DELL, Hewlett Packard Enterprise NYSE: HPE, Super Micro Computer NASDAQ: SMCI, and Cisco Systems NASDAQ: CSCO, all of which reflect strength in their numbers.
NVIDIA Has Risks, But the Market Is Getting Them Wrong
NVIDIA’s biggest risk is credit-related. It's not that NVIDIA’s credit quality is eroding so much as the amount of future sales it is self-financing. NVIDIA customers could undercut the revenue outlook with capital expenditure (CapEx) reductions, but this is unlikely, given the need for capacity and Wall Street insiders' moves to securitize GPUs. Securitizing GPUs is a bigger move than some give credit for and is likely to unlock additional funding as initial investments begin paying off.
NVIDIA MarketRank™ Stock Analysis
- Overall MarketRank™
- 99th Percentile
- Analyst Rating
- Buy
- Upside/Downside
- 44.3% Upside
- Short Interest Level
- Healthy
- Dividend Strength
- Weak
- News Sentiment
- 0.81
- Insider Trading
- Selling Shares
- Proj. Earnings Growth
- 65.73%
See Full AnalysisThe offset is slowing the advance of frontier modeling. Slowing AI’s advance removes the industry’s biggest hurdle: cash flow. It also enables monetization of existing AI infrastructure, strengthens balance sheets, and de-risks the outlook for NVIDIA’s future sales.
The market gets it wrong when it assumes that NVIDIA’s periodic growth slowdowns signal deteriorating demand. While supply bottlenecks and product transitions impact quarterly results, underlying demand remains robust, and this is all without the impact of China. Meanwhile, the company is selling its chips within full systems, deepening and widening its moat with vendor lock-in, while advancing AI at all levels of the stack. That enables incredible pricing power, stable margins, and ample cash flow.
Cash flow is critical, as NVIDIA is not only profitable but also self-funding growth, investing in its supply chain, future capacity, and new technology. Equally important, NVIDIA also has capacity for capital return, including dividends and share buybacks, and is on pace to accelerate them over the coming year.
Before you consider NVIDIA, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and NVIDIA wasn't on the list.
While NVIDIA currently has a Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
The AI wave will soon hit public markets with Anthropic and OpenAI set to go public later this year. However, you don't have to wait to invest. This report shows seven AI stocks that you can buy today while the big model providers get ready to go public.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
