ON Today
$34.29 -0.41 (-1.18%) As of 11:52 AM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $26.36
▼
$51.08 - P/E Ratio
- 23.29
- Price Target
- $43.96
Investors were right to look past On Holding's NYSE: ONON massive Q3 earnings beat to the core metrics, but they were wrong to drive the stock price down 7% in early premarket trading. While the headline was robust, it was driven by tariff refunds, and the underlying results failed to provide a wow factor, prompting some investors to sell the news despite the obvious strengths. Those include an improving gross margin and the capacity to sustain a premium position in a highly discounted merchandising environment, reasons for investors to buy the dip.
Competitors such as Nike NYSE: NKE are leaning hard into markdowns and promotions; On Holding is managing inventory, sustaining a positive supply/demand balance, and realizing it on the bottom line. Critics point to lackluster Q3 wholesale results, but they miss the point. On Holding helps sustain its position by limiting wholesale access, which drives traffic to its higher-margin direct-to-consumer (DTC) business and accelerates bottom-line growth.
On Holding Had a Good Quarter, Just Not Strong Enough to Trigger Buyers
On Holding had a good quarter, growing revenue by 17.2% reported and 17.8% on a currency-neutral basis. The company reported strength in all channels and regions, led by a 31.1% advance in Asia-Pacific (APAC). Emerging Markets, Europe & Africa (EMEA) was also strong, up by 17.9%, while the Americas trailed with 12.4% growth. Segmentally, DTC was the bright spot, up 24.8%, followed by 13.2% growth in Wholesale, both on a currency-neutral basis. By category, Accessories led with a 39.2% reported gain, while Apparel rose 38.7% and remains central to the growth and margin outlook.
Margin news is mixed, but gross profitability remains strong even excluding tariff refunds. Highlights include a roughly 1-percentage-point improvement in gross margin to 66.9% excluding refunds, but higher operating costs partly offset it. The adjusted EBITDA margin excluding refunds contracted slightly, to 21.9% from 22.6%, offsetting the top-line strength, but not enough to alter the fundamental outlook: On Holding is financially stable, growing, and widening gross margins. While guidance includes the impact of tariffs, management left revenue targets unchanged, expecting growth in the low 20% range and raising its 2026 gross margin outlook to about 66% excluding refunds.
Balance sheet highlights reflect On Holding’s strength and growth. Cash is up about 30% year-to-date, alongside higher receivables and inventories, which have increased current and total assets. Financial debt remains modest, although the company carries significant lease liabilities. Cash exceeds its financial debt. On Holding is in a nimble financial position and can sustain its growth in future quarters.
Optimistic Analysts Express Near-Term Caution: Stock Drops
Initial analyst responses are optimistic, highlighting growth, cash flow, and brand positioning, with the brand continuing to gain share in key markets. They also point to slowing growth and inventory, which rose more than 18% in the first three quarters, raising doubts about new product launches. The risk is that new launches won’t go as planned, leaving the company in a position to mark down products and risk its premium position or take a write-off and dispose of inventory.
What naysayers may be getting wrong is On Holding’s strategy, which includes building inventory to meet expected demand, which appears sufficient. While no unit sales figures were given, executives said first-week Cloudsurfer 3 sell-through exceeded four times that of the Cloudsurfer 2 launch. Assuming the market follows through on the signal, On Holding may be able to manage its inventory to lower levels as the initial demand surge subsides.
ON Stock Forecast Today
12-Month Stock Price Forecast:$43.9328.36% UpsideModerate BuyBased on 31 Analyst Ratings | Current Price | $34.22 |
|---|
| High Forecast | $73.00 |
|---|
| Average Forecast | $43.93 |
|---|
| Low Forecast | $20.00 |
|---|
ON Stock Forecast DetailsJohn Kernan at Cantor Fitzgerald initiated coverage of ONON with an Overweight rating and a $46 price target, about $2 above the current consensus target of $44, reinforcing bullish analyst sentiment. In total, the analysts' data reflects a largely positive outlook: Of the 31 analysts tracked by MarketBeat, 25 have Buy or Strong Buy ratings, supporting the Moderate Buy consensus rating. Coverage has increased sharply in 2026, and consensus price targets have recently edged higher.
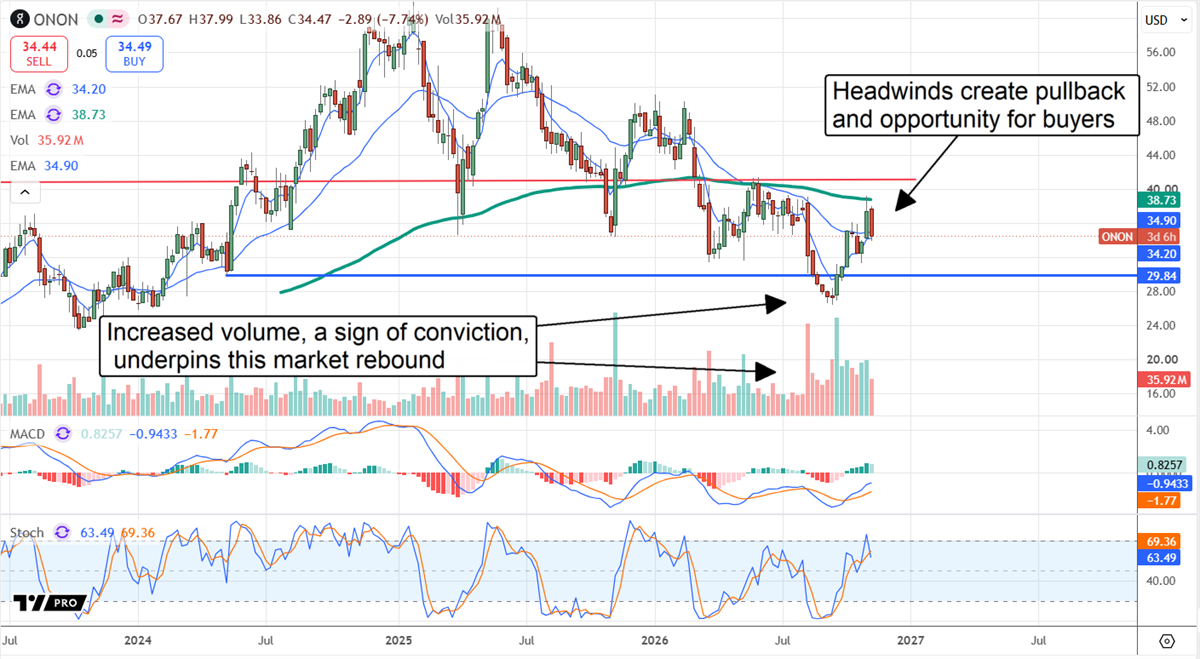
Price action on Nov. 10, following the earnings report, was as bearish as the early indication suggested. Under pressure, shares opened about 7.5% below the prior day's close and finished down 7.54%. The move shows caution, but the stock had rebounded from its late-October lows ahead of the report. Lower lows are always possible, and the post-earnings decline leaves that reversal unconfirmed. A volume increase underpinned the earlier rebound, a sign that actual buyers, not some near-term market fluctuation, drove it. The low valuation, about 18x projected 2027 earnings, is among the triggers.
On Holding’s biggest risk lies in the consumer and fashion cycles. Consumer habits underpin the ebb and flow of growth cycles and are impaired in 2026. Digging deeper, consumer habits, including fashion, are often fickle, leaving the company at risk of disruption. Investors concerned about disruption need only look at Nike, whose self-inflicted wounds helped enable On Holding’s success.
Before you consider ON, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and ON wasn't on the list.
While ON currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
MarketBeat just released its list of the 7 hottest IPOs expected to hit Wall Street in 2026. See which companies are preparing to go public and why investors are watching closely.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
Like this article? Share it with a colleague.
Link copied to clipboard.
