onsemi’s NASDAQ: ON deal to acquire Ferric is another step toward cementing its position as a computer vision system original equipment manufacturer (OEM) for robotics, autonomous vehicles, and the Internet of Things (IoT).
Ferric specializes in power delivery for AI processors and holds dozens of patents centered on its highly efficient technology. It takes power control off the motherboard and puts it directly on the semiconductor using thin-film technology. The net result is 50% to 70% smaller size and lower power usage, enabling more critical computing components and power at the edge, where computer vision systems handle a firehose-sized stream of real-time data.
Ferric fits cleanly into onsemi’s strategy. Its technology seamlessly integrates with onsemi’s primary power lines, enabling on-substrate power handling and delivery directly to the computer vision processor. For OEMs, this means onsemi is a one-stop shop, capable of powering sensors and core system compute efficiently while providing an end-to-end computer vision system.
With its acquisition of Synaptics NASDAQ: SYNA, onsemi would add processing and connectivity to its existing sensor and power technologies, broadening the range of components it supplies for automated machines. Ferric would strengthen power delivery across that portfolio while also expanding onsemi’s offering for AI data centers, where its technology can reduce the space needed for power components, cut power losses, and reduce heat.
onsemi Posts Beat-and-Raise Quarter: Signals Bottom in Stock Price
onsemi had a solid Q3, reporting $1.72 billion in net revenue, an 11% year-over-year (YOY) gain. The take outpaced consensus by a slim margin, which matters because the bar was set high, with expectations having crept higher all year.
onsemi Today
$70.54 -2.06 (-2.84%) As of 02:45 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $44.56
▼
$134.92 - P/E Ratio
- 41.01
- Price Target
- $95.66
Growth was driven by gains in all segments, led by a 21% increase in the PSG (power control) segment. By end markets, AI data center was strongest, growing 39% sequentially and 175% YOY, underscoring onsemi’s importance to the industry and the longevity of the AI industry at large. These results suggest demand for AI data-center infrastructure remains strong, despite concerns that the buildout is slowing or falling off track.
Other key details include margins, which expanded with revenue leverage. Gross and operating margins improved by over 100 basis points, driving accelerated earnings growth throughout the stack. Cash from operations grew 23% to $516 million; free cash flow grew 31% to $489 million, about 28% of revenue; and adjusted earnings per share (EPS) grew 43% to 90 cents. Cash flow details are also important because they derisk the Ferric acquisition: the company plans to use cash on hand and appears to have plenty.
Guidance is a trigger for accumulation, given the stock price’s massive correction and support signals. It included a hot read on revenue and earnings, likely to be cautious given the trends and business momentum.
Analysts Focus on Near-Term Headwinds, Lift Revenue and EPS Targets
Analysts' initial responses to the release were mixed, reflecting strong results and caution centered on onsemi's automotive segment. The segment faces near-term pressures tied to consumer habits and product wind-downs as OEMs end existing programs and gear up for new ones. What the bears fail to recognize, however, is that the company’s current strengths support a robust outlook, and the automotive market won’t be sluggish forever. Next-gen product lines are expected to enter production next year and ramp in the back half, pointing to sustainable, accelerating strength over the next four to six quarters.
Collectively, analysts are raising revenue and earnings targets while lowering the stock price forecast, sending mixed signals to the market. The group shows high conviction in the Moderate Buy rating; there is a strong bullish bias, with the consensus price target forecasting about 35%. However, downward pressure on price targets may impair price action in Q4, all the while setting the stage for catalysts next year.
Catalysts for ON could include persistent strength in the AI market, improvement in the automotive market, outperformance and accelerating growth, cash flow, and capital returns.
onsemi’s capital return consists entirely of share buybacks, and it is aggressively reducing the share count. Q3 activity resulted in a 2.62% reduction in the trailing 12-month count, with the capacity to continue reducing the count in upcoming quarters. Year-to-date balance sheet highlights include increased cash, current, and total assets, as well as steady equity, despite a reduction in the share count and liability increases tied to expansion plans and acquisitions.
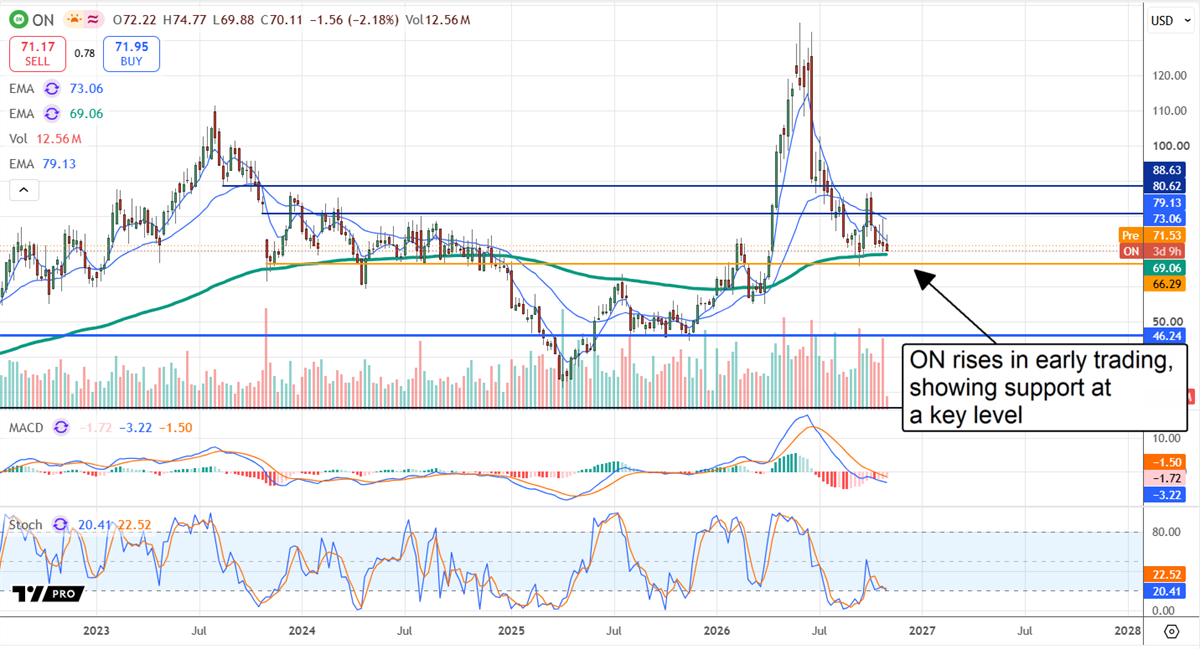
Stock price action following the release was more favorable than the analysts' response, with shares up approximately 2.5% premarket. The move signals a market floor, also reflected in the stochastic and MACD indicators, which suggest the market is accumulating at these low levels and could rebound soon. Institutions are key; they sold in Q3, helping the stock price downtrend, but shifted back to accumulation in early Q4. Assuming they continue, the stock price will move higher over time, as institutions own nearly 98% of the shares.
Before you consider onsemi, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and onsemi wasn't on the list.
While onsemi currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Looking for higher dividend income in 2027? Discover seven high-yield dividend stocks with attractive payouts, proven dividend histories and growth potential.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
