PepsiCo NASDAQ: PEP isn't without hurdles, but it’s doing what long-term investors need: generating cash flow and returning capital to investors.
PepsiCo Today
$128.34 +4.61 (+3.73%) As of 04:00 PM Eastern
- 52-Week Range
- $123.47
▼
$171.48 - Dividend Yield
- 4.61%
- P/E Ratio
- 16.82
- Price Target
- $150.20
The opportunity in 2026 is an historically low valuation and price point, compounded by an historically high yield. While high bond yields have played a role in PepsiCo's stock price decline, investors should consider that bond yields won’t stay high forever, and PEP won't remain low.
The same money invested in 10-year bonds will yield a little more than 5% over time, but that’s it; PepsiCo’s stock price will increase over the next decade even while it pays its dividend.
In this scenario, investors buying PEP in Q4 2026 can lock in an approximately 4.7% yield and an outlook for significant capital appreciation. At about 15x forward earnings, PEP stock trades at a 40% discount to historical norms, is deeply oversold, and is set up for a long-term price recovery. Recovering its premium alone puts the stock near existing highs; add in the growth outlook, and it's set up to hit fresh highs.
PepsiCo’s Diversified Business and Strategic Shifts Drive Growth
PepsiCo had a decent Q3, with revenue up 5.6% year over year (YOY) and above consensus. Growth was underpinned by a 3.1% organic increase, driven by volume and pricing. Acquisitions added another 1.7%, and the remainder was a foreign exchange-related tailwind.
Regionally, North America was the weakest, with PepsiCo Foods flat and Beverages up 5%. International was the bright spot, with International Beverages up 8%, and EMEA, Latin America, and Asia-Pacific Foods all growing by at least that much.
Margin news was mixed, but sufficient to keep buy-and-hold investors interested, given the low share price. Margin expanded at the headline, but was impacted by tariff refunds. Internally, core margins contracted, but less than expected, leaving the adjusted earnings per share (EPS) up by about 2%.
That EPS growth beat expectations by 5 cents, helping to offset the weak guidance. PepsiCo revised guidance, firmed the revenue target and trimmed earnings projections, which isn't typically good news. However, market responses suggest investors expected worse, making lower share prices unlikely.
Analysts and Institutions Limit PepsiCo’s Downside in Q4
Analysts' responses to the release were muted, citing North American weakness and lowered profit targets. As it stands, the 20 analysts tracked by MarketBeat are strongly aligned in their consensus Hold rating; the data indicate a bullish bias, and price targets highlight deep value. While consensus suggests a 20% upside, PEP trades about 5% below even the lowest analyst price target.
Institutional activity aligns with the thesis that PepsiCo’s stock price is bottoming. Institutions own a solid 73% of the stock and have accumulated for nine consecutive quarters. More importantly, buying activity ramped up in Q3 as price action hit long-term lows and is likely to remain bullish because of the market disconnect. Retail traders are overreacting to the GLP-1 threat, ignoring the company's International strength, turnaround efforts, and strategic shifts to capture consumer habits.
Capital Returns Help Put the Floor in PepsiCo’s Share Price
PepsiCo's capital returns are attractive, including a high dividend yield and share buybacks. Share buybacks aren’t aggressive, but reduce the count incrementally each quarter. Highlights from Q3 include a slight YOY reduction in buybacks, but this was tied to the share price, which enabled steady share count reduction at a lower cost. Looking ahead, PepsiCo is likely to continue reducing the count at the same pace while increasing its dividend distribution. The company is a Dividend King and unlikely to end its streak anytime soon.
Chart price action is yet another indicator that PepsiCo’s stock price is at a floor. Price action broke through critical support ahead of the release but is rebounding with favorable indicators. MACD reveals divergence from price, while Stochastic shows an incredibly oversold market.
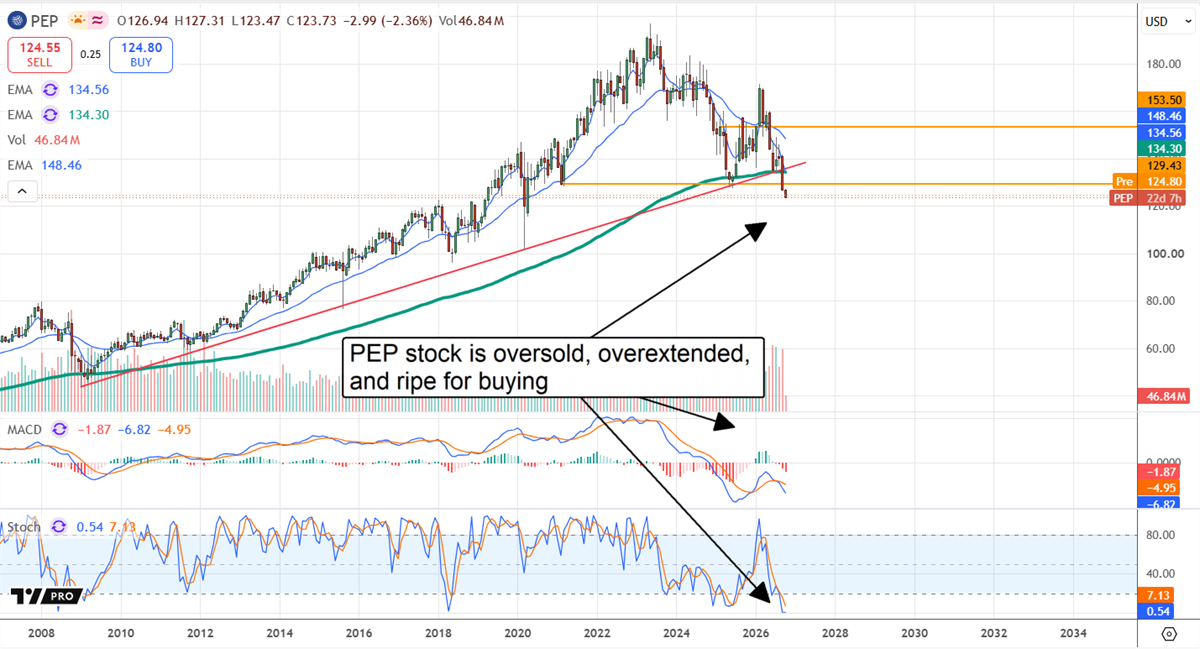
The only thing missing is a strong catalyst, and there are several brewing. Turnaround efforts include a massive North American portfolio reset, with a 20% stock-keeping-unit (SKU) reduction that streamlines operations and improves shelf spacing, plus value pricing. The efforts are already showing traction, as shown by the sequential improvement in Q3 versus Q2.
PepsiCo’s risks are primarily external, including consumer habits, regulatory hurdles, and legal headwinds. Consumer habits are affecting North American business but have not yet triggered structural declines; turnaround efforts are underway. Regulatory hurdles and legal pushback are bigger issues, with local and national agencies targeting soda companies as unhealthy, and recalls hurting consumer awareness.
Before you consider PepsiCo, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and PepsiCo wasn't on the list.
While PepsiCo currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
The AI boom extends far beyond the biggest tech names. Discover 10 companies supplying the memory, storage, networking, semiconductor manufacturing, and power infrastructure that make AI possible. Learn where the next wave of AI investment opportunities may emerge—and the key risks investors should watch as the global AI buildout accelerates.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
