Overlooked stocks worth buying aren’t easy to find, as, usually, when the market ignores a stock, it's for a good reason. However, a sure sign that an unloved or under-reported name is a winner is high institutional ownership. Institutions are unlikely to invest in a risky, cash-burning name without a reason, so following their lead is often profitable.
Other qualities that strengthen the bull case for an overlooked stock are value, cash flow, and yield, which are the only things that really matter—even high-profile tech stocks move on cash flow and yield; it is the aggressive, often explosive growth, wild forecasts, and emotional markets that make their stock prices move so much.
Archer-Daniels-Midland: A Cheap Dividend With a Giant Moat
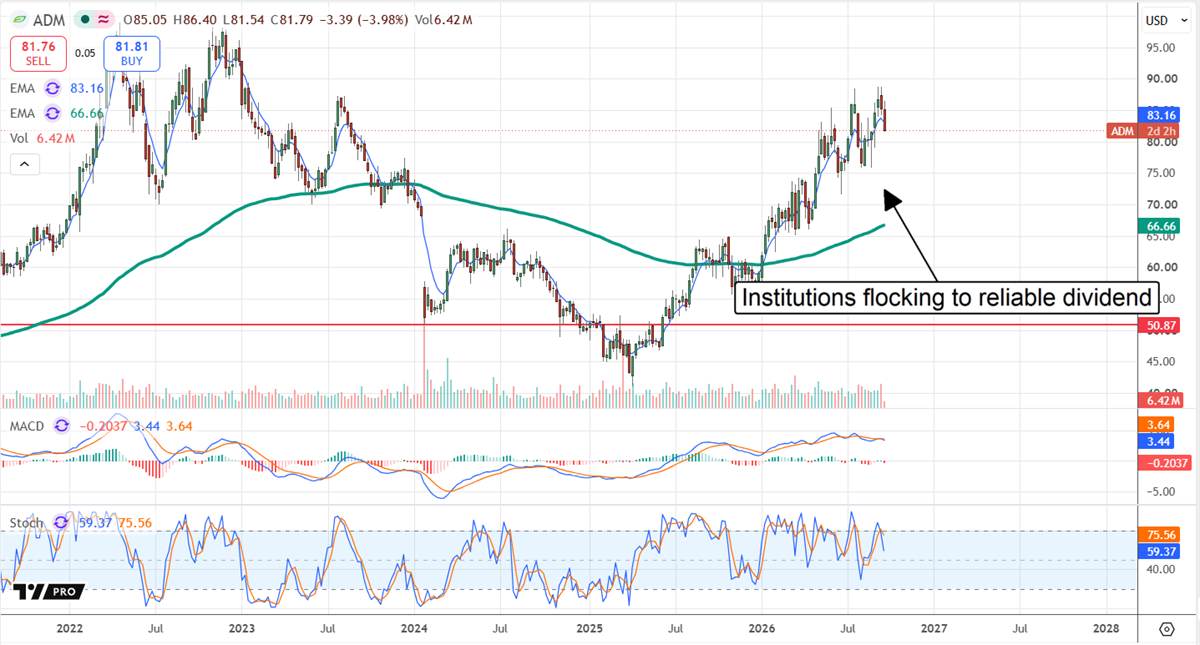
Archer-Daniels-Midland NYSE: ADM is an often-overlooked company because of its non-flashy, low-margin, commodity-driven business. Investors often overlook the company’s moat and countercyclicality, which enable wider margins and lower working capital during commodity downturns.
Archer Daniels Midland Today
ADM
Archer Daniels Midland
$81.22 -0.66 (-0.81%) As of 09/25/2026 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $55.58
▼
$88.75 - Dividend Yield
- 2.56%
- P/E Ratio
- 22.25
- Price Target
- $79.67
The strength is tied to the business model, which relies on commodities but not necessarily on higher commodity prices. ADM grinds and crushes nuts and seeds, converts beets and sweet potatoes into sugar, and provides many other services, making money on the spread.
The moat comes from scale: ADM’s global network includes approximately 750 collection and processing facilities, giving it a vast infrastructure footprint that would be extremely difficult for a competitor to replicate.
ADM is a good buy because of its cash flow, dynamic capital allocation model, and ability to sustain annual dividend increases. The company is laser-focused on its dividend-growth trajectory, which includes 53 consecutive years of annual increases. Share buybacks are also in the picture, coming at opportunistic times when cash flow allows. Eight analysts rate ADM as a consensus Hold, while institutions own nearly 80% of the stock and are aggressively accumulating.
Sanmina: The Muscle in Tech Manufacturing
Sanmina NASDAQ: SANM is an often overlooked stock because it works behind the scenes, providing outsourced manufacturing solutions to the tech industry. The low-profile business lacks product recognition, even though it makes devices for names such as Advanced Micro Devices NASDAQ: AMD. Additionally, its mid-cap size and low growth keep it out of the spotlight, which helps keep valuations low.
Sanmina Today
$224.77 +2.89 (+1.30%) As of 09/25/2026 04:00 PM Eastern
- 52-Week Range
- $111.52
▼
$288.68 - P/E Ratio
- 40.21
- Price Target
- $198.33
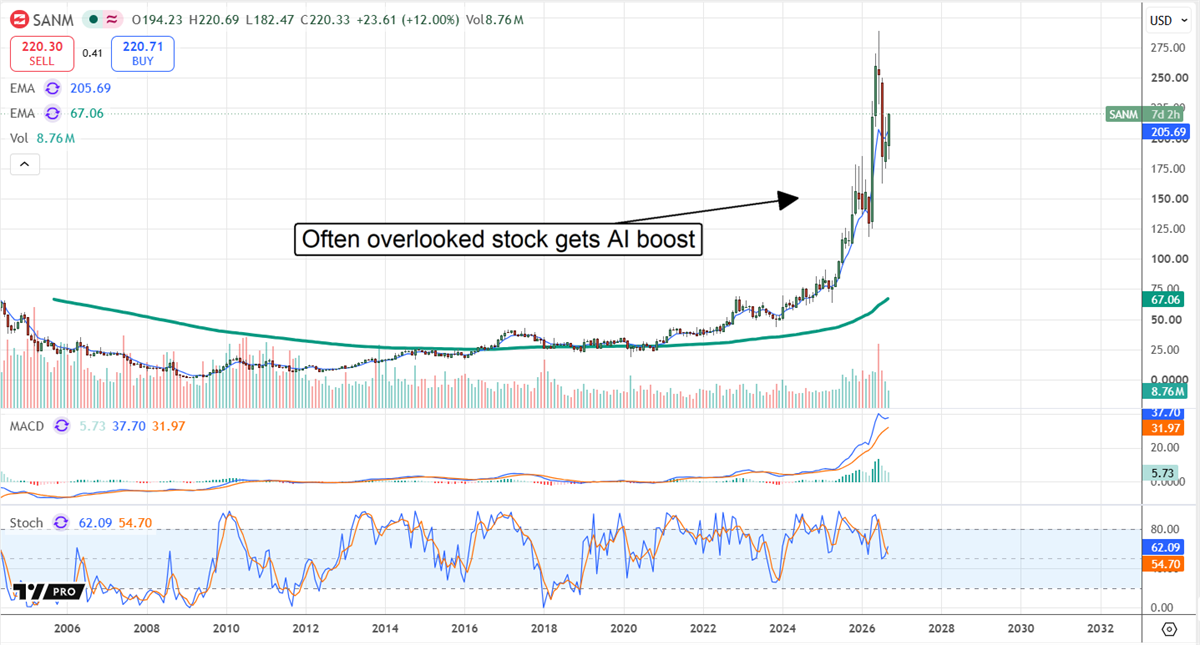
This year, the market is underestimating the impact of AI on this company. Sanmina is leaning into AI by focusing on higher-margin, higher-tech solutions. Catalysts include AMD’s MI450 line and Helios rack-scale systems, of which Sanmina is a preferred manufacturing partner. These programs are expected to drive significant growth over the coming year.
The company doesn’t return significant capital to investors today, choosing to invest in its future, but it may soon, given the business shift. Sanmina is transitioning from a legacy tech provider into an AI-critical name with a deep moat. The moat is built on vertical integration, product penetration, a global footprint, and high switching costs, which create sticky, long-term client relationships. Institutions own more than 90% of this stock and are accumulating aggressively.
SANM’s price action is driven by its latest results. They reflect its position in the AI ecosystem, which the stock has yet to price in. Caution entered the outlook over the summer but did not change it significantly, with analysts' trends pointing to the high-end price target of $260 with higher highs likely. The technical signal is MACD convergence, suggesting existing highs will be retested if not exceeded.
Delek US Holdings: A Structural Turnaround With Macroeconomic Tailwinds
Delek US Holdings NYSE: DK is often overlooked due to its higher-than-average valuations and correspondingly lower yields. However, the narrative is changing in 2026 as margin improvement efforts pay off and structural tailwinds emerge.
Delek US Today
DK
Delek US
$67.84 +0.93 (+1.39%) As of 09/25/2026 03:59 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $25.85
▼
$82.27 - Dividend Yield
- 1.50%
- P/E Ratio
- 19.06
- Price Target
- $65.45
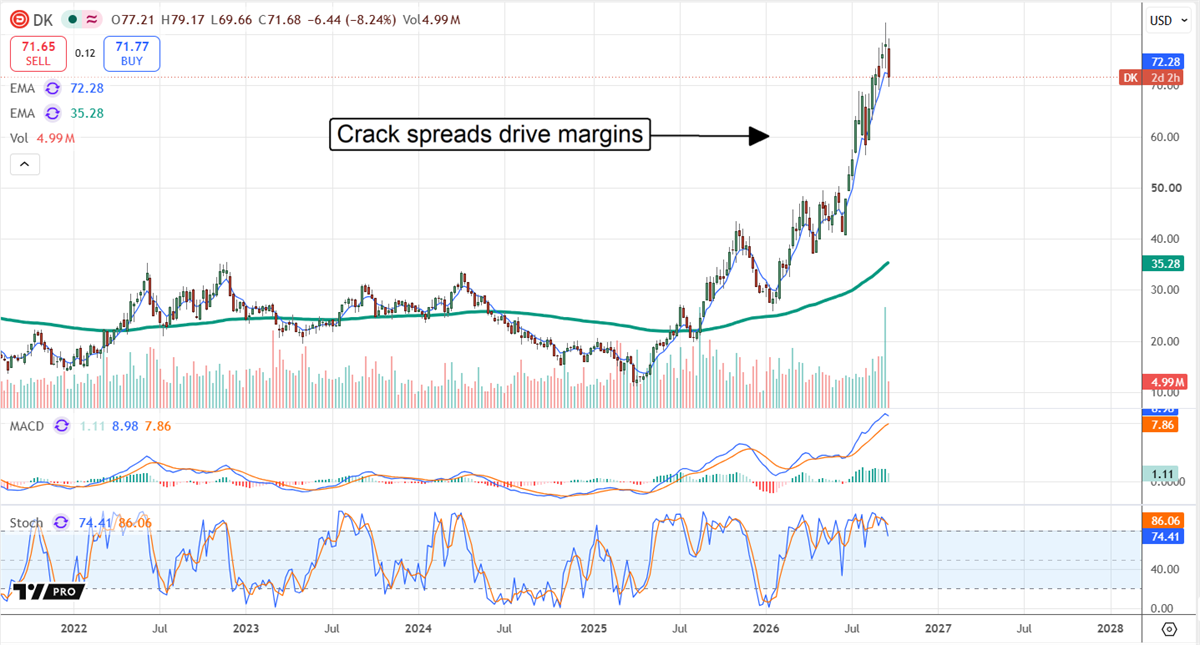
Higher energy prices are affecting cash flow, but crack spreads offset the impact. The crack spread enables wider margins, improved cash flow, and the capacity to execute strategy while paying dividends. Dividends are robust but reliable, yielding in alignment with the S&P 500 average. Institutions own more than 97% of this stock and are accumulating in 2026.
This year’s catalysts include rapidly improving market sentiment. Early 2026 results triggered analyst upgrades and higher price targets, strengthening sentiment and lifting the high end of price targets to $90, 25% upside from late September trading levels.
Looking ahead, analysts are underestimating 2027 results, expecting earnings per share to fall by 50%. They get the impact of lost global refining capacity wrong, and they may also be wrong about the likelihood that crack spreads remain wide through the end of next year. In this scenario, oil prices can implode without significantly hurting refiners, as long as the gap between input and product prices stays wide.
Before you consider Archer Daniels Midland, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Archer Daniels Midland wasn't on the list.
While Archer Daniels Midland currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Looking to profit from the electric vehicle mega-trend? Click the link to see our list of which EV stocks show the most long-term potential.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
