Zebra Technologies NASDAQ: ZBRA is among a growing number of stocks whose prices are imploding for no other reason than failing to exceed expectations.
Zebra Technologies Today
ZBRA
Zebra Technologies
$330.99 +1.49 (+0.45%) As of 12:03 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $199.05
▼
$392.78 - P/E Ratio
- 30.33
- Price Target
- $387.50
The stock plunge after Zebra's Q3 release wasn't due to weak results; on the contrary, the company posted a beat-and-raise quarter. Rather, the price plunge was due to a guidance miss and a perceived structural breakdown in the business that just isn’t happening.
While the company’s adjusted earnings per share (EPS) midpoint for Q4 came in a penny shy of consensus, the bar was set high, and fear-driven sellers are overlooking key elements pointing to sustainable growth, free cash flow, and aggressive share buybacks.
What the market got wrong centers on three factors: guidance, gross margin headwinds, and free cash flow (FCF) generation. Guidance fell short but, again, versus a high bar, with management forecasting persistent strength across regions and channels. Gross margin is a more pressing concern, but even it is only a near-term issue. Gross margin compression is tied to mix and memory costs which, one, don’t signal a structural defect, merely consumer choice, and two, can be compensated for. The company is raising prices to sustain margins and says that pass-through success affirms strong demand.
Zebra Technologies Automates Aggressive Share Count Reduction
Free cash flow matters because it represents the company’s distributable profits, and it is growing. FCF topped $660 million year-to-date (YTD), as of Q3’s end, and is tracking to exceed $1 billion by year’s end. This matters because it enables a fortress-like balance sheet, reinvestments, and aggressive share count reduction. Buybacks topped $640 million YTD, with free cash flow covering them by more than 100%. Looking ahead, investors can expect the company to sustain the aggressive pace, which reduced the count by nearly 7% in the first nine months of the year.
Investors should focus on Zebra's Q3 strengths. Revenue grew by 22% to $1.61 billion, exceeding the consensus by a solid margin. All segments and regions drove strength, led by a nearly 35% increase in Connected Frontline (CF) and an 8.1% increase in Asset Visibility & Automation. Both segments benefited from acquisitions and currency exchange, with organic growth of 15% and 7%, respectively.
Margin news was mixed, with gross margin contracting due to mix and memory costs, and operating margins flat. The net result was nearly $350 million in adjusted EBITDA, a 21.7% margin, and $4.95 in adjusted EPS, up 27.6%, driven by top-line strength and buybacks. If Q4 results exceed the forecast, they will likely reinvigorate market appetite. Reasons to believe the company will outperform include past performance, the low bar management set, pricing actions, and broad-based demand for front-line efficiency and business automation.
Analysts Stay Bullish on Zebra Despite Near-Term Headwinds
Zebra Technologies Today
ZBRAZebra Technologies
$330.99 +1.49 (+0.45%) As of 12:03 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $199.05
▼
$392.78 - P/E Ratio
- 30.33
- Price Target
- $387.50
Analysts are generally bullish on Zebra Technologies, but coverage is modest, with only 15 active analyst ratings tracked by MarketBeat. The post-release analyst response was cautious, with fear centered on near-term headwinds, leading the group into a wait-and-see mode that could linger for several quarters.
As it stands, trends are bullish, coverage is firmer than last year, sentiment is steady, and price targets are edging higher.
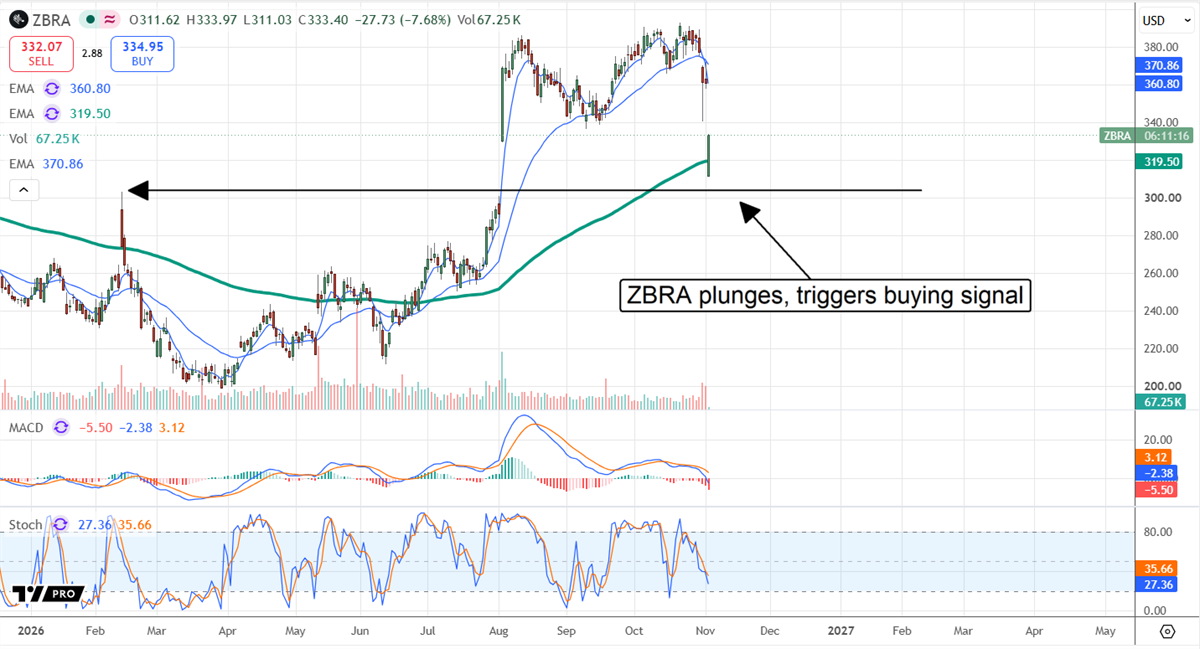
The consensus price target aligns with the high end of a multi-year trading range, while the lowest price target of $310 provides a price floor that may be strong enough to support the action. It aligns with the middle of the trading range and a pair of short-term moving averages. Risks include potential price target reductions, events that can pressure the market lower regardless of where they are set.
Institutions Buy Into ZBRA’s Long-Term Outlook
Institutions also reflect confidence in ZBRA, owning more than 90% of the shares. They also provide a limiting factor for downward price moves, as they have been accumulating shares in 2026. The question is how far the stock price could drop before further buying by the group is triggered.
ZBRA fell about 15% at the start of November, putting it below 15x its current-year forecast and 10x the 2030 consensus estimate, value levels that suggest double-digit upside in the near- to mid-term and triple-digit gains over the long term.
Zebra’s catalysts center on an industry-widehardware refresh cycle. Enterprises are ramping spend after years of tepid activity, focusing on automation and retail/warehouse upgrades. Machine vision is also driving business, with management highlighting an inflection for the segment. New product launches play a role, including advanced computer vision applications and kiosk-oriented services aimed at offsetting labor shortages.
Together, these forces are driving record results, including free cash flow and a guidance upgrade cycle that is likely not over yet. The biggest risk is debt, which is modestly high but could be quickly controlled by diverting free cash flow from buybacks for a short period.
Before you consider Zebra Technologies, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Zebra Technologies wasn't on the list.
While Zebra Technologies currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Looking for higher dividend income in 2027? Discover seven high-yield dividend stocks with attractive payouts, proven dividend histories and growth potential.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
