November is nearly here, and with it has come extra-low stock prices for many leading AI names. Spending fears have driven many high-quality tech stocks to long-term lows, setting them up for big rebounds.
The question is timing, and for many, now is the time. Q2 results and news since then reflect traction, monetization, and cash flow among leading AI-critical names, all of which are expected to improve sequentially over the next six to eight quarters.
Oracle: This Market Is Pricing in a No-Growth Outlook
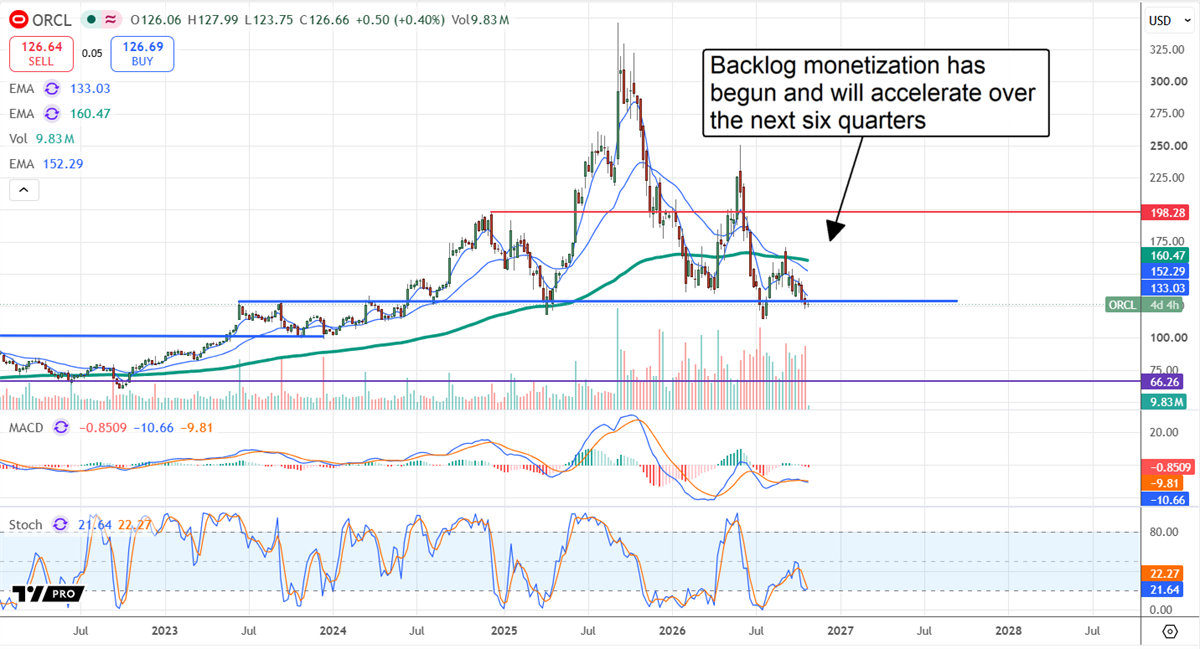
Oracle NASDAQ: ORCL is a compelling buy in November because its blossoming debt has pushed its share price to long-term lows, pricing in nothing but risk and a no-growth environment. The market continues to get it wrong: Oracle’s backlog is swelling, outpacing debt, and monetization has begun.
Oracle Today
$130.34 -9.22 (-6.61%) As of 02:43 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $114.50
▼
$265.81 - Dividend Yield
- 1.53%
- P/E Ratio
- 20.35
- Price Target
- $248.41
The Jupiter New Mexico project presents a potential hurdle to growth, but it accounts for only a small portion of the company's backlog. While the exact amount hasn’t been confirmed, it is estimated at approximately 3.5% of the backlog, a drop in a much larger bucket.
Monetization is the key. The company revealed monetization of early AI investments in its fiscal Q1 2027 earnings report, providing enhanced cash flow and adjusted margins to offset the impact of spending. The narrative for the remainder of 2026 and 2027 is that monetization will continue and accelerate, with a significant acceleration expected by year’s end.
Upcoming catalysts include the fiscal Q2 release, expected in early December, and the reality of Oracle’s strategy. It leverages client, landlord, and partner capital for its build, so the debt figures don’t really tell the whole story. In this scenario, end-game infrastructure is far larger (and more valuable) than the market realizes.
Salesforce: Recovering From a Case of SaaS-Pocalypse Fear
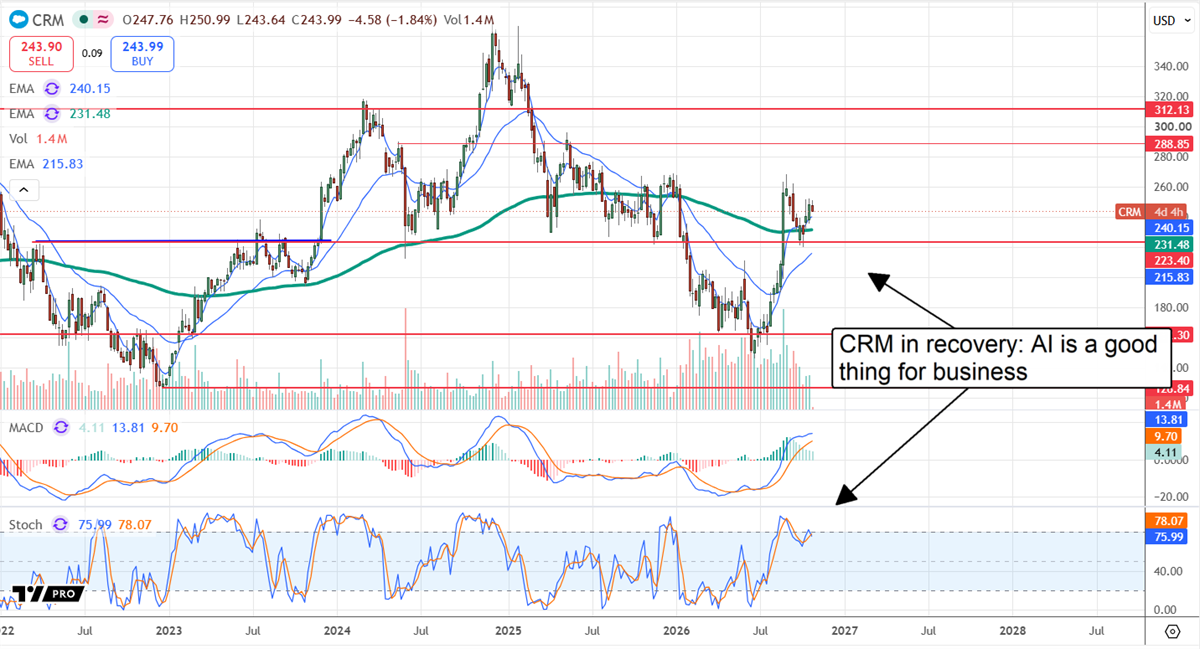
Salesforce NYSE: CRM is an attractive buy in November because the market has finally moved past its SaaS-Pocalypse fear and begun reevaluating the stock.
Salesforce Today
$229.41 -1.49 (-0.64%) As of 02:43 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $146.32
▼
$269.11 - Dividend Yield
- 0.77%
- P/E Ratio
- 20.87
- Price Target
- $278.98
Salesforce is gaining traction with agentic AI, which depends on the company’s data capabilities. Like Oracle, which trades at an even deeper discount, this stock is valued as if it isn’t growing, outperforming, and driving reliable cash flow. Forward estimates have CRM trading around 10x the five-year consensus, suggesting at least 100% upside over the next few years.
Investors should not misread Salesforce’s position; it isn’t a high-growth engine anymore, though growth remains central to the outlook. It has transitioned into a mature, blue-chip tech powerhouse with reliable cash flow and capital returns.
Capital returns include a dividend but focus on share buybacks. Buybacks reduced the count by 14% year over year in Q2, including an accelerated repurchase plan, and are expected to continue at a brisk pace in the upcoming quarters, driving shareholder leverage.
Zscaler: Regaining Market Confidence With AI Driving Business
Zscaler's NASDAQ: ZS share price fell earlier this year after it announced unexpected C-suite departures and reduced its guidance.
Zscaler Today
$235.17 -12.65 (-5.10%) As of 02:43 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $114.63
▼
$336.99 - Price Target
- $240.14
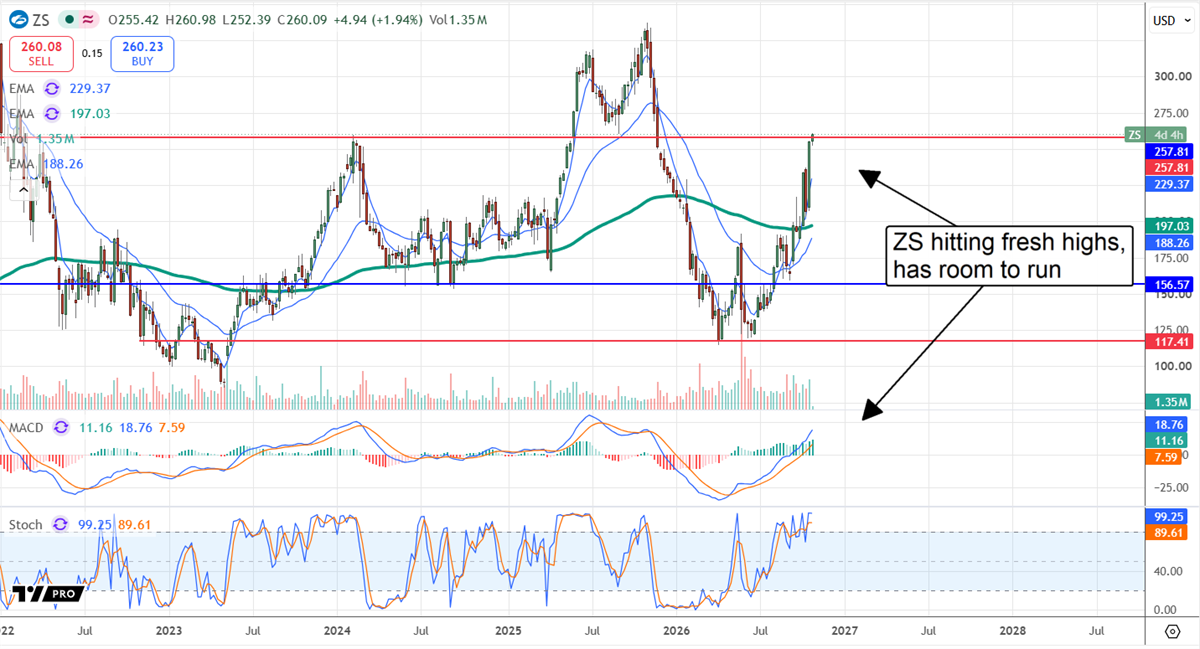
However, the company has recovered, hired fresh faces in its sales department, and is reinvigorating market appetite for its stock. Key drivers include demand for its zero-trust architecture, its ability to secure AI, and its talent for generating free cash flow.
Analysts have been bullish on Zscaler as of late October and have reversed the downtrend in price targets. Their consensus price target forecasts a slim downside, but analyst trends are firming, leading to the high end and a significant technical breakout for this market.
Valuation carries some risk. Trading above 50x earnings, ZS isn’t a cheap stock, but the outlook is robust. Like Oracle and Salesforce, Zscaler trades at pennies on the dollar compared to long-term forecasts. It has become an execution story; it only needs to grow into its forecast for the stock to rise.
Applied Digital: Extreme Lows Are Extremely Attractive
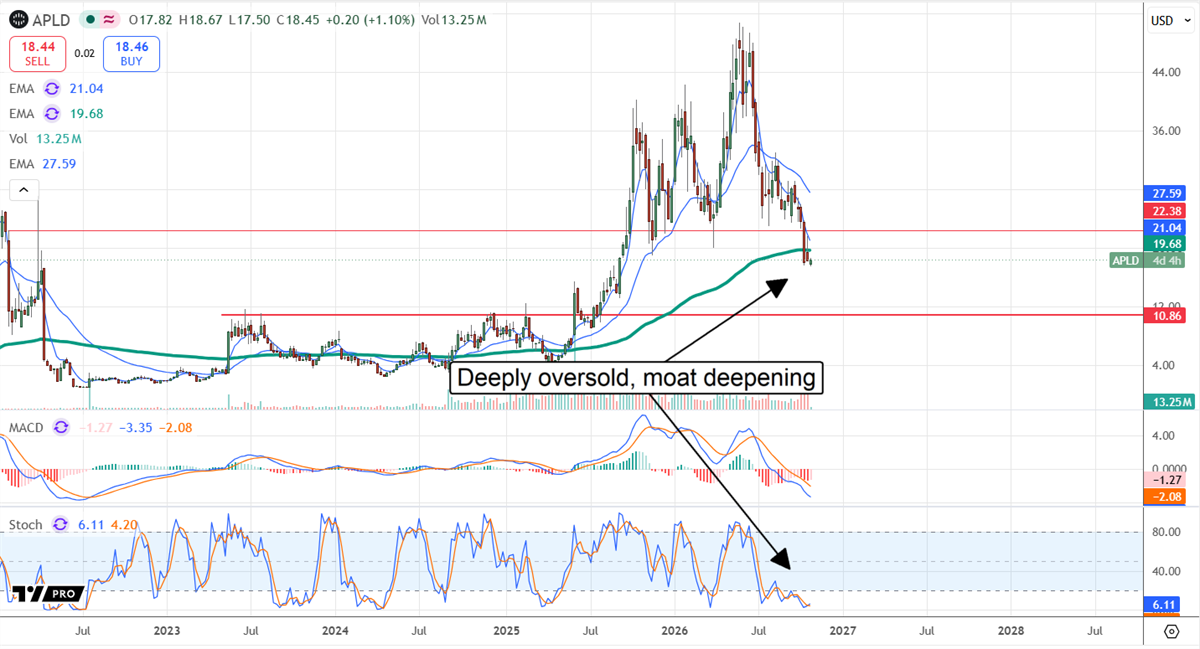
Applied Digital NASDAQ: APLD has risks, primarily in debt and execution, but, like Oracle, it has begun to monetize AI assets and has a long runway ahead.
Applied Digital Today
$17.26 -2.15 (-11.08%) As of 02:43 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $17.25
▼
$50.72 - Price Target
- $57.75
It is a compelling buy because of its low stock price and expected catalysts, including capacity ramp, monetization, and adjusted results.
Investors should consider Applied Digital's moat. Its data center projects are backed by long-term contracts with hyperscale-quality clients; additionally, the business is diversifying and has a first-mover advantage.
The company's data center projects face hurdles but are established, progressing, and have power.
The focus is now on North Dakota, where power is ample, the local population is more welcoming, and there is room to expand.
Early projects and first-mover neoclouds are protected by increasingly high barriers to entry, including real estate, regulatory hurdles, power supply, environmental constraints, and local pushback. It will take time, but Applied Digital is well-positioned to monetize AI, drive cash flow for investors, and push its stock price to fresh highs.
Amprius Technologies: Execution Phase Has Begun
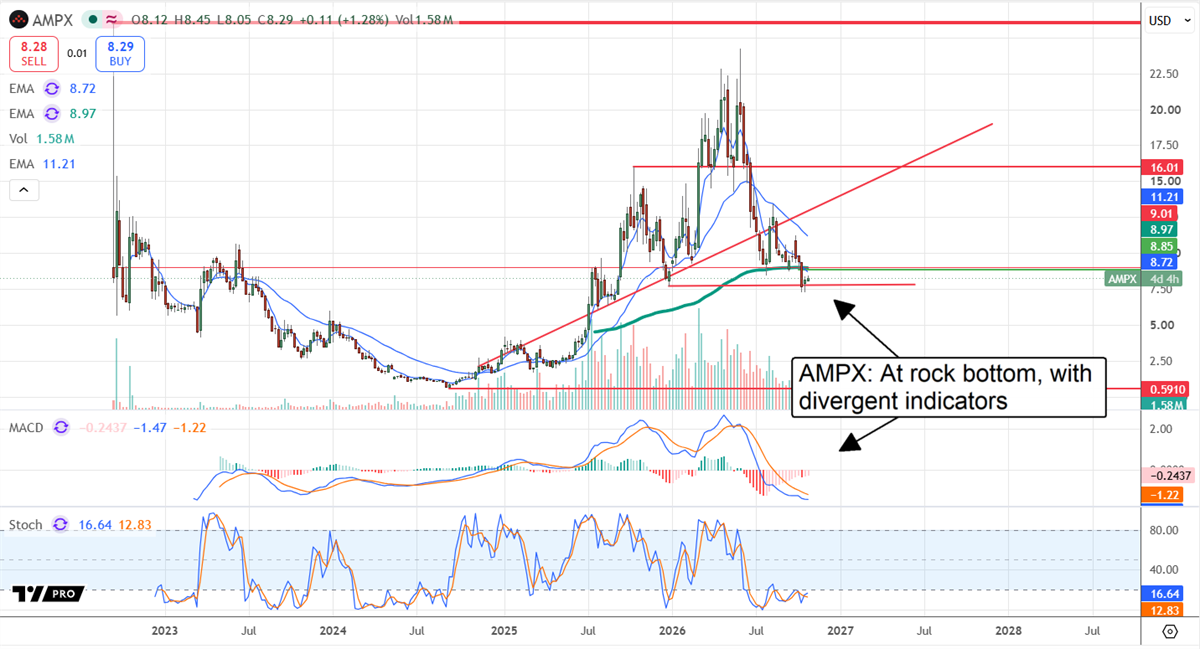
Amprius Technologies NYSE: AMPX is also trading at long-term lows, offering an attractive entry point as the company transitions from speculation to execution.
Amprius Technologies Today
AMPX
Amprius Technologies
$8.35 -0.80 (-8.70%) As of 02:42 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $7.26
▼
$24.23 - Price Target
- $21.42
Production is ramping up, and a $75 million government grant is now in play to expand domestic battery manufacturing that meets National Defense Authorization Act sourcing requirements.
Upcoming results, including the mid-November Q3 release, will reflect these developments, providing further insight into revenue growth and profitability. Profitability is a crucial component, with the inflection to adjusted profits expected over the coming year.
Catalysts for share prices include increased analyst coverage. More coverage matters for several reasons, including greater confidence, conviction, and institutional interest. Institutions follow the analysts' lead and can quickly drive share prices higher. Institutional interest in AMPX is still tepid but can change quickly. Outlook-validating news and its impact on the analysts would both be triggers.
Before you consider Oracle, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Oracle wasn't on the list.
While Oracle currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
Oil still powers the global economy, but AI is reshaping the energy opportunity. Discover seven stocks spanning traditional energy, infrastructure, and next-generation power.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.

