Deckers Outdoor Corp. NYSE: DECK delivered a mixed second-quarter earnings report for its fiscal year 2027 (FY2027) on Oct. 22. Earnings beat expectations. Revenue of $1.48 billion fell just short of estimates of $1.51 billion. Management also cut its full-year sales outlook for its HOKA and UGG brands.
Deckers Outdoor Today
$80.37 0.00 (0.00%) As of 03:23 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $77.20
▼
$122.29 - P/E Ratio
- 10.65
- Price Target
- $105.81
Investors reacted decisively. DECK stock fell 5% on Oct. 23 to close at $81.01. That left shares just above their September low.
But the headline reaction missed a bigger point. The sell-off didn't start with this report. DECK lost roughly 30% between late July and mid-September. Investors were pricing in slower growth long before management confirmed it. That changes how to read the guidance cut. Bad news the market already expected is not really new information. And there is a reasonable case that Deckers set its new outlook low on purpose.
The perception is that Deckers is a growth story in decline. The fundamentals show a company that is still growing, still expanding margins, and buying back stock at a rapid pace.
Deckers has a long record of guiding cautiously and then beating. If that pattern holds, DECK is set up to clear a low bar rather than chase a high one.
The Damage Was Done Before the Report
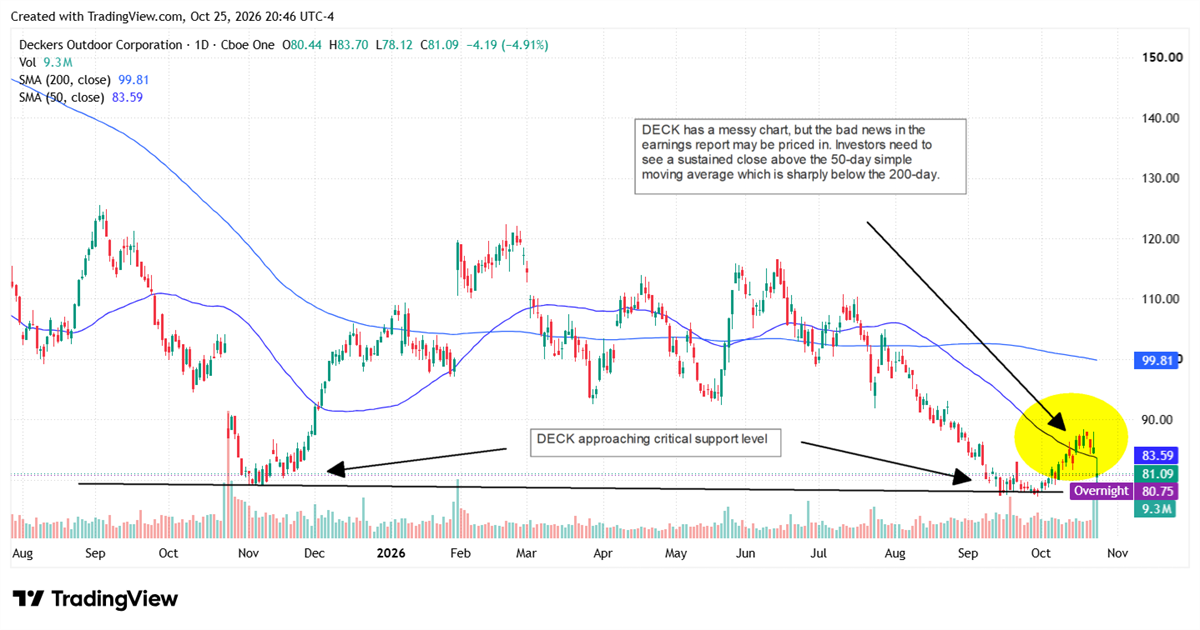
DECK traded near $110 after its first-quarter report in late July. By mid-September, shares had dropped below $80. That decline came without any new guidance from the company.
The stock then bounced toward $88 heading into earnings. Friday's drop erased that rally, but it did not break new ground. Shares dipped to $78.12 during the session and still held above the September low.
There is technical work left to do. DECK trades below its 50-day moving average of $83.59. It also sits well below its 200-day average of $99.81, which continues to trend lower. Reclaiming the 50-day would be the first sign of repair.
Still, the price action matters. A stock that holds its lows after a guidance cut often signals that sellers are running out of steam.
The Quarter Was Better Than the Headline
Revenue rose 3.5% to a record $1.48 billion. HOKA sales climbed 6.8% to $677.2 million. UGG grew 3.5% to $786.4 million. Both flagship brands are still growing.
The revenue shortfall was modest. Analysts expected about $1.51 billion. Management tied roughly $22 million of the gap to shipping delays from a European logistics transition. That points to more of a timing issue, not a demand collapse.
Margins were the real highlight. Gross margin jumped to 60.5% from 56.2%. Tariff refunds supplied about 310 basis points of that gain. The rest, about 120 basis points, came from selling more products at full price instead of chasing discounts.
Earnings per share (EPS) came in at $2.31. Excluding the refund benefit, adjusted EPS was about $2.03. That still beat the consensus estimate of $1.79 and grew 11.5% from a year ago.
A Low Bar, Set on Purpose
Now look at the new outlook. Deckers expects fiscal 2027 sales of $5.700 billion to $5.725 billion. The prior range was $5.86 billion to $5.91 billion. HOKA growth is now expected in the high single digits. UGG is expected to grow in the low single digits.
Full-year EPS guidance rose to $7.80 to $7.95. But that includes about 52 cents from tariff refunds. Without them, the range is roughly $7.28 to $7.43. That is slightly below the prior outlook.
On paper, that looks like a downgrade. But consider the track record. Deckers has beaten EPS estimates in each of its last five quarters, usually by double-digit percentages. A company that keeps beating is guiding with room to spare.
Management also has every incentive to stay cautious. In a weak consumer market, missing a raised forecast costs far more than beating a lowered one.
There is a hidden upside, too. The outlook includes only the tariff refunds received through Oct. 8. Any further refunds that would add to the results are not yet reflected in the guidance.
Buying Back Stock at a Discount
Deckers is putting its cash to work. It repurchased $637.5 million of stock in the first half of fiscal 2027, at an average price of $98.77. The company carries no debt.
About $4.4 billion remains on the buyback authorization. At today's price, that equals roughly 40% of the company's market value. The current outlook assumes $1 billion in repurchases this year.
Valuation adds to the case. At $81, DECK trades near 11 times the midpoint of its full-year EPS guidance, excluding tariff refunds. That is a low multiple for a debt-free company with operating margins above 20% and two growing global brands.
The Risks Are Real; So Is the Balance Sheet
The bear case is real. Direct-to-consumer comparable sales fell 6.4%. Domestic sales slipped 0.4%. HOKA's growth rate keeps slowing, and that remains the stock's biggest long-term question.
There is also a caveat to the lowball thesis. Second-quarter revenue came in below management's own internal expectations, not just Wall Street's. Conservative guidance only works if the company can hit it.
Deckers Outdoor Stock Forecast Today
12-Month Stock Price Forecast:$105.8133.00% UpsideHoldBased on 25 Analyst Ratings | Current Price | $79.56 |
|---|
| High Forecast | $184.00 |
|---|
| Average Forecast | $105.81 |
|---|
| Low Forecast | $70.00 |
|---|
Deckers Outdoor Stock Forecast DetailsThe Deckers analyst forecasts on MarketBeat continue to shift to a bearish stance. The consensus rating of 26 analysts is Hold, with 11 Holds and four Sell ratings.
Even so, the balance of risk has shifted. The sell-off began months before this report.
The guidance cut confirms what the stock had already priced in. And the new bar looks low enough to clear.
For patient investors, that gap between perception and the company's fundamentals is the opportunity.
The perception is a fading growth story. The fundamentals show a profitable, debt-free company buying back its own shares at a discount.
Before you consider Deckers Outdoor, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Deckers Outdoor wasn't on the list.
While Deckers Outdoor currently has a Hold rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
The AI boom is creating opportunities across semiconductors, cloud computing, enterprise software, infrastructure, cybersecurity, and automation.
Inside this report, you’ll find 10 companies positioned to benefit as artificial intelligence moves from hype to real-world deployment and becomes a core growth driver for corporate America.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.

