Advanced Micro Devices Today
AMD
Advanced Micro Devices
$482.49 -1.41 (-0.29%) As of 02:22 PM Eastern
This is a fair market value price provided by Massive. Learn more. - 52-Week Range
- $188.22
▼
$658.52 - P/E Ratio
- 124.14
- Price Target
- $618.62
MI450 and Helios helped drive results, and management expressed confidence in its supply chain. Looking to 2027, AMD expects revenue growth to accelerate to more than 80% and for operating margins to continue expanding. As it is, five major customers are already running models and workloads on Helios, including Meta Platforms NASDAQ: META, Microsoft NASDAQ: MSFT, Oracle's NYSE: ORCL Cloud Infrastructure, OpenAI, and Anthropic. AMD's expanded partnership with Meta and agreement with Anthropic also highlight the scale of its customer commitments.
Advanced Micro Devices Outperforms, Widens Margin in Q3
Advanced Micro Devices' Q3 earnings results cement its position as a leading provider of AI infrastructure hardware. Revenue grew 44.6% to nearly $13.4 billion, about 2% above expectations, driven by sales of Ryzen mobile processors. All Embedded subsegments produced growth, including aerospace, defense, automotive, and industrial.
Within Client and Gaming, Gaming is the sore spot, down 40% year over year but only 5.8% of total revenue. Client, the more important subsegment, slowed to 7% but continues to grow, driven by advances in edge AI. All Embedded subsegments produced growth, including aerospace, defense, automotive, and industrial.
Gross and operating margins also expanded, driven by higher-margin next-gen products and operating leverage. Gross margin improved by 2 percentage points and operating margin by 5 percentage points, leaving adjusted operating and adjusted net income up 75% and 77%, respectively. Adjusted earnings per share (EPS) rose 74%, beating forecasts by roughly 8%.
Guidance could provide two catalysts for shares, near-term and long-term. The near-term catalyst is Q4 revenue guidance roughly 5% above MarketBeat’s consensus midpoint. The long-term catalyst is management's expectation for faster growth in 2027. Further guidance increases could support analyst upgrades if AMD delivers on its forecasts.
Analysts Reaffirm Upside Potential: AMD Turns Into an Execution Story
Advanced Micro Devices Stock Forecast Today
12-Month Stock Price Forecast:$608.2221.68% UpsideModerate BuyBased on 44 Analyst Ratings | Current Price | $499.84 |
|---|
| High Forecast | $1,250.00 |
|---|
| Average Forecast | $608.22 |
|---|
| Low Forecast | $260.00 |
|---|
Advanced Micro Devices Stock Forecast DetailsAnalyst ratings and price targets remain generally bullish, but include several reduced price targets, with analysts citing strengths but worrying about valuation multiple compression. Even so, target reductions are offset by reaffirmed and increased targets, with the
consensus near $608. The consensus target implies approximately 20% upside from the pre-release close, enough to put AMD near its all-time high.
The question is whether it can move to highs, and the trends suggest that it can. Not only is business growing, accelerating, and outperforming expectations, but forward estimates offset today’s high valuation. At its Nov. 3 closing price, AMD traded near 60x consensus 2026 adjusted earnings, commanding a substantial premium to the broader market. However, sustained earnings growth could significantly reduce that multiple over time and support further upside, assuming continued execution on its AI customer commitments.
Cash Flow Drives Value: Premium Deserved But Risk Remains for AMD Market
Advanced Micro Devices deserves a premium because of its position and cash flow quality. Balance sheet highlights reflect both strengths, with liquid assets increasing across the board, offsetting liabilities and improving equity. The cash balance grew nearly 35% year-to-date, is enough to offset long-term debt, and leaves the company in a nimble financial position to execute its strategy, including acquisitions. Recent acquisition agreements include the planned acquisition of World Labs and a separate deal for Taalas, which would strengthen AMD's model research and specialized inference-chip capabilities, respectively.
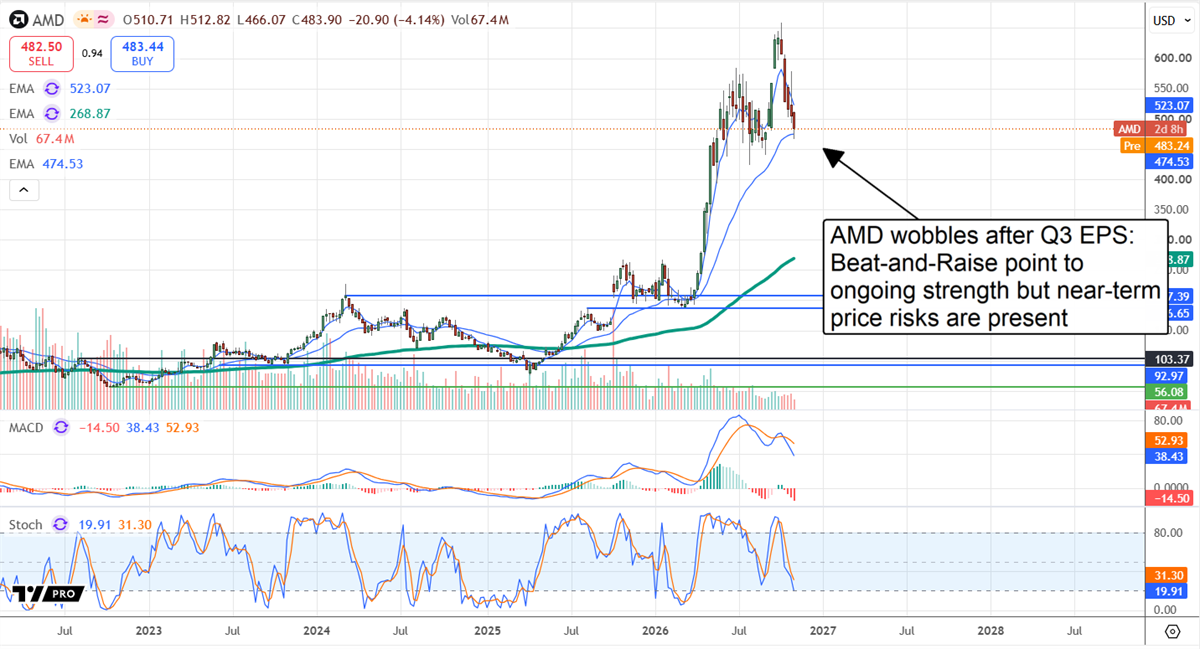
AMD's stock chart shows mixed post-release price action, revealing lingering uncertainty in the market. The initial reaction was a rise of as much as 7%, but the later response was a sell-off, pointing to continued near-term volatility. The risk is that price action falls below the 30-day exponential moving average (EMA), which could lead the market into a sharper correction. Despite its long-term growth potential, AMD is trading well above its 150-week EMA and could revert to it, as many other AI stocks have done.
What the market may be underestimating is the strength of central processing unit (CPU) demand. As AI workloads shift toward inference and agentic applications, the ratio could narrow from four to eight graphics processing units (GPUs) per CPU to closer to one GPU per CPU. AMD expects the server CPU market to reach approximately $220 billion by 2030, driven partly by this growing demand. With this in play, AMD's already ambitious outlook could leave room for additional growth if demand continues to expand.
Before you consider Advanced Micro Devices, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis. MarketBeat has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and Advanced Micro Devices wasn't on the list.
While Advanced Micro Devices currently has a Moderate Buy rating among analysts, top-rated analysts believe these five stocks are better buys.
View The Five Stocks Here
AI spending is reshaping the market, and the opportunity extends far beyond the biggest chipmakers. Discover 10 stocks set to benefit from powerful trends in AI infrastructure, cloud computing, energy, capital returns, and consumer growth this fall.
Get This Free Report
Continue following MarketBeat
Add MarketBeat as your preferred source on Google to see our latest stories in your feed.
